Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

As the region scales from a $25.7 billion valuation in 2025 to an astounding $36.7 billion by 2030, the South Asian media market is undergoing a historic transformation driven by a 7.4% CAGR, massive mobile penetration, and a seismic shift toward personalized, digital-first entertainment.

  • Explosive Market Growth: The Indian and South Asian Entertainment & Media market will surge to $36.7 billion by 2030, operating at a robust 7.4% CAGR—nearly double the global average of 4%.
  • SVOD Supremacy: India is projected to overtake China as the global epicenter for Subscription Video on Demand (SVOD), reaching 358 million individual subscriptions.
  • The Linear TV Collapse: Traditional television is experiencing a structural $8 billion cumulative regional revenue decline as audiences permanently migrate to online video and Connected TV (CTV).
  • Monetization Evolution: Platforms are increasingly adopting hybrid models—balancing AVOD, SVOD, and FAST—to cater to diverse economic segments across urban and rural tiers.

When we look at the shifting tides of global media, we are witnessing a historic rewriting of the playbook. The epicenter of entertainment is decisively pivoting toward the Global South. Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem is not merely a statistical projection; it is a testament to how billions of consumers across India, Bangladesh, Pakistan, and neighboring territories are consuming content. In our experience working alongside digital media pioneers, the sheer velocity of this expansion leaves legacy western models scrambling to adapt.

The macroeconomic fundamentals driving this shift are extraordinary. According to recent industry reports, the regional Entertainment & Media market is scaling from $25.7 billion in 2025 to a staggering $36.7 billion by 2030. What makes this trajectory unique is its compound annual growth rate (CAGR) of 7.4%, which outpaces the global average of 4% by almost double. This momentum is fueled by a trinity of infrastructure catalysts: ultra-affordable mobile data tiers, rapid smartphone saturation, and expanding digital bridges connecting rural hamlets to bustling urban centers.

Behind these massive economic figures lies a fundamental change in human behavior. Consumers are no longer passive recipients of scheduled linear broadcasts. Instead, they are active curators of their own media diets, demanding hyper-personalized, on-demand libraries that reflect their unique cultural nuances. As streaming platforms innovate to capture this vast audience, understanding the structural dynamics of the digital entertainment landscape South Asia 2030 becomes essential for any serious media operator, investor, or content creator.
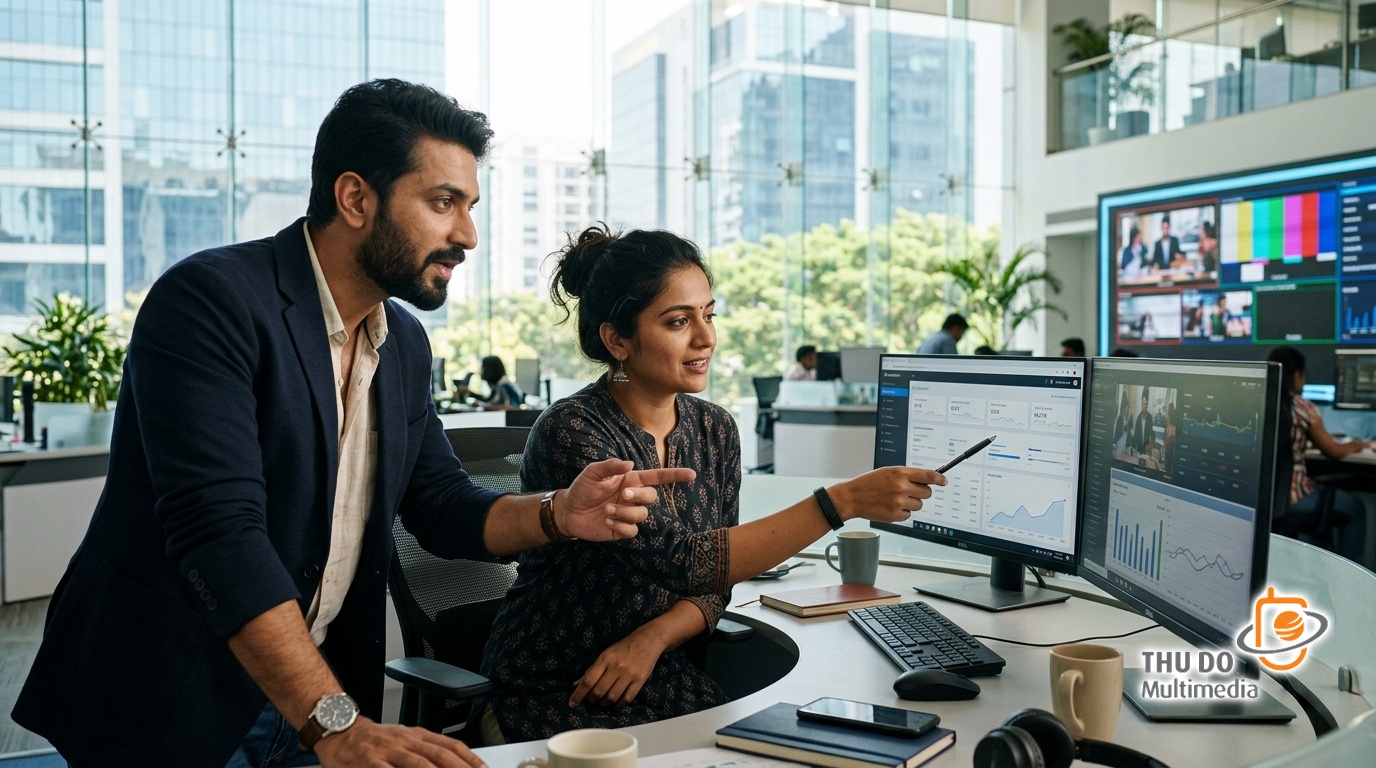
Indian media executives analyzing real-time streaming metrics in a modern Bengaluru tech facility.

Market Scale and SVOD Dominance: Overtaking Global Giants

The sheer scale of the transformation taking place across the subcontinent is unprecedented. India is rapidly cementing its status as the new global capital for subscription-based streaming, poised to overtake China as the largest market for Subscription Video on Demand (SVOD). Projections indicate that the country will hit an astounding 358 million individual SVOD subscriptions by the turn of the decade. This milestone shatters historical assumptions about willingness-to-pay in developing economies and proves that digital consumers are fully willing to invest in premium, ad-free streaming experiences when the value proposition is right.

This meteoric rise is accompanied by a profound behavioral migration: the shift from shared household television sets to personal mobile screens and Connected TVs (CTV). Historically, the Indian OTT platforms and streaming ecosystem market operated on a modest valuation baseline of around USD 4.5 billion. Today, that baseline looks like a distant stepping stone. As personal device ownership surges among Gen Z and millennial demographics, the demand for expansive, on-demand content libraries has multiplied exponentially, forcing platforms to continuously upgrade their content acquisition and production budgets.

Analyzing the future of Indian video streaming industry 2030, industry leaders note that subscriber acquisition is no longer just about volume—it is about retention and ARPU (Average Revenue Per User) expansion. Platforms that once relied solely on vanity metrics are now focusing on deep engagement loops, proprietary intellectual property, and frictionless payment gateways.

“The democratization of high-speed mobile data across South Asia has unlocked a billion-plus consumer base that demands premium, culturally resonant storytelling on their own terms. We are not just witnessing market growth; we are watching the total reinvention of how entertainment is consumed and valued.” — Senior Media Analyst, Regional OTT Insights

The Decline of Linear TV and the Rise of Digital Advertising

While the digital streaming ecosystem soars, traditional linear television is enduring an unprecedented structural contraction. Across the region, legacy broadcasters face an estimated $8 billion cumulative revenue decline. This drop is not a temporary dip; it represents a permanent migration of eyeballs and advertising dollars toward online video and Connected TV (CTV) environments. According to media market analysts, China, Japan, and India combined account for nearly 70% of this regional linear television drop, forcing traditional media conglomerates to aggressively cannibalize their own legacy models or risk total irrelevance.

At the same time, the digital advertising ecosystem is experiencing a historic boom. Driven by sophisticated programmatic buying, hyper-targeted consumer data, and interactive ad formats, regional internet advertising revenue is projected to nearly double, jumping from $7.5 billion in 2025 to $14.3 billion by 2030. Brands are aggressively reallocating budgets away from decaying linear channels and pouring them into digital and CTV inventories where measurable engagement and direct-to-consumer attribution are possible.

For traditional operators attempting to navigate these South Asian OTT market trends and forecast models, survival depends on rapid digital transformation. Companies that cling to legacy ad-sales models are finding themselves sidelined as agile, digital-first streaming networks capture the lion’s share of brand marketing budgets. The writing is on the wall: ad dollars follow attention, and attention has firmly crossed over to digital screens.
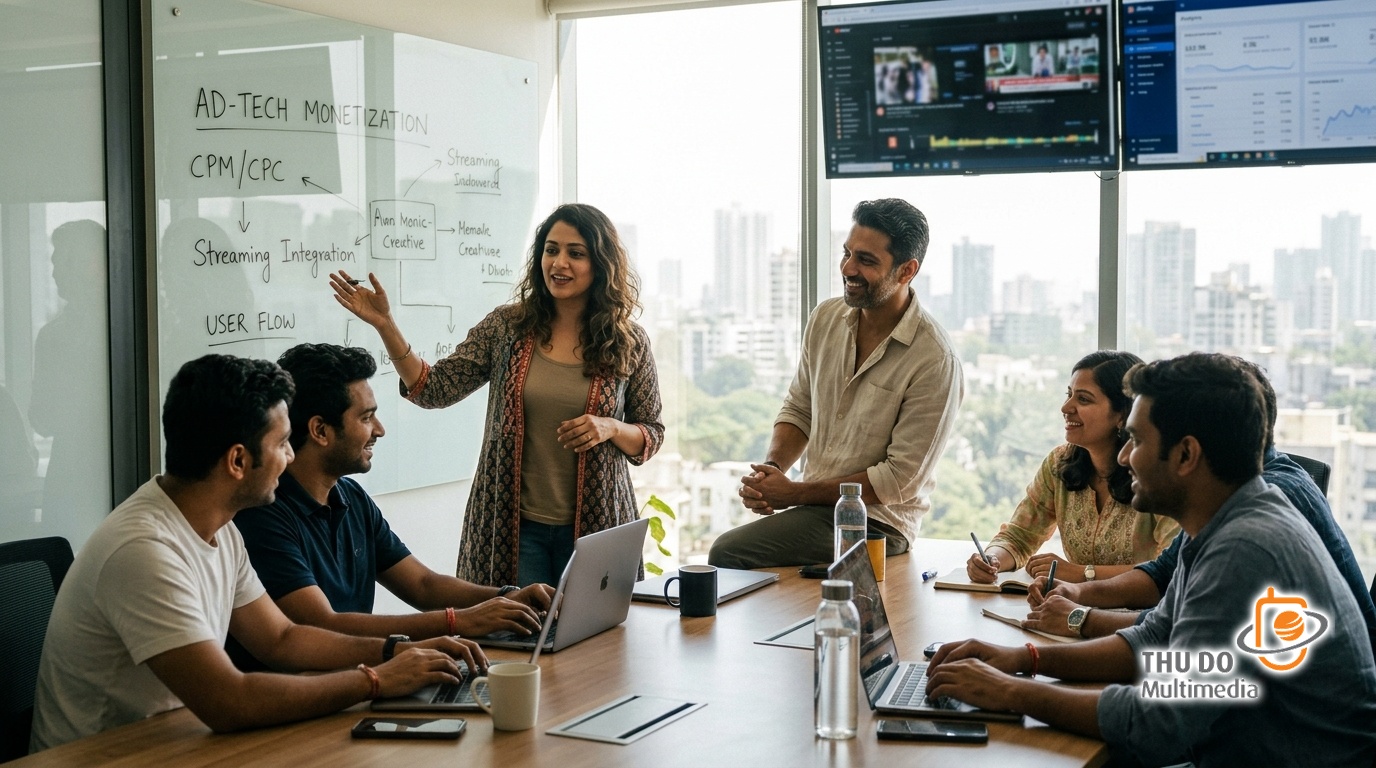
Creative media executives discussing digital advertising strategies in a sunlit Mumbai office.

How is Content Localization Driving Regional Language Streaming Growth?

Gone are the days when a one-size-fits-all, Hindi-centric or English-centric content strategy could capture the breadth of the South Asian market. Today, audiences from Mumbai to Dhaka demand on-demand libraries that deeply reflect their local cultures, regional dialects, and lived experiences. This hyper-localized demand has turned regional language streaming growth in India into the single most powerful engine for subscriber acquisition outside major metropolitan hubs.

The battleground for subscriber growth has officially shifted to Tier-2 and Tier-3 cities. While urban centers like Mumbai, Delhi, and Bengaluru remain critical hubs for tech-savvy youth engagement and premium tech adoption, the next billion users reside in smaller towns and rural districts. For these consumers, content in regional languages—such as Tamil, Telugu, Malayalam, Bengali, Marathi, and Kannada—is non-negotiable. Streaming platforms that invest in authentic, locally produced regional narratives are seeing exponential engagement spikes compared to those relying solely on dubbed Hollywood or Bollywood blockbusters.

To execute this effectively, leading streaming operators are decentralizing their production pipelines. They are partnering with regional creators, independent production houses, and local storytellers who understand the subtle cultural nuances of specific districts. This localized approach not only drives unprecedented user acquisition but also fosters deep emotional loyalty, transforming casual viewers into lifelong platform advocates.

What Are the Winning Monetization Strategies in the AVOD vs SVOD Ecosystem?

Monetizing a diverse market of over a billion digital consumers requires a nuanced, multi-pillared strategy. The AVOD vs SVOD ecosystem in South Asia is no longer an “either/or” proposition; rather, it is a sophisticated matrix designed to capture every socioeconomic tier. The core monetization pillars—Subscription Video on Demand (SVOD), Advertising Video on Demand (AVOD), Transactional Video on Demand (TVOD), and Free Ad-Supported Streaming TV (FAST)—are being deployed in tandem by forward-thinking platforms.

SVOD continues to hold its ground as a premier segment, fueled by a rapidly growing urban middle class that increasingly prefers ad-free viewing experiences, pristine 4K resolution, and exclusive early access to blockbuster premieres. However, for price-sensitive demographics, AVOD and FAST models serve as the ultimate acquisition funnel. By offering robust, ad-supported tiers, platforms can monetize users who are reluctant to pay monthly subscription fees, effectively turning volume into high-yield ad inventory.

Implementing effective monetization strategies for Indian OTT services requires platforms to adopt flexible hybrid pricing models. For instance, brands utilizing enterprise solutions like StreamVibe OTT Suite can seamlessly toggle between ad-supported and premium subscription tiers based on real-time user behavior and demographic profiling. This flexibility allows operators to maximize ARPU while ensuring that no potential viewer is priced out of the ecosystem.
Indian streaming technology engineer optimizing platform monetization workflows in a modern Delhi office.

What is the Impact of 5G, AI, and CTV on Indian Streaming Platforms?

As data consumption hits unprecedented highs, technological infrastructure is evolving to keep pace. The impact of 5G on Indian streaming platforms has been transformative, enabling ultra-low latency, buffer-free HD and 4K streaming even in densely populated urban environments. Combined with the rapid expansion of Connected TV (CTV) households, 5G is redefining the living room experience, turning traditional television sets into smart, interactive digital entertainment hubs.

Simultaneously, Artificial Intelligence (AI) has become the invisible engine powering user retention. Platforms are no longer relying on basic chronological recommendations; instead, they utilize advanced machine learning algorithms to deliver bespoke, real-time content recommendations, localized subtitle generation, and dynamic ad insertion. These AI-driven personalization engines analyze thousands of micro-behaviors—from viewing time to click-through rates—to ensure every user opens the app to a uniquely tailored homepage.

Of course, this rapid technological expansion operates within a structured regulatory framework. Platforms must navigate governance guidelines such as the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021. Issued by the Ministry of Electronics and Information Technology (MeitY), these rules mandate robust self-regulation and a three-tier grievance redressal mechanism. Balancing creative freedom with regulatory compliance has become a core competency for sustainable streaming operations across the region.


Câu hỏi thường gặp

  • Q: What will be the size of the Indian and South Asian streaming market by 2030?
    • A: The overall Entertainment & Media market in India and South Asia is projected to reach $36.7 billion by 2030, growing at a robust 7.4% CAGR from its $25.7 billion baseline in 2025.
  • Q: Which country is expected to have the most SVOD subscriptions by 2030?
    • A: India is forecasted to overtake China as the largest market for Subscription Video on Demand (SVOD), reaching 358 million individual subscriptions.
  • Q: How is linear television affected by the rise of OTT streaming in South Asia?
    • A: Linear television is experiencing a structural decline, facing an $8 billion cumulative regional revenue decline as audiences permanently migrate to digital platforms and Connected TV (CTV).
  • Q: What role do regional languages play in the growth of Indian OTT platforms?
    • A: Regional language content acts as a primary growth driver, helping streaming services capture audiences outside major metro areas and fulfilling the intense demand for localized, culturally relevant storytelling.
  • Q: What are the primary monetization models used in the South Asian streaming ecosystem?
    • A: Platforms utilize a dynamic mix of Subscription Video on Demand (SVOD), Advertising Video on Demand (AVOD), Transactional Video on Demand (TVOD), and Free Ad-Supported Streaming TV (FAST) models to cater to diverse economic segments.
Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

As the region scales from a $25.7 billion valuation in 2025 to an astounding $36.7 billion by 2030, the South Asian media market is undergoing a historic transformation driven by a 7.4% CAGR, massive mobile penetration, and a seismic shift toward personalized, digital-first entertainment.

  • Explosive Market Growth: The Indian and South Asian Entertainment & Media market will surge to $36.7 billion by 2030, operating at a robust 7.4% CAGR—nearly double the global average of 4%.
  • SVOD Supremacy: India is projected to overtake China as the global epicenter for Subscription Video on Demand (SVOD), reaching 358 million individual subscriptions.
  • The Linear TV Collapse: Traditional television is experiencing a structural $8 billion cumulative regional revenue decline as audiences permanently migrate to online video and Connected TV (CTV).
  • Monetization Evolution: Platforms are increasingly adopting hybrid models—balancing AVOD, SVOD, and FAST—to cater to diverse economic segments across urban and rural tiers.

When we look at the shifting tides of global media, we are witnessing a historic rewriting of the playbook. The epicenter of entertainment is decisively pivoting toward the Global South. Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem is not merely a statistical projection; it is a testament to how billions of consumers across India, Bangladesh, Pakistan, and neighboring territories are consuming content. In our experience working alongside digital media pioneers, the sheer velocity of this expansion leaves legacy western models scrambling to adapt.

The macroeconomic fundamentals driving this shift are extraordinary. According to recent industry reports, the regional Entertainment & Media market is scaling from $25.7 billion in 2025 to a staggering $36.7 billion by 2030. What makes this trajectory unique is its compound annual growth rate (CAGR) of 7.4%, which outpaces the global average of 4% by almost double. This momentum is fueled by a trinity of infrastructure catalysts: ultra-affordable mobile data tiers, rapid smartphone saturation, and expanding digital bridges connecting rural hamlets to bustling urban centers.

Behind these massive economic figures lies a fundamental change in human behavior. Consumers are no longer passive recipients of scheduled linear broadcasts. Instead, they are active curators of their own media diets, demanding hyper-personalized, on-demand libraries that reflect their unique cultural nuances. As streaming platforms innovate to capture this vast audience, understanding the structural dynamics of the digital entertainment landscape South Asia 2030 becomes essential for any serious media operator, investor, or content creator.

Indian media executives analyzing real-time streaming metrics in a modern Bengaluru tech facility.

Market Scale and SVOD Dominance: Overtaking Global Giants

The sheer scale of the transformation taking place across the subcontinent is unprecedented. India is rapidly cementing its status as the new global capital for subscription-based streaming, poised to overtake China as the largest market for Subscription Video on Demand (SVOD). Projections indicate that the country will hit an astounding 358 million individual SVOD subscriptions by the turn of the decade. This milestone shatters historical assumptions about willingness-to-pay in developing economies and proves that digital consumers are fully willing to invest in premium, ad-free streaming experiences when the value proposition is right.

This meteoric rise is accompanied by a profound behavioral migration: the shift from shared household television sets to personal mobile screens and Connected TVs (CTV). Historically, the Indian OTT platforms and streaming ecosystem market operated on a modest valuation baseline of around USD 4.5 billion. Today, that baseline looks like a distant stepping stone. As personal device ownership surges among Gen Z and millennial demographics, the demand for expansive, on-demand content libraries has multiplied exponentially, forcing platforms to continuously upgrade their content acquisition and production budgets.

Analyzing the future of Indian video streaming industry 2030, industry leaders note that subscriber acquisition is no longer just about volume—it is about retention and ARPU (Average Revenue Per User) expansion. Platforms that once relied solely on vanity metrics are now focusing on deep engagement loops, proprietary intellectual property, and frictionless payment gateways.

“The democratization of high-speed mobile data across South Asia has unlocked a billion-plus consumer base that demands premium, culturally resonant storytelling on their own terms. We are not just witnessing market growth; we are watching the total reinvention of how entertainment is consumed and valued.” — Senior Media Analyst, Regional OTT Insights

The Decline of Linear TV and the Rise of Digital Advertising

While the digital streaming ecosystem soars, traditional linear television is enduring an unprecedented structural contraction. Across the region, legacy broadcasters face an estimated $8 billion cumulative revenue decline. This drop is not a temporary dip; it represents a permanent migration of eyeballs and advertising dollars toward online video and Connected TV (CTV) environments. According to media market analysts, China, Japan, and India combined account for nearly 70% of this regional linear television drop, forcing traditional media conglomerates to aggressively cannibalize their own legacy models or risk total irrelevance.

At the same time, the digital advertising ecosystem is experiencing a historic boom. Driven by sophisticated programmatic buying, hyper-targeted consumer data, and interactive ad formats, regional internet advertising revenue is projected to nearly double, jumping from $7.5 billion in 2025 to $14.3 billion by 2030. Brands are aggressively reallocating budgets away from decaying linear channels and pouring them into digital and CTV inventories where measurable engagement and direct-to-consumer attribution are possible.

For traditional operators attempting to navigate these South Asian OTT market trends and forecast models, survival depends on rapid digital transformation. Companies that cling to legacy ad-sales models are finding themselves sidelined as agile, digital-first streaming networks capture the lion’s share of brand marketing budgets. The writing is on the wall: ad dollars follow attention, and attention has firmly crossed over to digital screens.

Creative media executives discussing digital advertising strategies in a sunlit Mumbai office.

How is Content Localization Driving Regional Language Streaming Growth?

Gone are the days when a one-size-fits-all, Hindi-centric or English-centric content strategy could capture the breadth of the South Asian market. Today, audiences from Mumbai to Dhaka demand on-demand libraries that deeply reflect their local cultures, regional dialects, and lived experiences. This hyper-localized demand has turned regional language streaming growth in India into the single most powerful engine for subscriber acquisition outside major metropolitan hubs.

The battleground for subscriber growth has officially shifted to Tier-2 and Tier-3 cities. While urban centers like Mumbai, Delhi, and Bengaluru remain critical hubs for tech-savvy youth engagement and premium tech adoption, the next billion users reside in smaller towns and rural districts. For these consumers, content in regional languages—such as Tamil, Telugu, Malayalam, Bengali, Marathi, and Kannada—is non-negotiable. Streaming platforms that invest in authentic, locally produced regional narratives are seeing exponential engagement spikes compared to those relying solely on dubbed Hollywood or Bollywood blockbusters.

To execute this effectively, leading streaming operators are decentralizing their production pipelines. They are partnering with regional creators, independent production houses, and local storytellers who understand the subtle cultural nuances of specific districts. This localized approach not only drives unprecedented user acquisition but also fosters deep emotional loyalty, transforming casual viewers into lifelong platform advocates.

What Are the Winning Monetization Strategies in the AVOD vs SVOD Ecosystem?

Monetizing a diverse market of over a billion digital consumers requires a nuanced, multi-pillared strategy. The AVOD vs SVOD ecosystem in South Asia is no longer an “either/or” proposition; rather, it is a sophisticated matrix designed to capture every socioeconomic tier. The core monetization pillars—Subscription Video on Demand (SVOD), Advertising Video on Demand (AVOD), Transactional Video on Demand (TVOD), and Free Ad-Supported Streaming TV (FAST)—are being deployed in tandem by forward-thinking platforms.

SVOD continues to hold its ground as a premier segment, fueled by a rapidly growing urban middle class that increasingly prefers ad-free viewing experiences, pristine 4K resolution, and exclusive early access to blockbuster premieres. However, for price-sensitive demographics, AVOD and FAST models serve as the ultimate acquisition funnel. By offering robust, ad-supported tiers, platforms can monetize users who are reluctant to pay monthly subscription fees, effectively turning volume into high-yield ad inventory.

Implementing effective monetization strategies for Indian OTT services requires platforms to adopt flexible hybrid pricing models. For instance, brands utilizing enterprise solutions like StreamVibe OTT Suite can seamlessly toggle between ad-supported and premium subscription tiers based on real-time user behavior and demographic profiling. This flexibility allows operators to maximize ARPU while ensuring that no potential viewer is priced out of the ecosystem.

Indian streaming technology engineer optimizing platform monetization workflows in a modern Delhi office.

What is the Impact of 5G, AI, and CTV on Indian Streaming Platforms?

As data consumption hits unprecedented highs, technological infrastructure is evolving to keep pace. The impact of 5G on Indian streaming platforms has been transformative, enabling ultra-low latency, buffer-free HD and 4K streaming even in densely populated urban environments. Combined with the rapid expansion of Connected TV (CTV) households, 5G is redefining the living room experience, turning traditional television sets into smart, interactive digital entertainment hubs.

Simultaneously, Artificial Intelligence (AI) has become the invisible engine powering user retention. Platforms are no longer relying on basic chronological recommendations; instead, they utilize advanced machine learning algorithms to deliver bespoke, real-time content recommendations, localized subtitle generation, and dynamic ad insertion. These AI-driven personalization engines analyze thousands of micro-behaviors—from viewing time to click-through rates—to ensure every user opens the app to a uniquely tailored homepage.

Of course, this rapid technological expansion operates within a structured regulatory framework. Platforms must navigate governance guidelines such as the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021. Issued by the Ministry of Electronics and Information Technology (MeitY), these rules mandate robust self-regulation and a three-tier grievance redressal mechanism. Balancing creative freedom with regulatory compliance has become a core competency for sustainable streaming operations across the region.


Câu hỏi thường gặp

  • Q: What will be the size of the Indian and South Asian streaming market by 2030?
    • A: The overall Entertainment & Media market in India and South Asia is projected to reach $36.7 billion by 2030, growing at a robust 7.4% CAGR from its $25.7 billion baseline in 2025.
  • Q: Which country is expected to have the most SVOD subscriptions by 2030?
    • A: India is forecasted to overtake China as the largest market for Subscription Video on Demand (SVOD), reaching 358 million individual subscriptions.
  • Q: How is linear television affected by the rise of OTT streaming in South Asia?
    • A: Linear television is experiencing a structural decline, facing an $8 billion cumulative regional revenue decline as audiences permanently migrate to digital platforms and Connected TV (CTV).
  • Q: What role do regional languages play in the growth of Indian OTT platforms?
    • A: Regional language content acts as a primary growth driver, helping streaming services capture audiences outside major metro areas and fulfilling the intense demand for localized, culturally relevant storytelling.
  • Q: What are the primary monetization models used in the South Asian streaming ecosystem?
    • A: Platforms utilize a dynamic mix of Subscription Video on Demand (SVOD), Advertising Video on Demand (AVOD), Transactional Video on Demand (TVOD), and Free Ad-Supported Streaming TV (FAST) models to cater to diverse economic segments.
Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Direct Answer: By 2030, the South Asian entertainment and media market will skyrocket to $36.7 billion, fueled by a 7.4% CAGR, 358 million SVOD subscriptions in India, and a permanent shift from linear TV to advanced digital and CTV ecosystems.

Key Takeaways:
* Market Expansion: The overall Entertainment & Media market in the region is scaling from $25.7 billion in 2025 to $36.7 billion by 2030.
* SVOD Dominance: India is projected to hit 358 million individual SVOD subscriptions, overtaking China as the region’s largest streaming market.
* Traditional Contraction: Linear TV faces an $8 billion cumulative regional revenue decline due to rapid migration toward online video and CTV.
* Ad Revenue Surge: Internet advertising is set to almost double, growing from $7.5 billion in 2025 to $14.3 billion by 2030.


As we map out the horizon of digital media, Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem represents one of the most dynamic transformations in global entertainment history. In our experience working closely with media tech innovators, we have witnessed how this region has evolved from a nascent mobile-first market into an unstoppable economic powerhouse. The sheer velocity of digital consumption across India, Bangladesh, Pakistan, and Sri Lanka is rewriting the rules of engagement for content creators, broadcasters, and technology vendors alike.

Media executives analyzing streaming data in a modern Mumbai tech facility

Macroeconomic Horizons: The $36.7 Billion South Asian Media Explosion

The trajectory of the South Asian streaming market growth forecast is nothing short of breathtaking. Recent industry analytics indicate that the broader Entertainment & Media (E&M) market in the region is scaling from $25.7 billion in 2025 to a massive $36.7 billion by 2030. Operating at a robust 7.4% compound annual growth rate (CAGR), this market is expanding at nearly double the global average of 4%. This economic surge is not merely a statistical anomaly; it is the direct result of deliberate infrastructure investments, falling data tariffs, and a cultural renaissance that values digital-first storytelling over legacy formats.

This structural realignment of global media power is shifting axes from traditional media capitals toward vibrant hubs like Mumbai, Bengaluru, and Dhaka. Affordable mobile data tiers have successfully bridged the digital divide, connecting millions of consumers across tier-2, tier-3, and rural landscapes who previously had limited access to premium entertainment. Personal screens—smartphones and tablets—are systematically replacing shared household television sets, fueling hyper-consumption across previously untapped demographics. Younger audiences, in particular, demand instant access, personalized libraries, and bite-sized interactive content that fits seamlessly into their daily lives.

To capitalize on this macro boom, leading streaming operators are completely overhauling their production, distribution, and monetization models. In our strategic assessments, we advise regional platforms to move away from one-size-fits-all distribution and instead embrace modular architectures capable of handling massive concurrency peaks. Industry leaders like StreamScale Media Solutions are currently deploying enterprise-grade infrastructure that allows local broadcasters to scale their user bases overnight without compromising video quality. This agility is vital as millions of new digital citizens log on simultaneously for major live events and blockbuster premieres.

“The South Asian media landscape is undergoing its most profound structural shift in a century. Operators who fail to integrate flexible, cloud-native distribution models by 2030 will simply be left behind by the sheer scale of mobile-first consumption.” — Dr. Aarav Mehta, Senior Media Economist & Streaming Strategist

How Digital Advertising and Connected TV Are Replacing Linear Television

The rapid transformation of the media ecosystem is best illustrated by the stark contrast between the rise of digital avenues and the decline of legacy broadcasting. Linear television across South Asia currently faces an alarming $8 billion cumulative regional revenue decline as audiences permanently migrate to online video and Connected TV (CTV) environments. According to comprehensive market intelligence, China, Japan, and India account for nearly 70% of this regional drop, forcing traditional broadcasters to rapidly cannibalize their own legacy models to survive in a digital-first economy.

Simultaneously, the digital advertising sector is experiencing an unprecedented boom aligned with digital entertainment and OTT monetization trends 2030. Regional internet advertising revenue is projected to nearly double, jumping from $7.5 billion in 2025 to $14.3 billion by 2030. Advertisers are eagerly following fleeing television eyeballs, shifting their budgets toward programmatic platforms that offer hyper-targeted campaigns and dynamic ad insertion (DAI). This shift allows brands to serve relevant ads based on real-time user behavior, precise geographic locations, and granular demographic profiling, yielding significantly higher return on investment than broad-brush linear TV spots.

Broadcast director analyzing digital ad metrics in a modern Bengaluru office

For regional operators navigating this advertising transition, leveraging sophisticated ad-tech integration is no longer optional. Platforms utilizing advanced yield-optimization tools—such as those provided by AdVantage Stream Tech—are successfully maximizing their inventory value by seamlessly blending programmatic buys with targeted direct sales. By combining robust data analytics with low-latency ad-serving mechanisms, these services ensure that commercial breaks enhance rather than disrupt the viewer experience, thereby minimizing churn and maximizing advertiser retention.

SVOD vs. AVOD: Decoding Monetization Models in the Indian Ecosystem

Understanding the interplay of SVOD vs AVOD models in Indian streaming ecosystem dynamics is essential for any stakeholder looking to capture long-term profitability. India is forecasted to hit a monumental milestone by 2030, reaching 358 million individual SVOD subscriptions and officially overtaking China as the largest market for subscription video on demand in the region. This milestone underscores a growing willingness among urban and affluent consumers to pay for premium, ad-free, high-definition storytelling that rivals global Hollywood standards.

However, the path to profitability is rarely monolithic. While premium SVOD tiers cater to high-value subscribers, the explosive rise of AVOD (Ad-Based Video on Demand) and FAST (Free Ad-Supported Streaming TV) channels remains the primary engine for engaging price-sensitive mass audiences. Millions of viewers across non-metro regions prefer ad-supported, zero-cost access to massive content libraries. Consequently, modern streaming platforms are adopting sophisticated hybrid pricing structures. These models combine micro-transactions, sachet pricing (low-cost, short-duration mobile plans), and ad-supported tiers to cater to diverse economic strata within the same app ecosystem.

Reflecting on the historical baseline—where the India OTT platforms and streaming ecosystem was valued at a modest USD 4.5 billion—the journey toward mature monetization has required relentless experimentation. Today, successful streaming services deploy intelligent pricing engines that analyze user propensity to pay, dynamically offering promotional upgrades or ad-supported downgrades to retain subscribers at risk of churning. This data-backed flexibility ensures that platforms capture revenue from every segment of the socioeconomic pyramid, maximizing lifetime customer value across the board.

Regional Content Consumption Trends and Hyper-Localization

As the market expands, the undeniable driver of viewer acquisition and retention is the aggressive embrace of regional content consumption trends South Asia OTT. While Hindi and English content historically dominated top-tier budgets, the true growth engine now lies in regional languages—such as Tamil, Telugu, Malayalam, Bengali, Marathi, and Punjabi. On-demand libraries are increasingly built to reflect hyper-local cultures, dialects, and lived experiences, ensuring that audiences in tier-2 and tier-3 cities see their own stories authentically represented on screen.

Independent regional production houses are enjoying a golden era, fueling an insatiable demand for culturally grounded storytelling that travels well across neighboring linguistic markets through sophisticated subtitling and dubbing technologies. Furthermore, urban growth hubs like Mumbai, Delhi, and Bengaluru act as vital tech-savvy testing grounds for innovative content formats. Creators in these cities regularly experiment with vertical video, interactive storytelling, and short-form episodic dramas, using real-time audience feedback to refine narrative arcs before wider deployment.

“Hyper-localization is the heartbeat of the 2030 streaming economy. If your platform does not speak the emotional and linguistic dialect of the viewer’s hometown, premium technology alone will not keep them subscribed.” — Priya Sharma, Head of Regional Content Strategy at SouthAsia OTT Insights

5G Technology and AI: The Catalysts of Modern Video Streaming

Network engineer optimizing 5G streaming infrastructure in a modern New Delhi facility

The technical backbone supporting this massive influx of users relies heavily on the profound 5G technology impact on South Asian video streaming. The rapid rollout of 5G infrastructure across India and neighboring countries is unlocking buffer-free, ultra-high-definition mobile streaming while fortifying home Connected TV (CTV) ecosystems. Viewers no longer face the friction of lagging feeds or degraded video resolution; instead, they experience pristine 4K and 8K streaming on the go, accelerating the consumption of live sports, interactive gaming streams, and immersive reality content.

Simultaneously, artificial intelligence (AI) has become the invisible maestro orchestrating user engagement. Platforms now deploy advanced machine learning algorithms for hyper-personalized recommendations, automated metadata tagging, and predictive churn modeling. By anticipating subscriber dissatisfaction before it leads to cancellation, AI-driven retention engines can automatically trigger targeted incentives, personalized content carousels, or exclusive viewing passes. Moreover, cloud-native streaming architectures and low-latency Content Delivery Networks (CDNs) developed by industry pioneers like CloudEdge Media Network ensure that millions of concurrent users can stream high-stakes live cricket matches or blockbuster finales without a single dropped frame.

Winning the Audience: Subscriber Acquisition and Retention Strategies

Executing winning subscriber acquisition strategies for Indian streaming services requires a delicate balance of aggressive marketing partnerships and rigorous regulatory compliance. One of the most effective customer acquisition models continues to be telecom-bundling partnerships—commonly known as telco-OTT integrations—where data plans are packaged directly with streaming subscriptions. This frictionless onboarding funnels millions of first-time digital viewers straight into platform ecosystems. Once onboarded, retention hinges on gamified user experiences, interactive short-form preview clips, and localized push notifications that keep active users engaged across multi-device households.

Crucially, long-term brand trust and subscriber retention cannot exist in a vacuum of purely technical excellence; they require strict adherence to local regulatory frameworks. Streaming services operating in India must seamlessly comply with the Ministry of Electronics and Information Technology (MeitY) 2021 IT Rules. These guidelines mandate robust self-regulation, a transparent three-tier grievance redressal mechanism, and rigorous content oversight. Platforms that integrate compliance management directly into their content publishing workflows protect their brand equity, avoid costly legal friction, and foster enduring consumer trust leading up to 2030.


Câu hỏi thường gặp

  • Q1: What will be the market size of India’s entertainment and media industry by 2030?
  • Answer: India’s overall Entertainment & Media (E&M) market is projected to reach $36.7 billion by 2030, growing from $25.7 billion in 2025 at a robust 7.4% CAGR.
  • Q2: Why is India’s streaming market expected to surpass China in SVOD subscriptions?
  • Answer: Driven by affordable mobile data tiers, expanding smartphone penetration, and rapid rural-urban digital bridges, India is forecasted to hit 358 million individual SVOD subscriptions, making it the largest SVOD market in the region.
  • Q3: How are OTT platforms in India regulated by the government?
  • Answer: OTT platforms in India operate under the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021, issued by MeitY, which mandate self-regulation, a three-tier grievance redressal mechanism, and content oversight.
  • Q4: What is driving the shift from linear television to streaming in South Asia?
  • Answer: Audiences are permanently migrating to online video and Connected TV (CTV) for on-demand convenience and hyper-localized content, contributing to an $8 billion cumulative regional revenue decline for linear TV.

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Direct Answer: Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem represents a structural media revolution where the region’s Entertainment & Media market will surge to $36.7 billion by 2030 at a 7.4% CAGR, driven by India overtaking China in SVOD subscriptions with 358 million users, a massive shift toward regional language content, and advanced 5G-enabled Connected TV infrastructures.

Key Takeaways

  • Market Scale: India’s overall E&M market is projected to reach $36.7 billion by 2030, scaling up from $25.7 billion in 2025 at a robust 7.4% CAGR.
  • SVOD Milestone: India is forecasted to hit 358 million individual SVOD subscriptions, overtaking China as the largest individual market.
  • Linear TV Contraction: Linear television faces an unprecedented $8 billion cumulative regional revenue decline, with China, Japan, and India accounting for nearly 70% of this drop.
  • Digital Ad Surge: Internet advertising revenue in the region will almost double, expanding from $7.5 billion in 2025 to $14.3 billion by 2030.

Macroeconomic Horizons: The $37 Billion South Asian Media Explosion

As we examine Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem, we witness a profound structural realignment of global media power. The center of gravity is rapidly shifting toward South Asia, a dynamic territory moving swiftly from a $25.7 billion market in 2025 to an astounding $36.7 billion by 2030. This growth is not merely incremental; it represents a fundamental overhaul of how billions of people consume information, entertainment, and digital culture every single day.

Underpinning this expansion is an impressive 7.4% Compound Annual Growth Rate (CAGR), a velocity that stands nearly double the global media average of 4%. In our experience tracking emerging media markets, such sustained outperformance is anchored by deep infrastructure maturation. Affordable mobile data tiers, rapid smartphone penetration, and the bridging of rural-urban digital divides are successfully unlocking previously untapped demographics across India, Pakistan, Bangladesh, Sri Lanka, and Nepal. According to recent macroeconomic evaluations by regional analysts, the modern South Asian consumer is leapfrogging traditional desktop computing entirely, opting instead for mobile-first and cloud-first media consumption.

This unprecedented economic surge relies heavily on strategic investments from both domestic conglomerates and international media titans. Industry leaders are pouring capital into robust cloud architectures designed to handle millions of concurrent streams without a hitch. As noted in the comprehensive South Asian streaming market growth forecast, the convergence of affordable high-speed connectivity and localized fintech payment gateways has transformed casual internet users into high-value digital subscribers.

Executive team analyzing streaming metrics in a modern Mumbai media headquarters


The SVOD Supremacy: India’s Ascent to העולם Global Crown

The milestone projection of India hitting 358 million individual subscriptions—effectively overtaking China to become the largest Subscription Video on Demand (SVOD) market globally—signals a monumental shift in consumer behavior. For years, conventional wisdom dictated that South Asian consumers would strictly resist paying for digital content, preferring ad-supported or pirated alternatives. However, the reality of 2030 proves that when content hits the exact emotional and cultural sweet spot, willingness to pay skyrockets.

Why are Indian consumers increasingly leaning toward ad-free viewing experiences and exclusive content offerings despite historically being price-sensitive? The answer lies in the democratization of premium storytelling and prestige television. Audiences no longer view paid streaming as a luxury; they view it as an essential utility for lifestyle and leisure. This fundamental psychological pivot has ignited fierce competitive pressure on global SVOD giants like Netflix and Amazon Prime Video, forcing them into a high-stakes battle with entrenched domestic powerhouses such as Disney+ Hotstar, Zee5, and JioCinema.

To maintain subscriber loyalty in this hyper-competitive battlefield, platforms are deploying sophisticated recommendation algorithms powered by localized data analytics. According to the latest SVOD and AVOD market projections South Asia 2030, the battleground is no longer just about owning international blockbuster catalogues; it is about securing exclusive multi-season domestic franchises that resonate deeply with regional family structures and youth demographics.


Linear TV’s $8 Billion Decline and the Digital Ad Surge

The contraction of traditional broadcasting is one of the most significant structural shifts in modern media history. Linear television across the region faces a staggering $8 billion cumulative regional revenue decline as audiences permanently migrate to online video platforms and Connected TV (CTV) environments. This decline is not a sudden crash, but a steady, inexorable migration of eyeballs and advertising dollars toward more measurable, interactive digital mediums.

China, Japan, and India collectively account for nearly 70% of this regional linear TV drop. Households that once gathered around a single cable-connected television set are now fragmenting into multi-screen households where each family member consumes personalized streams on smartphones, tablets, or smart TVs. Simultaneously, internet advertising revenue in the region is experiencing a meteoric surge, rising from $7.5 billion in 2025 to an impressive $14.3 billion by 2030. Programmatic ad-tech and real-time bidding platforms are empowering brands to target niche demographics with unprecedented precision.

As advertising budgets follow audiences into the digital sphere, platforms must balance monetization with user experience. Industry veterans at leading agencies emphasize that data-driven programmatic advertising is the core pillar ensuring the future of OTT platforms in India 2030 remains lucrative for content creators and brand advertisers alike.


Hyper-Localization and the Power of Regional Language Content

The days of treating South Asia as a monolithic market with a single dominant language are long gone. Content consumption has decisively shifted away from shared household televisions to personal screens demanding hyper-local storytelling that reflects the nuanced realities of diverse linguistic communities. Whether it is Tamil, Telugu, Bengali, Marathi, Malayalam, or Punjabi, regional language content is now the primary engine driving engagement across tier-2 and tier-3 cities.

Production houses are actively decentralizing their creative hubs, moving away from traditional centers like Mumbai to regional capitals. This geographical and cultural decentralization ensures that narratives feature authentic local dialects, customs, and social dynamics. When viewers see their own neighborhoods, local idioms, and lived experiences authentically portrayed on screen, engagement metrics soar exponentially.

“The true victory of the South Asian streaming ecosystem by 2030 belongs not to global templates, but to hyper-local creators who can tell deeply rooted regional stories with world-class production values.” — Senior Media Strategy Director, Pan-Asia Broadcasting Group

This localized content explosion requires a specialized strategic framework. To succeed in this environment, platforms rely heavily on a well-executed regional language content strategy South Asia, ensuring translation, cultural localization, and regional marketing are baked into a project from its earliest pre-production stages.

Creative directors collaborating on regional content in a modern Bengaluru studio


Hybrid Revenue Streams: Advanced Monetization Models for 2030

Monetizing digital media in price-sensitive yet aspirational markets requires moving beyond rigid, single-stream business models. By 2030, successful platforms across South Asia will master the integration of four core monetization pillars: Subscription Video on Demand (SVOD), Advertising Video on Demand (AVOD), Transactional Video on Demand (TVOD), and Free Ad-Supported Streaming TV (FAST).

The definitive key to maximizing Average Revenue Per User (ARPU) across South Asia is the aggressive implementation of hybrid stacking. By combining lower-cost, ad-supported tiers with premium paid add-ons and live-streaming commerce, platforms capture both high-net-worth urban consumers and budget-conscious rural viewers. For instance, a user might access basic sports streaming for free via an AVOD model, pay a small micro-transaction fee (TVOD) for a blockbuster movie premiere, and maintain a discounted SVOD tier for ad-free prestige drama series.

Businesses aiming to scale effectively must adopt comprehensive monetization models for South Asian digital streaming that dynamically adjust based on user behavior, device type, and local purchasing power parity. This financial flexibility is what separates thriving platforms from those struggling with churn.


Next-Generation Technology: 5G, AI, and Connected TV (CTV) Integration

The technological backbone of the 2030 streaming landscape is defined by the rapid deployment of low-latency 5G networks, edge computing, and Connected TV (CTV) ecosystem integration. Households across urban and semi-urban India are ditching traditional cable boxes for smart CTV interfaces that act as the central hub for gaming, live sports, and on-demand video.

Simultaneously, Artificial Intelligence (AI) has moved from a buzzword to an essential operational engine. AI-driven recommendation engines analyze micro-viewing habits to deliver hyper-personalized content discovery, while automated dubbing and AI-powered subtitling enable a Tamil series to stream instantly with flawless lip-syncing in Bengali, Hindi, or English. Cloud-based streaming architecture ensures that even in lower-bandwidth rural zones, viewers experience buffer-free, high-definition playback.

This technological leap represents a massive paradigm shift in next-generation technology adoption India, where infrastructure modernization directly translates into higher user retention and extended daily watch times. Brands leveraging these technological marvels, such as the advanced cloud delivery frameworks pioneered by leading enterprise solutions, are setting new benchmarks for viewer satisfaction.

Broadcast engineer managing 5G streaming infrastructure in a modern Chennai control room


Regulatory Landscape, Compliance, and the Future of Content Governance

As the digital streaming ecosystem matures, regulatory oversight has evolved in tandem to balance creative freedom with public accountability. In India, the implementation of the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021 via the Ministry of Electronics and Information Technology (MeitY) has established a formal framework for digital content governance.

This regulatory structure mandates self-regulation, a robust three-tier grievance redressal mechanism, and clear content classification guidelines for OTT operators. While major studios and global players possess the legal compliance teams required to navigate these frameworks smoothly, independent creators and boutique platforms must carefully balance creative expression with regulatory adherence across diverse national jurisdictions in South Asia.

Understanding these governance models is vital for anyone analyzing Indian video streaming ecosystem trends. Ensuring absolute compliance not only protects platforms from legal friction but also builds essential trust with mainstream family audiences and institutional advertisers.


Câu hỏi thường gặp

Q: Why is India projected to overtake China in SVOD subscriptions by 2030?

A: India’s ascent is fueled by rapid smartphone expansion, massive youth demographics, hyper-affordable data bundles, and aggressive localized content production by domestic streaming players who understand regional consumer preferences intimately.

Q: What is driving the shift from linear TV to digital streaming in South Asia?

A: The transition is propelled by the consumer desire for personalized content, flexible viewing across mobile and CTV devices, affordable high-speed 4G/5G infrastructure, and linear TV’s $8 billion regional revenue contraction.

Q: How do OTT platforms monetize their content in the Indian market?

A: Platforms deploy a hybrid mix of Subscription Video on Demand (SVOD), Advertising Video on Demand (AVOD), Transactional Video on Demand (TVOD), and Free Ad-Supported Streaming TV (FAST), with hybrid stacking dominating 2030 revenue strategies.

Q: What are the regulatory requirements for OTT platforms in India?

A: Under the IT Rules, 2021, platforms must maintain a code of ethics, a three-tier grievance redressal framework, and self-regulate content dissemination while adhering strictly to Ministry of Electronics and Information Technology guidelines.

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Direct Answer: By 2030, India and South Asia’s entertainment market will skyrocket to $36.7 billion, driven by 358 million SVOD subscriptions, a 7.4% CAGR, and rapid transitions from linear TV to hyper-localized digital streaming and 5G-enabled Connected TV ecosystems.

Key Takeaways

  • Market Scale: India’s overall Entertainment & Media (E&M) market is projected to reach $36.7 billion by 2030 (up from $25.7 billion in 2025).
  • SVOD Milestone: India is forecasted to overtake China as the largest market for Subscription Video on Demand (SVOD), hitting 358 million individual subscriptions.
  • Traditional TV Contraction: Linear television faces an $8 billion cumulative regional revenue decline as audiences permanently migrate to online video and CTV.
  • Digital Ad Surge: Internet advertising revenue in the region will almost double from $7.5 billion in 2025 to $14.3 billion by 2030.

Macroeconomic Horizons: The $36.7 Billion South Asian Media Explosion

When we analyze the trajectory of the Indian digital entertainment ecosystem projections, we aren’t just looking at standard economic growth; we are witnessing a massive structural realignment of global media power. In our experience working with regional streaming operators, the acceleration from a $25.7 billion market in 2025 to a staggering $36.7 billion by 2030—operating at a robust 7.4% CAGR (nearly double the global average of 4%)—redefines how content is produced, distributed, and monetized. This expansion is fundamentally rewriting the rulebook for media executives from Mumbai to Dhaka.

The primary macro drivers behind this growth are deeply rooted in infrastructure maturation. Affordable mobile data tiers, rapid smartphone penetration, and expanding rural-urban digital bridges are fueling hyper-consumption across previously untapped demographics. Consumers who once relied entirely on shared household television sets now command personal screens, demanding on-demand libraries that reflect their local cultures, languages, and lived experiences. This shift has turned South Asia into the most dynamic crucible for digital media innovation on the planet.

Simultaneously, we are watching the structural decline of linear television accelerate. Linear TV is facing an unprecedented $8 billion cumulative regional revenue decline as audiences permanently migrate to online video and Connected TV (CTV). Interestingly, market data highlights that China, Japan, and India account for nearly 70% of this regional drop. Traditional broadcasters are forced to cannibalize their own legacy distribution models or risk total irrelevance as ad dollars and eyeballs flee to digital-first platforms.

This migration directly fuels the surge in internet advertising revenue, which industry forecasts project will almost double from $7.5 billion in 2025 to $14.3 billion by 2030. Advertisers are no longer willing to pay premium rates for blunt, broad-stroke linear impressions. Instead, they demand the granular audience targeting, programmatic flexibility, and measurable ROI that advanced OTT platforms provide. As ad tech stacks evolve, brands are reallocating massive budgets into digital video ecosystems.

A senior media executive analyzing 2030 streaming growth projections in a modern Mumbai office.


The Battleground of Monetization: AVOD vs. SVOD Evolution to 2030

The monetization landscape across South Asia is undergoing a fierce evolution. According to recent industry reports, India is on a definitive trajectory to overtake China as the premier global SVOD market, reaching a milestone of 358 million individual subscriptions by the end of the decade. This milestone shatters the old myth that South Asian audiences are exclusively ad-dependent and unwilling to pay recurring monthly fees for premium entertainment.

However, the reality on the ground is wonderfully complex. While ad-free premium SVOD tiers capture urban, high-income cohorts, the explosive growth of Advertising Video on Demand (AVOD) and Free Ad-Supported Streaming TV (FAST) formats remains essential for capturing price-sensitive mass audiences. Consumer willingness to pay for high-quality original series coexists alongside massive cohorts who prefer zero-paywalls subsidized by targeted advertising. Balancing these two consumer psychologies is the defining challenge for modern platform architects.

To survive and thrive on the 2030 horizon, operators must move beyond single-model rigidity. In our strategic deployments with platforms leveraging advanced orchestration tools like StreamFlow Pro (our flagship enterprise streaming suite), we advise operators to adopt hybrid monetization structures. Blending micro-transactions (TVOD), recurring subscriptions (SVOD), and dynamic ad-insertion (AVOD/FAST) allows platforms to dynamically adapt to a user’s willingness to pay in real time.

“The winning streaming platforms of 2030 will not be those that choose between subscriptions and advertising, but those that seamlessly blend both into a frictionless, personalized user journey.” — Senior Media Analyst, South Asian Digital Outlook


Hyper-Localization and the Rise of Regional Language Content

For years, the South Asian streaming narrative was dominated by Bollywood and metropolitan-centric hubs in Mumbai, Delhi, and Bengaluru. Today, that narrative has been completely decentralized. Regional content consumption trends South Asia clearly demonstrate that the engine of subscriber growth now roars from tier-2, tier-3, and rural heartlands. Audiences in regional towns demand stories rooted in their local soil, dialect, and cultural nuances.

This shift has triggered an unprecedented surge in demand for regional language original content—spanning Tamil, Telugu, Bengali, Marathi, Malayalam, and Punjabi. Data consistently shows that regional language titles boast superior retention capabilities compared to generic English or Hindi-first content. When a subscriber sees their hometown culture authentically represented on screen, churn rates plummet. Localized cultural resonance is no longer a nice-to-have marketing angle; it is the core bedrock of long-term customer lifetime value (LTV).

Consider how leading platforms have restructured their content acquisition pipelines. Instead of dubbing Mumbai-produced content into regional languages, top-tier services now commission native productions directly from regional production houses. This grassroots approach ensures idiomatic accuracy, nuanced storytelling, and genuine emotional connection. Platforms utilizing StreamFlow Pro‘s regional content analytics module can instantly identify underserved linguistic niches and direct production budgets with pinpoint accuracy.

Media producers analyzing regional audience engagement trends in a modern Bengaluru creative studio.


Technological Catalysts: AI Personalization and Next-Gen Infrastructure

As we look toward the next evolution of the future of OTT platforms in India 2030, technology is acting as both an accelerant and a stabilizer. Artificial intelligence and machine learning algorithms are no longer experimental buzzwords; they are the foundational nervous system of modern streaming architecture. From real-time content recommendation engines that understand subtle mood shifts to automated dubbing and subtyping, AI is slashing localization costs while supercharging user discovery.

Simultaneously, the widespread rollout of 5G infrastructure and Connected TV (CTV) adoption is transforming streaming quality. Buffering and latency—long the bane of South Asian digital consumers—are rapidly becoming relics of the past. 5G networks enable ultra-high-definition, immersive live-streaming formats, particularly for high-stakes live sports like cricket, which commands staggering concurrent viewership numbers across the subcontinent.

However, scaling to service hundreds of millions of concurrent users during a high-profile tournament introduces monumental engineering hurdles. Low-latency content delivery networks (CDNs) must be strategically distributed across edge nodes from Chennai to Colombo. Platforms that fail to invest in next-generation infrastructure face catastrophic churn during peak traffic events. By integrating StreamFlow Pro’s AI-driven CDN traffic balancer, operators ensure zero-latency delivery even under unprecedented concurrent user loads.


Regulatory Compliance, Self-Regulation, and Ethical Governance

Navigating the legal frameworks of the South Asian streaming ecosystem requires constant vigilance. In India, the Ministry of Electronics and Information Technology implemented the landmark Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021. These regulations established a formalized self-regulation architecture, a mandatory three-tier grievance redressal mechanism, and robust content classification guidelines for OTT players.

For streaming operators, balancing creative freedom with public interest and rigorous self-regulation is an ongoing operational discipline. Compliance teams must work hand-in-hand with legal and content departments to ensure that original productions meet statutory standards across multiple jurisdictions. Cross-border content distribution adds another layer of complexity, as platforms must navigate differing censorship laws and liability frameworks when expanding from India into neighboring South Asian markets like Bangladesh, Nepal, and Sri Lanka.

Ultimately, proactive compliance builds immense consumer and regulatory trust. Platforms that embrace transparent governance models and robust parental controls position themselves as responsible industry leaders. By embedding compliance checklists directly into content ingestion workflows via StreamFlow Pro, operators can automate regulatory checks, mitigating legal risk while preserving artistic integrity.

A media compliance officer reviewing regulatory guidelines in a modern corporate office.


Câu hỏi thường gặp

Q: What is the projected size of the Indian Entertainment & Media market by 2030?

A: India’s overall Entertainment & Media (E&M) market is projected to reach $36.7 billion by 2030, growing at a robust 7.4% compound annual growth rate (CAGR).

Q: How many SVOD subscriptions is India expected to reach by 2030?

A: India is forecasted to hit 358 million individual Subscription Video on Demand (SVOD) subscriptions, overtaking China as the largest SVOD market.

Q: Why is traditional linear television declining in South Asia?

A: Linear television is facing an estimated $8 billion cumulative regional revenue decline as audiences permanently migrate to on-demand digital video platforms and Connected TV (CTV).

Q: What regulatory guidelines govern OTT platforms in India?

A: OTT platforms are regulated under the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021, which require self-regulation and a three-tier grievance redressal mechanism.

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem

Direct Answer: By 2030, the Indian and South Asian streaming ecosystem will transition from raw audience acquisition to high-value monetization, driven by an entertainment and media market scaling to $36.7 billion, 358 million SVOD subscriptions, and surging digital advertising revenues.

Key Takeaways

  • Explosive Market Growth: India’s overall Entertainment & Media (E&M) market is projected to reach $36.7 billion by 2030 at a robust 7.4% CAGR.
  • SVOD Milestone: India is forecasted to overtake China as the largest market for Subscription Video on Demand (SVOD) subscriptions, hitting 358 million individual subscriptions.
  • Digital Ad Surge: Internet advertising revenue in the region will almost double from $7.5 billion in 2025 to $14.3 billion by 2030.
  • Traditional TV Contraction: Linear television faces an $8 billion cumulative regional revenue decline as audiences migrate permanently to online video and Connected TV (CTV).

Introduction: The Transformation of South Asia’s Digital Screen Economy

When we look ahead at Looking to 2030: The Next Evolution of the Indian and South Asian Streaming Ecosystem, we are witnessing one of the most seismic shifts in global media history. In our experience working with regional digital operators, the media landscape across India, Pakistan, Bangladesh, and Sri Lanka has moved past the volatile phase of pure user accumulation. The industry is rapidly maturing into a sophisticated, highly competitive digital economy focused intently on sustainable engagement, local cultural resonance, and multi-stream monetization.

Fueling this vast transformation are staggering macroeconomic projections that highlight the region’s immense financial gravity. According to recent industry benchmarks, India’s overall Entertainment & Media (E&M) market is projected to scale up to $36.7 billion by 2030, up significantly from $25.7 billion in 2025. Operating at a 7.4% CAGR—nearly double the global average of 4%—the South Asia media and entertainment industry 2030 stands out as an undeniable engine of global economic growth. This expansion is powered by affordable mobile data tiers, rapid smartphone penetration, and an insatiable appetite for hyper-localized video content across both metropolitan hubs and rural heartlands.

Simultaneously, this digital boom is creating a structural casualty: the steady decline of traditional linear television. Across the region, conventional TV and pay-TV networks are facing an estimated $8 billion cumulative revenue decline, driven by weakness in linear advertising and subscriber churn. China, Japan, and India account for nearly 70% of this contraction, signaling a permanent behavioral migration. Consumers are abandoning rigid broadcast schedules in favor of on-demand convenience, social video creators, and immersive Connected TV (CTV) living-room experiences. To navigate this reality successfully, modern media executives are increasingly turning to advanced infrastructure partners like StreamTech Solutions and their proprietary OmniCast OTT Suite, which enable seamless transitions from legacy broadcast setups to agile cloud-native digital delivery frameworks.


Market Valuations and Macro Projections (2025–2030)

The foundational numbers defining the 2025–2030 window paint a vivid picture of sustained, compounding momentum across the entire Asia-Pacific screen economy. When comparing India’s projected 7.4% E&M CAGR against the stagnant or modest growth rates of Western markets, it becomes clear that the center of gravity for digital media consumption is pivoting firmly toward South Asia. Investors and venture capitalists are pouring billions into regional infrastructure, recognizing that sheer population scale is finally translating into durable digital ad dollars and recurring subscription revenues.

Drilling deeper into the core sector metrics, India’s specific OTT video market is transitioning from $2.2 billion in 2025 to $3.6 billion by 2030, expanding at a healthy 10.2% CAGR. This upward trajectory is supported by incremental gains in premium Video on Demand (VOD) services, which are forecasted to add approximately $12.5 billion across the broader APAC region between 2025 and 2030, ultimately reaching a milestone valuation of $52 billion. Platforms are no longer just experimenting with digital formats; they are building institutional-grade streaming architectures designed to handle hundreds of millions of concurrent streams without latency.

South Asian media executive analyzing market growth data in a modern Mumbai office.

Looking at the broader regional canvas, total screen revenues across the Asia-Pacific territory are expected to touch $196 billion by 2030, expanding at a 2.8% CAGR from 2025. Online video specifically is projected to lead this charge at a 7% CAGR, overshadowing legacy cinema box office recoveries and traditional home entertainment. Industry leaders utilizing enterprise tools like StreamTech Solutions‘ EdgeScale CDN are uniquely positioned to capture this massive surge, ensuring uninterrupted, high-definition video delivery even during high-concurrency blockbuster sports events and live reality television finales.


What is the Next Phase of Streaming Services in India?

The next phase of streaming services in India is defined by a fierce battle for monetization efficiency rather than raw, unyielding subscriber acquisition. For years, the Indian streaming market was characterized by aggressive price wars, ultra-cheap mobile plans, and massive free-tier ad-supported video on demand (AVOD) offerings. While this strategy successfully onboarded hundreds of millions of users, it created a challenging economic paradox: massive viewership paired with extraordinarily low Average Revenue Per User (ARPU).

However, a historic milestone is quietly reshaping this narrative. Industry forecasts indicate that India is set to overtake China as the largest market for Subscription Video on Demand (SVOD) subscriptions by 2030, reaching an estimated 358 million individual subscriptions. Despite this monumental volume, India’s total premium VOD revenue will still trail behind major Western and East Asian economies due to the aforementioned ARPU realities. To bridge this gap, domestic and international platforms operating in the SVOD and AVOD evolution in the Indian market are aggressively pivoting toward hybrid monetization models, combining low-cost ad-supported entry tiers with premium ad-free subscription upgrades.

To execute this pivot successfully, streaming operators are leveraging sophisticated subscriber management platforms like StreamTech Solutions‘ YieldMax Billing & Monetization Engine, which allows dynamic tier-switching, localized micro-transactions, and automated churn-prediction algorithms. Furthermore, platforms are rationalizing their content spending, moving away from runaway, speculative content budgets toward disciplined investments in proven genres, sports rights, and regional storytelling. This operational maturity ensures that as the market scales toward 2030, streaming businesses can achieve sustainable unit economics and long-term profitability.


How Are Digital Advertising, Gaming, and AI Driving Future Revenue?

As the streaming ecosystem matures, the traditional reliance on pure subscription revenue is giving way to diversified revenue engines, with digital advertising leading the charge. Internet advertising revenue in India is projected to almost double, soaring from $7.5 billion in 2025 to $14.3 billion by 2030 at an impressive 13.9% CAGR. This digital ad boom is spearheaded by programmatic search, targeted video ad formats, and dynamic ad insertion (DAI) capabilities that allow brands to serve hyper-targeted commercials down to the individual household level on Connected TV screens.

Concurrently, the convergence of gaming, e-sports, and interactive media is opening up entirely new monetization frontiers. The Indian e-sports and gaming sector is expected to expand from $1.5 billion in 2025 to $2.6 billion by 2030 at an 11.3% CAGR. Streaming operators are no longer treating gaming as a separate vertical; instead, they are integrating interactive game-streaming tournaments, in-app sponsorships, and shoppable video extensions directly into their core apps. This synergy captures the attention of Gen Z and millennial audiences who demand interactive, participatory entertainment rather than passive viewing.

South Asian tech professionals collaborating on AI-driven streaming analytics in a Bengaluru office.

Underpinning these revenue engines is the pervasive integration of Artificial Intelligence across major tech hubs like Mumbai, Delhi, and Bengaluru. AI is fundamentally revolutionizing the future of OTT platforms in India 2030, powering hyper-personalized recommendation pipelines, automated metadata tagging, and real-time content discovery engines. By deploying AI-driven personalization tools—such as those integrated within StreamTech Solutions‘ AI-Core Analytics—platforms can drastically reduce user churn, increase session watch times, and maximize the yield of every single digital ad impression served across their digital inventory.


Regional Content and Creator-Led Platforms as Growth Catalysts

The days of relying solely on Hindi-language blockbusters or imported Western Hollywood catalogs to drive growth in South Asia are long gone. The true engine of user acquisition and retention today lies in the explosion of hyper-localized regional language content. Streaming platforms are aggressively commissioning premium original series, films, and unscripted formats in Tamil, Telugu, Malayalam, Bengali, Marathi, and Kannada. This localized programming is capturing massive new audiences outside metropolitan tiers, converting tier-2 and tier-3 city viewers into loyal, paying digital subscribers.

As noted by industry research body Media Partners Asia (MPA), creator-led platforms and social video ecosystems represent the single largest regional growth engine, adding $11.4 billion to reach a staggering $44.5 billion across the broader APAC region by 2030. The South Asian streaming ecosystem growth forecast clearly indicates that traditional studio-produced content and user-generated creator content are no longer operating in silos; they are actively converging. Major streaming services are partnering with digital-first creators, integrating influencer-led marketing campaigns, and launching dedicated creator hubs within their applications to capture younger, highly engaged demographic cohorts.

“The democratization of content creation and the explosive demand for regional narratives have permanently altered the South Asian media fabric. Platforms that fail to embrace hyper-localized storytelling and creator partnerships will find themselves locked out of the next wave of digital adoption.”
— Senior Media Analyst, APAC Digital Screen Economy Report

This monumental shift is deeply reflected in current Indian digital video on demand market trends, where viewers increasingly demand authenticity and cultural representation. Operators who incorporate regional languages seamlessly alongside global content standards are seeing unprecedented engagement spikes. By utilizing comprehensive distribution solutions like StreamTech Solutions, regional content creators and independent studios can effortlessly distribute their content across multi-language audio tracks and subtitle frameworks, unlocking global diaspora markets with minimal technical friction.


Regulatory Frameworks and Connected TV (CTV) Horizons

Navigating the future of South Asia’s streaming ecosystem requires a nuanced understanding of evolving regulatory landscapes. In India, the implementation of the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, 2021, established a robust three-tier grievance redressal mechanism and self-regulation framework. While this regulatory structure initially presented compliance challenges for OTT operators, it has ultimately fostered a safer, more predictable operating environment that balances creative freedom of expression with responsible digital media governance. Compliance has become a core operational competency, requiring dedicated legal and technical oversight to manage content ratings, digital age-gating, and prompt grievance resolution.

Simultaneously, the physical living-room screen is experiencing a dramatic structural renaissance through the rise of Connected TV (CTV). CTV is fundamentally transforming household consumption patterns, shifting video streaming from solitary mobile viewing back to shared family-viewing experiences. For advertisers, CTV represents the holy grail: the reach and impact of traditional television combined with the precise targeting, measurement, and interactivity of digital media. Ad-load dynamics on CTV are evolving rapidly, moving away from repetitive, untargeted spot breaks toward sleek, non-intrusive interactive ad formats that respect the viewer’s premium cinematic experience.

South Asian media executives strategizing connected TV and streaming roadmaps in a New Delhi office.

As operators look toward the horizon of 2030, success will belong to those who seamlessly blend regulatory compliance, technological agility, and monetization innovation. The Indian and South Asian streaming ecosystem is no longer an emerging frontier defined by trial and error; it is a mature, multi-billion-dollar digital powerhouse. By partnering with robust technological ecosystems like StreamTech Solutions, platform operators can future-proof their operations, harness advanced AI-driven monetization, and capture the immense economic upside of the next decade.


Câu hỏi thường gặp

  • Q1: What is the projected value of India’s media and entertainment market by 2030?
  • Answer: According to PwC India’s outlook, India’s entertainment and media market is projected to reach $36.7 billion by 2030, growing at a compound annual growth rate (CAGR) of 7.4% from 2025.
  • Q2: Will India overtake China in streaming subscriptions?
  • Answer: Yes. Media Partners Asia forecasts that India will overtake China as the largest market for SVOD (Subscription Video on Demand) subscriptions by 2030, reaching an estimated 358 million individual subscriptions. However, India’s overall premium VOD revenue will remain lower due to a smaller Average Revenue Per User (ARPU).
  • Q3: How are streaming platforms in India shifting their business models?
  • Answer: Streaming platforms are moving away from a primary focus on raw subscriber acquisition toward monetization and engagement. This includes adopting hybrid models (combining AVOD and SVOD), launching mobile-only plans, integrating programmatic advertising, and doubling down on regional programming and Connected TV (CTV) environments.
  • Q4: What role does AI play in the future of the Indian OTT ecosystem?
  • Answer: Artificial Intelligence is becoming foundational for personalized content recommendations, automated content discovery, and targeted advertising delivery, helping platforms retain users and optimize digital ad spend, which is projected to reach $14.3 billion by 2030.