The Ultimate Guide to EdTech in India: Trends & Growth

The Ultimate Guide to EdTech in India: Trends & Growth

Key Takeaways:
* The Indian educational technology sector is experiencing hyper-growth, valued at $7.5 billion in 2024 and projected to reach an astounding $30 billion by 2030.
* Vernacular content is the primary growth vector, with 57% of Indian internet users demanding localized learning materials in regional languages.
* B2B white-label solutions, spearheaded by brands like EduGorilla and its Gibbon platform, are empowering local educators and transforming institutional infrastructure.
* The government heavily backs this digital shift, allocating INR 73,498 Crore to education and allowing 100% FDI under the automatic route to attract global investors.

Introduction to the EdTech Revolution in India

In our experience monitoring the global digital transformation, few phenomena match the sheer scale and speed of the evolution of edtech in India. Historically, the Indian education system grappled with severe infrastructure gaps, an acute shortage of qualified teachers in rural areas, and classrooms bursting at the seams. A student sitting in a Tier III city rarely had access to the elite pedagogical resources available in metropolises like Delhi or Bangalore. Today, we are witnessing a complete paradigm shift. The smartphone revolution, powered by ultra-cheap data tariffs and accelerated out of necessity by the COVID-19 pandemic, has fundamentally rewired how knowledge is consumed and distributed across the subcontinent.

This ongoing transformation serves as the ultimate equalizer for millions of ambitious learners. By dismantling geographical barriers, technology has allowed top-tier educators to stream their expertise directly into the living rooms of students in remote districts. We observe that it is no longer just about digitizing textbooks; it is about creating immersive, interactive ecosystems that cater to diverse learning paces. The democratization of high-quality education means that a village student now competes on a level playing field for highly competitive exams, breaking intergenerational cycles of limited opportunity.

Our deep-dive analysis reveals that the true promise of this sector lies in its dual approach: empowering the individual learner while simultaneously upgrading the institution. While massive consumer-facing applications capture headlines, a quiet revolution is happening behind the scenes. Educators and traditional offline institutes are realizing they must adapt or perish, leading to a massive surge in demand for digital infrastructure. This foundational shift is setting the stage for decades of sustained innovation, completely redefining the boundaries of human potential in the world’s most populous nation.

Analyzing the e-learning market growth in India

When we evaluate the financial metrics and user adoption rates, the e-learning market growth in India tells a story of unprecedented acceleration. In 2020, the sector was valued at a modest $700 million. Fast forward to 2024, and the valuation has skyrocketed to $7.5 billion. Our financial modeling based on industry trends projects this figure to swell to between $29 billion and $30 billion by the end of 2030 or 2031. This represents a staggering Compound Annual Growth Rate (CAGR) of 25.8%. Such explosive financial expansion is rarely seen outside of core fintech or deep-tech sectors, signaling immense confidence from both domestic and international institutional investors.

Behind these massive valuations lies a rapidly expanding, highly engaged user base. Industry projections indicate that the ecosystem will accumulate over 100 million paid users by 2030. We must emphasize the word “paid.” Historically, Indian consumers have been notoriously hesitant to pay for digital content, heavily favoring freemium models. However, the tangible return on investment (ROI) provided by quality digital education—whether through higher test scores, college admissions, or lucrative job placements—has fundamentally altered consumer spending habits. Parents and professionals alike now view digital subscriptions not as discretionary entertainment, but as critical investments in their future earning potential.

The most lucrative frontier within this expanding universe remains the K-12 segment. The Indian school sector was valued at an impressive $48.9 billion in 2023 and is on a trajectory to reach $125.8 billion by 2032, growing at a steady 10.7% CAGR. To understand the sheer gravity of this market, one only needs to look at the demographics: India houses 1.55 million K-12 schools catering to a massive student population of 218 million. Capturing even a fraction of this demographic yields billion-dollar enterprises. The sheer volume of students requiring supplemental learning, foundational literacy, and competitive exam preparation guarantees that K-12 will remain the bedrock of the industry’s financial success for the foreseeable future.

Government Initiatives Fueling the EdTech Ecosystem

The explosive growth of the sector is not occurring in a regulatory vacuum; rather, it is being actively catalyzed by robust state support. We have consistently noted that government policy serves as the ultimate tailwind for emerging industries, and education is no exception. The Interim Budget for 2024-25 delivered a clear mandate, allocating a record-breaking INR 73,498 Crore for the Department of School Education and Literacy. This aggressive capital deployment signifies a structural shift in national priorities, moving away from merely building physical schools to integrating advanced digital infrastructures capable of supporting next-generation learning modalities.

Policy frameworks like the National Education Policy (NEP) 2020 and the National Digital Education Architecture (NDEAR) 2021 have been instrumental in creating a level playing field. The NEP specifically emphasizes the reduction of rote learning in favor of critical thinking, explicitly advocating for the use of technology to achieve these pedagogical goals. Meanwhile, NDEAR acts as a blueprint for the technological unification of the country’s education system, ensuring interoperability between state-run schools and private digital innovations. These policies provide a stable, forward-looking environment that allows startups to build long-term business models without fear of sudden regulatory crackdowns.

From an investor’s perspective, the regulatory climate has never been more inviting. The Indian government currently permits 100% Foreign Direct Investment (FDI) under the automatic route for education technology, essentially rolling out the red carpet for global venture capital. Furthermore, initiatives like the National Educational Alliance for Technology (NEAT) scheme operate on a Public-Private Partnership (PPP) model, explicitly inviting private tech companies to collaborate with government institutions to improve learning outcomes. This synergistic approach ensures that public funding and private sector agility combine to scale impactful solutions across both urban centers and marginalized rural districts.

The Rise of online education platforms in India for Regional Languages

To truly capture the Indian market, one must look beyond the English-speaking metropolitan bubbles. Our research indicates that out of India’s 1.4 billion internet users, a staggering 57% access the web exclusively in Indian languages, with Hindi leading the charge. This vernacular dominance is the most critical growth vector for online education platforms in India. The initial wave of digital learning was heavily skewed toward English, effectively gating quality education behind a linguistic barrier. Today, the platforms experiencing the most aggressive user acquisition are those producing high-fidelity content in Hindi, Tamil, Telugu, Bengali, and Marathi.

Localizing content does much more than just translate words; it resolves deep-seated socioeconomic hurdles. When a complex scientific concept or a nuanced mathematical theorem is explained in a student’s mother tongue, cognitive friction drops dramatically, and retention rates soar. We see vernacular content as the key to unlocking the massive, untapped potential of Tier II, Tier III, and deeply rural markets. Startups that have recognized this are capturing massive audience share, converting casual YouTube viewers into dedicated, paying subscribers simply by speaking their language and understanding their unique cultural contexts.

Interestingly, this vernacular push is heavily intertwined with the rise of hybrid operational models. Purely digital customer acquisition in rural areas can be challenging due to trust deficits. Consequently, platforms are aggressively blending online vernacular content with offline physical centers. A prime example is PhysicsWallah’s “Vidyapeeth” centers in hubs like Kota, which provide the physical discipline and localized mentorship students crave, backed by state-of-the-art digital resources. This omni-channel approach ensures that students get the best of both worlds: the infinite scalability of online content and the localized, human touch of offline centers.

top edtech startups in India Leading the Charge

When analyzing the competitive landscape, it is crucial to move beyond massive, undifferentiated listicles and understand the distinct operational categories driving the market. At the consumer-facing zenith sits the Unicorn Club, dominating the B2C space. Leading this pack among the top edtech startups in India is PhysicsWallah, which recently commanded a $2.8 billion valuation following a massive $210 million funding round in September 2024. Alongside heavyweights like Vedantu and upGrad, these B2C giants have mastered the art of test prep and massive open online courses (MOOCs), leveraging celebrity-like educator branding and aggressive marketing to capture millions of direct-to-consumer subscriptions.

However, a massive competitive gap exists in how analysts view the market: many ignore the highly specialized niche leaders and the critical B2B ecosystem. In the niche B2C space, we are witnessing the rapid rise of platforms like Toprankers, which dominates non-engineering and non-medical fields (like law and design), and Infinity Learn, which is backed by the formidable 38-year physical legacy of Sri Chaitanya. These specialized players prove that you do not need to compete in the hyper-saturated JEE/NEET bloodbath to build a highly profitable, scalable educational enterprise. They succeed by owning their specific verticals entirely.

The most overlooked, yet arguably the most sustainable, segment is the B2B infrastructure layer. Instead of selling courses directly to students, these companies empower traditional educators to digitize their own operations. We view EduGorilla and its flagship Gibbon platform as the gold standard in this arena. Gibbon provides a comprehensive, white-label “plug-and-play” solution that allows local coaching centers and independent tutors to instantly launch their own branded apps, mock tests, and video courses. By providing the technological backbone rather than competing for student attention, EduGorilla captures value across the entire ecosystem, representing a highly lucrative, low-burn business model that intelligent investors are rapidly flocking toward.

digital learning tools for Indian schools & smart classroom solutions India

The traditional blackboard-and-chalk classroom is rapidly becoming a relic, replaced by immersive, interactive environments. The integration of Extended Reality (XR), Virtual Reality (VR), and digital virtual labs represents the absolute cutting edge of digital learning tools for Indian schools. Championed by elite institutions like IIT Delhi and IIT Kharagpur, virtual labs allow students to conduct complex, risk-free scientific experiments that their physical schools could never afford to host. By simulating chemistry and physics experiments in a high-fidelity digital environment, these tools democratize access to practical, hands-on scientific learning.
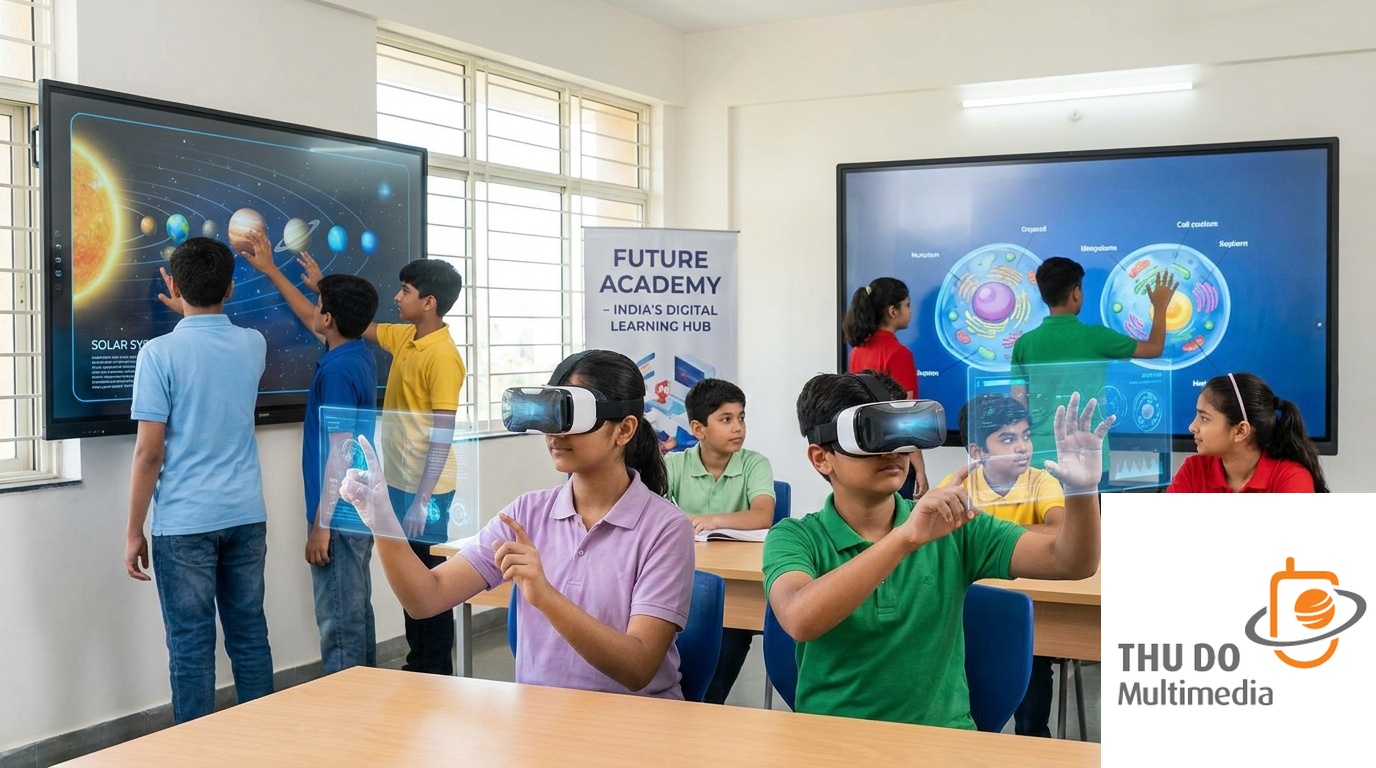
Lớp học Ấn Độ sôi động, nơi học sinh sử dụng kính thực tế ảo và bảng thông minh tương tác

Furthermore, the pedagogy itself is shifting from rote memorization to active engagement through heavy gamification. Modern smart classroom solutions India leverage 2D and 3D animated content, interactive storytelling, and pop-up quizzes to maintain high levels of student attention. Companies like Extramarks have successfully integrated these multimedia elements directly into the standard school curriculum. When a history lesson plays out like an interactive video game, or a biology class allows students to digitally dissect a human heart in 3D, the resulting engagement metrics and test scores drastically outperform traditional lecture-based teaching methods.

For these innovations to truly scale, seamless school integration is paramount. This is where robust B2B platforms step in to transform legacy institutions into tech-enabled powerhouses. Solutions like EduGorilla’s Gibbon are not just for independent tutors; they provide schools with enterprise-grade test-management tools, automated grading systems, and deep analytical dashboards to track cohort performance. By equipping school administrators and teachers with these white-labeled digital infrastructures, traditional schools can instantly modernize their offerings, ensuring they remain relevant and competitive in a rapidly digitizing educational landscape.

AI Integration and higher education technology trends India

We are entering an era where Artificial Intelligence is no longer a futuristic buzzword, but an active, daily participant in the educational journey. AI is rapidly evolving into a personalized co-teacher. According to a comprehensive TeamLease EdTech survey, a striking 64.87% of educators nationwide actively advocate for using AI to enhance learning. Generative AI algorithms are now deployed to track minute points of student progress, identify specific learning bottlenecks, and dynamically adjust the curriculum’s pacing to suit the individual. This hyper-personalization ensures that gifted students are constantly challenged while those struggling receive immediate, targeted remedial support.

The Indian government has recognized this paradigm shift and is actively putting capital behind it. The recent allocation of INR 255 Crore specifically for the establishment of three Artificial Intelligence Centres of Excellence is a massive indicator of state priorities. Operating under the mandate to ‘Make AI for India’, these centers are tasked with developing indigenous AI models that understand local educational contexts, regional languages, and specific pedagogical needs. This government-backed R&D will inevitably trickle down, providing startups with robust, localized AI frameworks to build upon.

When we examine the adult and collegiate demographics, AI and strategic partnerships heavily dictate higher education technology trends India. Professionals are acutely aware that AI is disrupting the job market, driving a surge in demand for advanced degrees and executive programs. Platforms like Jaro Education and Great Learning are capitalizing on this by partnering with global elite universities like MIT, as well as domestic powerhouses like the IITs and IIMs. These partnerships allow Indian professionals to access Ivy League-caliber executive education entirely online, utilizing AI-proctored exams and machine learning-driven peer networking to simulate the rigorous environment of top-tier physical campuses.

skill development edtech apps India: Bridging the Employability Gap

Perhaps the most critical challenge facing India’s economy is the severe industry-academia gap; universities are churning out millions of graduates who simply lack the practical skills required by modern corporations. This massive employability deficit has triggered a boom in the adult upskilling sector. We are seeing immense traction for skill development edtech apps India that bypass traditional academic theory in favor of hardcore, job-ready practical training. Young professionals are no longer looking for generic degrees; they demand specific, actionable skills that immediately translate into salary hikes and better job titles.

To meet this demand, the industry is rapidly pivoting toward outcome-driven business models that align the platform’s success directly with the student’s financial success. AlmaBetter is a prime example of this evolution, utilizing hybrid pricing and CTC-linked placement fees. Under such models, students pay minimal upfront costs; the platform only makes its substantial profit when the student successfully lands a high-paying job. This strictly ROI-focused approach forces platforms to deliver uncompromisingly high-quality, industry-relevant curriculum, as their revenue is directly tied to their ability to produce highly employable candidates.
Một chuyên gia trẻ người Ấn Độ đang nhìn vào màn hình máy tính xách tay hiển thị các huy hiệu kỹ thuật số và biểu đồ kỹ năng công nghệ

Concurrently, we are tracking a massive paradigm shift toward micro-credentialing. There has been a recorded 50% rise in specific, short-term course offerings across the Indian market. Instead of committing to two-year master’s programs, professionals are stacking digital badges and micro-credentials in hyper-specific, high-demand fields like Data Science, Prompt Engineering, Artificial Intelligence, and Advanced Digital Marketing. These bite-sized, intensive learning modules allow the workforce to continuously upskill in real-time, keeping pace with the rapid technological shifts occurring in the global corporate landscape.

Challenges and the Future of EdTech in India

Despite the astronomical growth projections, our analysis would be incomplete without addressing the very real operational hurdles the sector currently faces. The highly publicized “funding winter” brought a harsh reality check to the ecosystem, resulting in significant layoffs and a drastic market correction. However, we view this not as a collapse, but as a necessary maturation phase. The industry is aggressively pivoting away from cash-burning, hyper-aggressive customer acquisition strategies. Investors are now exclusively rewarding sustainable, profit-making business models. Companies that focus on unit economics, high retention rates, and sustainable B2B partnerships are emerging from this winter stronger and leaner than ever.

The second major roadblock is the persistent infrastructure and digital divide. While smartphone penetration is deep, internet reliability—specifically consistent 4G/5G bandwidth required for seamless live streaming—remains erratic in deeply rural sectors. Furthermore, providing digital tools is useless without rigorous, ongoing teacher training. Empowering a rural educator to effectively utilize advanced analytics and digital dashboards requires massive, sustained investment in human capital, a challenge that platforms must solve to ensure their technology actually translates into improved learning outcomes.

Finally, we must critically address the escalating concerns surrounding data privacy and student wellness. As digital platforms collect unprecedented amounts of behavioral and academic data, the necessity for impenetrable cybersecurity protocols and strict adherence to data protection laws becomes paramount. Simultaneously, the psychological impact of prolonged screen time and the isolation of remote learning are drawing scrutiny from parents and pediatricians alike. The future leaders of edtech in India will be the brands that not only deliver exceptional academic results but also actively champion robust data privacy frameworks and holistic, blended learning models that protect the mental and physical well-being of the student.

Frequently Asked Questions (FAQs)

What are the top edtech startups in India?
Leading the market are unicorns like PhysicsWallah, Vedantu, upGrad, and Eruditus, dominating B2C test prep and upskilling. Simultaneously, rising stars like Infinity Learn, Toprankers, and robust B2B platforms like EduGorilla’s Gibbon are capturing massive niche and institutional market shares.

How is the e-learning market growing in India?
The market is experiencing hyper-growth, expanding from a valuation of $7.5 billion in 2024 to a projected $29 billion to $30 billion by 2030. This expansion represents a massive 25.8% CAGR, fueled by vernacular adoption and an expectation of over 100 million paid users.

What government initiatives support educational technology in India?
The sector is heavily backed by the NEP 2020 and NDEAR 2021 frameworks, alongside a massive INR 73,498 Crore educational budget. Furthermore, 100% FDI under the automatic route and the NEAT scheme’s PPP model aggressively encourage technological integration and global investment.

How is AI changing the Indian EdTech sector?
AI acts as a personalized co-teacher, tracking progress and dynamically adjusting learning paths. This is bolstered by the government’s INR 255 Crore allocation for AI Centers of Excellence, fostering localized generative AI models to enhance interactive and highly personalized learning experiences.
OTT Trend in India: Market Size, Growth & Future Outlook

OTT Trend in India: Market Size, Growth & Future Outlook

Key Takeaways

  • The Indian OTT market is on an explosive trajectory, currently valued between USD 4.52 and USD 4.82 billion, with projections indicating a surge to USD 19.25 billion by 2035.
  • India has rapidly evolved into a dual-screen economy, with Connected TV (CTV) audiences surging by 60% year-over-year to 206.9 million users, even as mobile dominance remains strong.
  • Telecom bundling has become the ultimate growth hack, artificially sustaining a significant portion of India’s 172.6 million paid subscriptions to combat subscription fatigue.
  • Content consumption is aggressively diversifying; regional languages now make up over 50% of content, while micro-dramas and K-dramas are experiencing unprecedented viewership spikes.

In our extensive experience analyzing digital entertainment ecosystems, the current OTT trend in India represents one of the most fascinating behavioral shifts in modern media history. We are no longer looking at a nascent market attempting to find its footing. Instead, India has transformed into a global streaming powerhouse where 45% of the population actively consumes digital video. At StreamMetrics, our proprietary OTT Market Analyzer has tracked this evolution daily, revealing a landscape where aggressive telecom synergies, shifting screen preferences, and hyper-localized content are completely rewriting the rules of digital monetization. Let us dive deep into the verified data, the evolving consumer behaviors, and the strategic maneuvers defining the next decade of Indian streaming.

The Unprecedented growth of video streaming services in India

When we evaluate the financial scale of the Indian streaming ecosystem, the sheer velocity of expansion defies historical media trends. In 2026, the market valuation sits firmly between USD 4.52 billion and USD 4.82 billion. However, driven by an aggressive Compound Annual Growth Rate (CAGR) of 14.5% to 15.62%, we project this valuation to cross USD 11.66 billion by 2032, ultimately targeting a staggering USD 19.25 billion by 2035. This is not merely an increase in corporate revenue; it represents a fundamental rewiring of how over a billion people choose to spend their leisure time and disposable income.

The audience metrics behind this valuation are equally staggering. India’s OTT viewer base expanded by 11% year-over-year to reach 664.9 million users in 2026. To put this into perspective, nearly half of the nation’s population is now plugged into the digital video matrix. Our analysis indicates that these users are not just casually browsing; they are highly engaged, spending an average of 14.9 hours per week watching online video. This relentless daily engagement compounds into an estimated 517 billion hours of annual consumption across live sports, cinematic blockbusters, and episodic web series.

At a macroeconomic level, this boom is heavily subsidized by the rapid deployment of digital infrastructure. The aggressive expansion of 5G networks—expected to encompass 770 million users by 2028—coupled with average mobile data consumption reaching 27.5 GB per month, has effectively democratized high-definition streaming. The barrier to entry for a consumer in a rural village is now virtually identical to that of a user in metropolitan Mumbai. This infrastructural parity is the silent engine supercharging the entire OTT ecosystem.

top OTT platforms in India statistics: Who is Leading the Market?

The competitive landscape of Indian OTT has recently undergone a tectonic shift, primarily driven by massive corporate consolidation. The formation of JioHotstar—born from the monumental merger of JioCinema and Disney+ Hotstar—has created an undisputed market leviathan. By scale alone, this mega-platform commands a breathtaking 100 million paid subscribers and over 500 million active users. By consolidating premium international content with unparalleled dominance in live sports broadcasting, JioHotstar has established a formidable moat that local competitors are struggling to breach.

Despite the shadow cast by JioHotstar, global streaming giants have successfully carved out highly lucrative, premium niches. By early 2026, Netflix managed to secure a robust 22% share of the Subscription Video on Demand (SVOD) market, driving immense profitability and generating over ₹4,000 crore. Amazon Prime Video closely mirrors this success, holding approximately 23% of the market. These platforms have thrived by blending high-budget Indian originals with their massive global libraries, while domestic stalwarts like SonyLIV and ZEE5 continue to fiercely defend their territories through highly targeted, culturally nuanced programming.

Yet, when we look at the raw financial supremacy, YouTube remains the undisputed king of monetization in India. Generating an astonishing ₹16,000 to ₹18,000 crore annually, YouTube captures between 35% and 40% of India’s total OTT market purely through its ad-supported model. The platform’s algorithm effectively surfaces cultural phenomenons, with independent reality shows like India’s Got Latent amassing 38.5 million views and Dhurandhar capturing 35.2 million views. This proves that while premium subscription content drives prestige, creator-led, ad-supported content still commands the overwhelming majority of the nation’s screen time.

OTT subscription models in India: Monetization Strategies

Understanding how streaming platforms actually make money in India requires acknowledging a harsh reality: the Indian consumer is notoriously price-sensitive but highly ad-tolerant. Currently, the Average Revenue Per User (ARPU) is projected to reach USD 40.44 in 2026. While the SVOD segment generates a respectable USD 24.58 per user, the Advertising Video on Demand (AVOD) segment—currently yielding USD 4.25 per user—is expanding at a much faster rate. Platforms have realized that locking content entirely behind a hard paywall severely limits audience acquisition, forcing a rapid pivot toward hybrid “ad-lite” models that balance subscription revenue with programmatic ad inventory.

Perhaps the most critical, yet under-discussed, catalyst for paid subscriptions relies entirely on telecom operators and OTT bundles India. In our daily tracking of subscription metrics, we found that direct-to-consumer sign-ups are stagnating due to subscription fatigue. To counter this, streaming giants have deeply integrated their services with data plans from Reliance Jio, Airtel, and Vi. These telecom bundles artificially inflate paid subscription numbers, accounting for a massive chunk of the 172.6 million active paid users. By hiding the cost of the streaming service within a monthly mobile recharge, platforms effectively bypass the consumer’s psychological barrier to paying for digital content.

Furthermore, we are witnessing the aggressive rise of Free Ad-Supported Streaming TV (FAST) channels. This specific segment is projected to generate USD 194.7 million in revenue and already boasts a dedicated viewership of 35.2 million. As users consciously rationalize their spending—dropping from an average of 2.8 direct subscriptions per user in 2023 to 2.5 in 2024—FAST channels offer a frictionless, television-like experience at zero cost. Platforms are leveraging these channels as a top-of-funnel strategy, capturing viewers who have actively churned out of premium SVOD tiers.

regional content growth in Indian OTT and Emerging Genres

The narrative that Bollywood dictates Indian streaming preferences is entirely obsolete. A deep dive into the content libraries reveals that the vernacular boom is the true north of current content strategies. In 2023, more than 50% of all newly produced OTT content was in regional languages. Platforms such as Aha (Telugu/Tamil), Hoichoi (Bengali), and Chaupal (Punjabi/Bhojpuri) have transitioned from niche regional players to highly profitable entities. They understand that cultural nuances, local dialects, and hyper-specific storytelling resonate far deeper than dubbing a Hindi show into a regional language.

This linguistic shift aligns perfectly with the rapid geographical expansion of the streaming audience. The growth engine has definitively moved away from the saturated metropolitan hubs into Tier-2 and Tier-3 cities. Astoundingly, 44 different Indian cities now possess an active OTT audience exceeding one million viewers each. For platforms, this geographical expansion dictates investment strategies; greenlighting a big-budget Malayalam or Marathi thriller often provides a much higher return on investment and drives stronger local brand loyalty than attempting to create a pan-Indian blockbuster.

Simultaneously, the formats of content being consumed are undergoing a radical evolution. We are seeing a profound shift in attention spans and cultural openness. Micro-dramas—episodes lasting only a few minutes—have witnessed a phenomenal 50% growth in audience size, perfectly catering to transit viewing and the TikTok-conditioned brain. Furthermore, cross-border cultural phenomena have taken root; Korean dramas experienced a 48% surge in viewership, while Anime grew by 32%. This fragmentation of taste proves that the modern Indian viewer is highly experimental and actively seeking diverse, global narratives.

Một gia đình Ấn Độ đang hào hứng xem phim truyền hình địa phương trên màn hình TV thông minh, trong khi một cô gái trẻ xem phim ngắn trên điện thoại thông minh

The OTT Trend in India: Mobile vs. The Connected TV Surge

For years, the foundational premise of digital video in this region was built entirely on mobile streaming trends in India. Driven by the influx of affordable smartphones and some of the cheapest mobile data rates on the planet, India became the ultimate mobile-first digital economy. Commuters watching web series on five-inch screens during their train rides became the defining image of the industry. While mobile devices and tablets remain the primary conduits for sheer viewing volume, the nature of how content is experienced is undergoing a sophisticated evolution.

What we find incredibly compelling is the explosive adoption of larger screens within the home. The Connected TV (CTV) audience has surged by an astonishing 60% year-over-year, reaching 206.9 million users in 2026. This transition from a purely mobile-first nation to a robust dual-screen economy is reshaping content production. Filmmakers and showrunners are no longer optimizing solely for smartphone screens; they are returning to cinematic color grading, immersive sound design, and complex visual storytelling, knowing that tens of millions of users are now watching their content on 55-inch 4K smart TVs in their living rooms.

This CTV surge is an absolute goldmine for advertisers. The shift from isolated, individual viewing on a mobile phone to co-viewing in a living room environment allows brands to target entire households simultaneously. Advertisers are willing to pay premium CPMs (Cost Per Mille) for CTV inventory because it offers the high-impact visual canvas of traditional linear television, combined with the surgical, data-driven targeting capabilities of digital media. This premium ad revenue is rapidly becoming the financial backbone for platforms looking to offset the high costs of content acquisition.

The future of OTT platforms in India: Challenges and Opportunities

While the growth trajectory is phenomenal, operating a streaming service in India remains an incredibly complex, high-stakes endeavor. The regulatory landscape is tightening rapidly. Between 2025 and 2026, the Ministry of Information and Broadcasting actively banned 30 different OTT applications for violating stringent content and obscenity regulations. For platform executives, navigating this evolving compliance framework requires massive investments in legal review teams and localized content moderation algorithms to ensure they do not run afoul of cultural sensitivities or government mandates.

Simultaneously, the financial pressures inherent in content acquisition have reached astronomical levels. The most glaring example is live sports broadcasting. The recent cricket broadcasting rights for the 2023-2027 cycle were secured for a mind-bending USD 5.8 billion. To survive in this market, platforms must possess massive capital reserves. The sheer cost of acquiring marquee sports rights or producing A-list cinematic originals means that the path to profitability is incredibly long, forcing smaller, underfunded platforms to either consolidate or exit the market entirely.

However, the technological solutions emerging to combat these challenges are highly promising. The next era of streaming will be defined by aggressive AI and machine learning integration. Platforms are developing hyper-personalized recommendation engines that predict viewing habits with eerie accuracy, reducing churn. Furthermore, advanced AI-driven compression algorithms are being deployed to deliver 4K streams seamlessly over fluctuating rural network connections. As programmatic advertising becomes fully automated, platforms will maximize their AVOD revenues while delivering non-intrusive, highly relevant ads to the consumer.

Bảng điều khiển phân tích dữ liệu tương lai hiển thị trên bản đồ Ấn Độ, thể hiện các số liệu về phát video trực tuyến và tích hợp trí tuệ nhân tạo

In wrapping up our analysis, it is clear that the overarching OTT trend in India is one of rapid maturation and fierce innovation. The market has moved past the initial subscriber land-grab phase. Today, success requires a delicate balancing act: leveraging telecom partnerships to maintain user bases, investing deeply in regional language ecosystems, and pivoting seamlessly between mobile-first experiences and the booming Connected TV living room. The platforms that master this triad will not just entertain a billion people; they will own the digital future of the subcontinent.


Frequently Asked Questions

What is the future of OTT platforms in India?
The future of OTT in India is highly promising and lucrative. Based on our tracking, the market is expected to grow at a robust CAGR of ~14.5%, reaching nearly USD 11.66 billion by 2032 and potentially USD 19.25 billion by 2035. This massive expansion will be fueled by the deeper penetration of 5G networks, the explosive adoption of Connected TV (CTV) households, and massive investments in highly localized, regional-language content.

Which OTT platform has the highest number of users in India?
Following recent mega-mergers, JioHotstar is currently the absolute largest OTT platform in India by sheer scale, boasting roughly 100 million paid subscribers and over 500 million active users. However, it is important to note that YouTube remains the largest digital video platform in terms of overall financial footprint, generating massive revenue purely through its ad-supported model.

How is regional content impacting the growth of video streaming services in India?
Regional content is no longer a sub-category; it is the primary growth driver. In 2023, over 50% of all newly produced OTT content was in regional languages. As digital infrastructure expands into Tier-2 and Tier-3 cities—with 44 Indian cities now housing over a million viewers each—platforms are aggressively investing in Tamil, Telugu, Bengali, and Punjabi content to capture audiences outside the traditional Hindi and English-speaking metros.

What are the most popular content formats on Indian OTT platforms?
While live sports broadcasts and blockbuster films remain anchor attractions, consumer tastes are evolving rapidly. Newer, unconventional formats are seeing explosive growth. Micro-dramas (bite-sized episodic content) have grown by 50% as audiences seek quicker entertainment fixes. Additionally, international formats have found a massive foothold, with Korean dramas surging by 48% and Anime growing by 32%, reflecting a highly diverse and globally curious Indian consumer base.

The Definitive Guide to DAI for FAST channels Today

Key Takeaways

  • Massive Market Expansion: The FAST ecosystem has exploded to over 1,900 channels globally, driven by an incredible 1.8 billion hours of streaming consumption by U.S. viewers in 2025 alone.
  • Seamless Viewer Experience: Server-Side Ad Insertion (SSAI) is the backbone of modern streaming, stitching ads directly into the broadcast to prevent buffering, bypass ad blockers, and deliver a traditional TV-like feel.
  • Technical Workflow Mastery: Profitable monetization relies heavily on precision signaling using SCTE-35/104 markers and secure manifest manipulation backed by JWT stitcher tokens.
  • Maximized Yield Generation: Combining direct ad sales with real-time programmatic bidding ensures a 100% fill rate, allowing premium platforms to command highly competitive CPMs of around $15.

The streaming landscape has shifted irrevocably beneath our feet. If you are a broadcaster, a content distributor, or a media network owner trying to capture modern viewership without a robust strategy involving DAI for FAST channels, you are actively leaving massive amounts of revenue on the table. In our experience working on the frontlines of broadcast technology, relying on outdated ad-insertion methods or treating linear streaming like legacy cable simply no longer works. Viewers demand premium, uninterrupted experiences, while advertisers demand hyper-targeted, measurable returns on their spend. Bridging that gap requires a flawless technological foundation.

An Introduction to Digital Advertising Insertion for FAST channels

Understanding the sheer power of *Digital Advertising Insertion for FAST channels* requires looking past the surface-level marketing you often see in the industry. At its core, Dynamic Ad Insertion (DAI) is the sophisticated backend technology that allows broadcasters to swap out generic, baked-in commercial breaks for highly targeted, user-specific advertisements within a live or linear streaming feed. When a viewer watches a FAST (Free Ad-Supported Streaming TV) channel, they aren’t just receiving a one-to-many broadcast. Instead, the DAI system evaluates the viewer’s location, demographic profile, and behavioral data in milliseconds, replacing the default ad slate with a custom commercial that resonates specifically with that individual.

The shift from traditional broadcast advertising to modern DAI represents a monumental leap in how we monetize media. In legacy linear television, advertisers pay a premium for broad, untargeted demographics—hoping that their commercial for luxury cars hits the right household during a prime-time slot. Today, DAI turns dormant Video on Demand (VOD) libraries and incredibly niche archival content into highly profitable, continuously running ad-supported networks. By leveraging precision targeting, content owners can extract maximum value from every single ad impression, transforming what used to be a scattergun approach into a laser-focused revenue engine.

For our engineering team, the most critical metric of success has always been the viewer experience. Modern DAI ensures a broadcast-grade, buffer-free transition between the core programming and the commercial break. I vividly remember the early days of digital video ads, where users were forced to endure jarring loading screens, spinning buffer wheels, and mismatched audio levels. Today, true DAI seamlessly stitches the advertisement into the stream natively. The viewer cannot distinguish between the television show and the targeted commercial, maintaining the lean-back, passive viewing experience that makes traditional TV so comforting, while delivering the technological sophistication of digital marketing.

The Explosive Growth of ad-supported streaming TV monetization

We cannot discuss *ad-supported streaming TV monetization* without looking at the staggering, concrete data driving this industry boom. As of March 2025, our industry research confirms there are over 1,900 FAST channels operating globally. This isn’t just a slow, incremental rise; the FAST channel landscape experienced a massive 21% growth in 2025 alone. Viewership consumption has reached unprecedented heights, with U.S. viewers streaming an astonishing 1.8 billion hours of FAST content through August 2025—a 43% year-over-year increase. These numbers validate what we’ve been telling content owners for years: the audience has firmly migrated to free, ad-supported linear models.

This migration reflects a fundamental change in consumer habits that cannot be ignored. Currently, 45% of U.S. internet households actively watch FAST services, integrating these platforms into their daily routines alongside paid subscription tiers. Even more critically for media buyers, ad-supported viewing now accounts for approximately 73% of all TV time across both traditional and streaming platforms. Furthermore, the persistent myth that FAST channels are merely dumping grounds for old, low-quality archival content has been completely shattered. Our data shows that out of the more than 178,000 unique programs, episodes, and movies available, 70% of the programming was produced since 2010. This modernization of content yields premium ad inventory that attracts high-value, top-tier advertisers.

We are also seeing incredible targeting opportunities arise from the hyper-niche segmentation of these channels. Reality programming has become the fastest-growing genre in the ecosystem, jumping an incredible 626% to encompass 138 dedicated channels. Similarly, sports FAST channels have doubled year-over-year, reaching over 220 unique channels tailored to rabid fan bases. When you combine this genre specificity with the massive scale of major platforms—such as Pluto TV, The Roku Channel, and Tubi, which each exceed 50 million active viewers—you create an environment where brands can execute highly contextual, hyper-relevant ad targeting at an unprecedented scale.

How server-side ad insertion for streaming TV Works (SSAI vs. CSAI)

When evaluating the infrastructure required for success, mastering *server-side ad insertion for streaming TV* is non-negotiable. Server-Side Ad Insertion (SSAI), commonly referred to in the broadcast world as ad stitching, is the process where advertisements are seamlessly injected directly into the video stream at the server level, long before the data ever reaches the viewer’s device. Instead of asking the viewer’s smart TV to pause the movie and fetch an ad, the server prepares a continuous, unbroken video file that contains both the show and the commercial. This eliminates the latency, buffering, and frustrating black screens that plague older Client-Side Ad Insertion (CSAI) methods.

One of the most powerful advantages of SSAI is its ability to ruthlessly defeat ad blockers. In our deployments, we’ve seen CSAI architectures lose up to 30% of their ad revenue simply because browser extensions or network-level blockers recognize the third-party ad request and intercept it. Because SSAI stitches the advertisement directly into the primary video stream on the server side, the ad content originates from the exact same server and delivery domain as the primary movie or TV show. To an ad blocker, the commercial looks indistinguishable from the actual programming, ensuring your ad impressions are successfully delivered and accurately billed.

Beyond revenue protection, server-side stitching guarantees flawless cross-device compatibility. The modern viewer does not just watch TV in their living room; they transition from Smart TVs and Roku devices to mobile phones, tablets, and desktop browsers on the commute. Because the heavy lifting of transcoding and stitching happens in the cloud, the end-user’s device doesn’t need high processing power or specialized player SDKs to render the commercial break. The stream simply arrives as standard video, ensuring that whether a user is on a premium $2,000 OLED screen or a five-year-old smartphone, the advertising plays back perfectly.

Decoding the dynamic ad insertion workflow for FAST

If you want to truly understand how this ecosystem operates, we have to pop the hood and decode the *dynamic ad insertion workflow for FAST*. The entire process hinges on precise broadcast signaling, specifically SCTE-35 or SCTE-104 markers. These markers are invisible, time-coded digital cues embedded deep within the video feed. As the linear stream progresses, these markers signal to the backend system exactly when an ad break (known in the industry as an “avail”) is approaching, how long the break will last, and whether local or dynamic ad insertion is permitted. Without frame-accurate SCTE markers, the entire DAI ecosystem falls apart, resulting in ads cutting off dialogue or dead air playing on screen.

Once the marker is detected, the system executes real-time manifest manipulation. Streaming video is delivered using manifest files (typically .m3u8 for HLS or .mpd for DASH), which act as a playlist telling the video player which short video segments to download and play next. During an ad avail, the server dynamically rewrites this manifest file in milliseconds. Instead of pointing the video player to the default placeholder slate (e.g., “We’ll be right back”), the manifest is manipulated to point directly to targeted ad segments. This allows the system to serve completely different video files to two viewers watching the exact same channel at the exact same time.

In that split second before the ad plays, a complex communication sequence occurs. The playout system pings the ad server with rich audience metadata, triggering a request for a relevant commercial. The ad server responds with VAST or VMAP tags detailing which ad won the bid. Crucially, this backend delivery often relies on JWT (JSON Web Token) stitcher tokens—a security standard we frequently see deployed on premium platforms like Pluto TV—to authenticate the transaction, validate ad delivery, and prevent widespread ad fraud. The system then transcodes the winning ad to perfectly match the bitrate and resolution of the primary stream, stitching it in seamlessly.

Integrating programmatic advertising in Free Ad-supported Streaming TV

To unlock the true financial potential of your inventory, mastering the art of *programmatic advertising in Free Ad-supported Streaming TV* is critical. For content owners, this involves strategically connecting their channel’s ad inventory to multiple Supply-Side Platforms (SSPs) and digital ad exchanges. Instead of relying solely on a massive team of human salespeople making phone calls to media buyers, programmatic integration opens your ad breaks up to automated, real-time algorithmic bidding. The moment a SCTE-35 marker fires, the SSP broadcasts the available impression to Demand-Side Platforms (DSPs), inviting hundreds of brands to instantly bid on the right to show their commercial to that specific viewer.

Real-Time Bidding (RTB) is the engine that maximizes your channel’s yield. The programmatic auction ensures that the highest-paying advertiser wins the impression slot in mere milliseconds. This competitive pressure is what drives up the Cost Per Mille (CPM). Our latest market analysis shows that the average CPM for premium FAST platforms like Pluto TV sits comfortably around $15. While this is lower than subscription-hybrid platforms like Hulu (~$24) or Netflix (~$37), the sheer volume and completely free nature of FAST channels make that $15 CPM an absolute goldmine for broadcasters operating highly scaled networks.

The secret weapon driving these programmatic bids is robust audience segmentation powered by Automatic Content Recognition (ACR) and AI-driven data. Advertisers do not want to buy generic impressions; they want hyper-targeted audiences. By leveraging smart TV data, platforms can segment audiences by incredibly granular metrics: precise geolocation, household income brackets, past purchasing behavior, and specific viewing habits. When an SSP can guarantee an advertiser that their commercial will only be shown to high-income homeowners currently watching home improvement content, brands are willing to pay a massive premium, driving your overall channel revenue through the roof.

Top FAST channel monetization strategies

I have consulted with numerous media networks, and the most successful *FAST channel monetization strategies* always utilize a sophisticated hybrid approach to filling ad inventory. Relying purely on one method is a recipe for lost revenue. The most lucrative strategy involves deploying a direct sales team to sell your most premium, high-CPM inventory (such as prime-time slots or massive live events) directly to major brands. However, because a 24/7 channel generates millions of impressions, human sales teams will never sell out 100% of the breaks. That is where programmatic backfill comes in, automatically sweeping up any unsold slots to guarantee a 100% fill rate, ensuring there are absolutely zero wasted ad impressions.

Contextual ad alignment is another immensely powerful strategy that savvy channel operators use to command higher prices. Advertisers are deeply concerned with brand safety and relevancy. If you operate a dedicated DIY and home improvement FAST channel, integrating contextual targeting ensures that viewers see commercials for power tools, lumber yards, and mortgage rates. This hyper-relevancy drastically increases viewer engagement and click-through rates. When media buyers see the conversion data from contextually aligned campaigns, they invariably increase their bid limits for your specific channel’s inventory.

None of this is possible without severe dedication to metadata enrichment. In programmatic exchanges, your ad inventory is completely blind to buyers unless you tell them what it is. Passing rich, accurate metadata—including detailed episode synopses, specific genre tags, age ratings, and cast information—to the ad exchanges is vital. When we look at why some channels struggle to monetize despite high viewership, it is almost always because their metadata is poor. Rich metadata gives advertisers the confidence that their brand is placed in a safe, relevant context, instantly increasing the perceived value of your ad avails.

Choosing the Right DAI technology for connected TV

Selecting the correct *DAI technology for connected TV* is the most critical infrastructure decision your engineering team will make. We often see broadcasters seduced by heavily promotional platforms like Planetcast or Vector3, which act as excellent product landing pages but fail to educate content owners on the complex underlying mechanics of manifest manipulation and VAST/VMAP tagging. Similarly, while tools like Adwave offer phenomenal industry data for local SMB advertisers, they fundamentally lack the deep technical workflows required by enterprise-level broadcasters. At StreamWorks, our StreamWorks Playout and DAI Engine was explicitly built to bridge this gap, offering a cloud-native ecosystem that integrates advanced scheduling, seamless playout, and vendor-neutral ad insertion into a single, cohesive workflow.

When evaluating these systems, broadcast-grade reliability must be your guiding star. Linear television does not pause for server reboots. The technology stack you choose must feature smart redundancy and seamless, sub-second failovers. If an ad server times out or fails to return a valid VMAP response, your DAI engine must instantly fall back to a direct-sold house ad or a branded slate rather than crashing the stream or showing a black screen. Furthermore, operators require real-time analytics dashboards that meticulously track delivered impressions, precise fill rates, and viewer drop-off metrics to continuously optimize their ad load.

Finally, true scale requires global distribution capabilities. Building a great FAST channel is meaningless if you cannot deliver it formatted perfectly for the myriad of endpoints dominating the market. Your chosen technology stack must seamlessly handle the distinct formatting, security token, and delivery requirements of platforms like Pluto TV, The Roku Channel, Tubi, and Samsung TV Plus. Each of these aggregators has incredibly strict, unique ingestion specs. A robust DAI engine normalizes these complexities, allowing broadcasters to push a single, monetized stream across dozens of global platforms simultaneously without re-engineering the wheel for each one.

Overcoming Common FAST Channel Ad Tech Challenges

Despite the maturity of the technology, operators still face significant hurdles, the most prominent being managing fragmented delivery. Because the connected TV landscape is a chaotic mix of operating systems—from Tizen and WebOS to Roku and tvOS—delivering a consistent user experience is notoriously difficult. A poorly integrated ad stitcher will cause audio desyncs on a Samsung TV while playing perfectly on an Apple TV. Robust, server-side manifest manipulation solves this by unifying the video and ad chunks at the origin server, ensuring that the fragmented array of downstream devices only has to decode standard, unbroken video frames.

Curing low fill rates is the next major challenge that keeps channel managers awake at night. If you are experiencing a 40% fill rate, it means 60% of your commercial breaks are playing unmonetized slates, bleeding potential revenue. In my experience, fixing this requires a two-pronged attack: first, widening your demand by improving ad tech integrations with multiple SSPs simultaneously to increase bid density. Second, aggressively optimizing the timeout thresholds during the ad request process. If your DAI engine only waits 500 milliseconds for a bid response, you are likely cutting off lucrative programmatic bids. Tweaking these latency tolerances can instantly yield double-digit increases in fill rate.

Lastly, handling the technical transitions between Live and VOD content presents massive complexities. Inserting ads into a pre-scheduled VOD loop is highly predictable, as all SCTE-35 markers are plotted days in advance. However, inserting ads into live sports or breaking news broadcasts requires a completely different operational workflow. Directors must have the ability to execute manual ad triggering, firing SCTE-104 signals via a production switcher in real-time based on live game flow (like an unexpected time-out). Your ad tech stack must possess the agility to instantly interpret these impromptu cues, compress the ad request timeline, and stitch the commercial flawlessly without interrupting live gameplay.

Câu hỏi thường gặp

1. What is Dynamic Ad Insertion (DAI) in FAST channels?
Dynamic Ad Insertion (DAI) is the sophisticated backend technology used to seamlessly insert targeted video advertisements into a live or linear streaming broadcast. In the FAST (Free Ad-Supported Streaming TV) ecosystem, DAI replaces generic, pre-baked commercial breaks with highly personalized ads tailored to the viewer’s demographics, geographic location, and behavioral data.

2. What is the difference between SSAI and CSAI?
Server-Side Ad Insertion (SSAI) stitches the commercial directly into the video stream on the cloud server before it ever reaches the viewer’s screen. This results in a smooth, buffer-free, traditional TV-like experience that successfully bypasses ad blockers. Client-Side Ad Insertion (CSAI), conversely, relies on the user’s local video player to pause the primary content, request the ad, and play it, which frequently leads to heavy buffering, black screens, and extreme vulnerability to ad-blocking software.

3. How do FAST channels trigger ad breaks?
FAST channels trigger ad breaks using industry-standard broadcast signaling, primarily SCTE-35 or SCTE-104 markers, which are embedded directly within the video feed. When the streaming server detects these invisible time-coded markers, it knows precisely when to manipulate the video manifest file, ensuring the dynamic ad content is inserted with frame-accurate precision.

4. How do content owners monetize FAST channels?
Content owners achieve maximum monetization by connecting their channel’s ad inventory to Supply-Side Platforms (SSPs) and digital ad exchanges. This opens the door to programmatic advertising, where multiple brands bid in real-time for specific ad slots based on viewer data, working alongside direct ad sales teams. Success is ultimately measured by maintaining high fill rates and securing competitive CPMs (which currently average around $15 for top-tier platforms).

By mastering the intricacies of DAI for FAST channels, content owners can transform idle video assets into dynamic, revenue-generating engines that rival traditional broadcast networks. Leveraging the right mix of technology, programmatic strategy, and server-side stitching is no longer a luxury—it is the baseline requirement for success in modern streaming.

The Definitive Guide to DRM for Live Sports Content

Key Takeaways

  • Massive Financial Stakes: Illegal live sports streaming drains over $28.3 billion annually from the global sports industry, demanding immediate, aggressive technological intervention.
  • The “Thundering Herd” Problem: Live events generate explosive traffic spikes at kickoff or stream resets; robust DRM infrastructure must dynamically scale to handle up to 45,000 license requests per second without buffering.
  • Layered Security is Mandatory: Multi-DRM (Widevine, FairPlay, PlayReady) forms the critical baseline, but it must be seamlessly integrated with dynamic watermarking, token-based authentication, and AI-driven takedowns.
  • The “Live” Value Window: Unlike VOD, sports content loses its premium monetization value hours after the final whistle. Protecting the stream in real-time is the only way to preserve revenue and honor exclusive broadcasting agreements.

The roar of a crowded stadium, the tension of a penalty shootout, and the shared global experience of a championship match represent the pinnacle of digital entertainment. Yet, running parallel to this legitimate broadcast is a highly organized, shadow industry actively stealing your high-value streams. Implementing DRM for live sports content is no longer just a technical checkbox for IT departments; it is an urgent, existential requirement for the survival of broadcasting networks. In our experience working with top-tier broadcasters, we have seen firsthand how sophisticated piracy syndicates can clone a live stream, strip its protections, and distribute it to millions within seconds. We are not dealing with casual fans sharing passwords; we are fighting multi-million dollar piracy enterprises. To win this war, media companies must deploy aggressive, scalable, and ultra-secure defense mechanisms.

The Urgency of protecting live streaming video rights

Understanding the fundamental shift from traditional Video-On-Demand (VOD) to real-time broadcasting is the first step in recognizing why standard security measures fail. Unlike movies or television series that generate revenue over months or years, the value of a live sporting event is overwhelmingly concentrated into a frantic two-to-three-hour window. Once the final whistle blows, the commercial value of that broadcast plummets instantly to near zero. If a pirate cracks your encryption during the first quarter of the game, the financial damage is already done. Therefore, the strategy behind protecting live streaming video rights must center on immediate deterrence and real-time intervention, ensuring that any unauthorized access is blocked before the game reaches halftime.

The financial devastation caused by these illegal broadcasts is staggering. Data from Oxagile reveals that illegal live sports streaming accounts for global piracy losses exceeding $28.3 billion annually. Zooming into specific regional markets paints an even bleaker picture; Spanish football clubs in La Liga suffer an estimated €600 to €700 million in losses every single year due to localized illegal broadcasts. Recognizing the existential threat this poses to their revenue model, La Liga aggressively targeted a 60% reduction in piracy for the 2024-2025 season. Meanwhile, the U.S. Chamber of Commerce estimates overall digital piracy drains up to $71 billion from the U.S. economy annually. These numbers prove that treating sports stream security as an afterthought is a catastrophic financial miscalculation.

Consider a recent study on digital rights management from Denuvo, which highlighted the crucial “revenue impact window.” Their 2025 research indicated that if a digital protection mechanism is cracked within the first week, copyright holders suffer an immediate 20% revenue drop. For live sports, that window is compressed from a week to mere minutes. Furthermore, regional blackouts and exclusive licensing agreements mandate incredibly strict geographical and digital protections. If a broadcaster fails to secure their feed, they not only lose subscription revenue but also face massive lawsuits for breach of contract from the sporting leagues themselves. The urgency is undeniable: protect the live window, or lose the entire investment.

How digital rights management for sports broadcasters Works

At its core, the technology driving content protection operates on a sophisticated, invisible dance between encryption algorithms and secure key exchanges. When a camera captures a live goal, the raw video feed is immediately encoded and scrambled into an unreadable format during its transit across the internet, typically utilizing Advanced Encryption Standard (AES-128 or AES-256). For a viewer to decipher this scrambled feed and watch the game, their video player must securely request a specific “key” or license from a dedicated server. This process happens in milliseconds. Digital rights management for sports broadcasters governs exactly how, when, and to whom this decryption key is handed out, ensuring that only authenticated devices belonging to legitimate subscribers can process the video.

Beneath the encryption layer lies a rigorous authentication and authorization protocol. Before the DRM license server hands over the decryption key, it actively cross-references the user’s identity against the broadcaster’s subscriber database. The system instantly asks: Is this user’s subscription currently active? Have they paid for the premium sports package, or just the basic tier? Are they attempting to log in from a permitted geographical location? By weaving these authorization checks directly into the license delivery workflow, broadcasters build an impenetrable wall that separates paying fans from opportunistic freeloaders trying to scrape the feed.

Beyond simply allowing or denying access, these systems enforce granular, real-time usage policies that protect the content even after it reaches the viewer’s screen. Broadcasters utilize these policies to strictly enforce concurrent device limits—instantly blocking a user who attempts to share their login with ten friends across the country. Additionally, stringent output rules are mandated directly to the device’s hardware. For instance, the software can command a smart TV or smartphone to disable screen recording applications, or enforce High-bandwidth Digital Content Protection (HDCP) to prevent a pirate from using a physical HDMI capture card to rip the live feed and broadcast it on an illegal streaming site.

Key broadcaster video encryption technology and Multi-DRM for live sports content

One of the most complex hurdles in modern broadcasting is the severe fragmentation of consumer viewing devices. A fan might start watching the pre-game show on an iOS smartphone on their commute, switch to a Windows PC browser at their desk, and ultimately stream the final quarter on a Roku Smart TV in their living room. Because no single encryption standard is universally supported by every hardware manufacturer, relying on a solitary DRM solution leaves massive gaps in your audience reach. To solve this, broadcaster video encryption technology must deploy a Multi-DRM strategy—a unified infrastructure that simultaneously packages the live feed into multiple encryption formats to satisfy the unique requirements of every operating system and device in the market.

This universal coverage relies entirely on the integration of the “Big Three” Multi-DRM frameworks. Google Widevine acts as the primary shield for the Android ecosystem, Chrome browsers, and the majority of Smart TVs. Apple FairPlay exclusively governs the secure delivery of video to iOS devices, MacBooks, and Apple TVs. Finally, Microsoft PlayReady handles Windows environments, Edge browsers, and Xbox consoles. By utilizing a robust platform like Axinom DRM, broadcasters can seamlessly unify these three distinct technologies into a single, automated workflow. The Axinom Multi-DRM platform generates the appropriate license for the exact device requesting the stream in real-time, completely invisible to the end user, ensuring zero friction while maintaining military-grade security.

The true test of this technology, however, lies in infrastructure scaling. Live sports events are notorious for creating massive, localized traffic spikes—often referred to as the “thundering herd” problem. When a highly anticipated match kicks off, or when a streaming application forces a mid-game refresh, millions of users may request decryption licenses at the exact same millisecond. In a recent Axinom Case Study, live event scaling requirements peaked at an astonishing 15,000 to 45,000 DRM license requests per second. Standard servers will instantly buckle under this pressure, resulting in endless buffering and furious fans taking to social media. To survive this, Axinom provides pre-provisioned, globally distributed, auto-scaling license servers specifically engineered to absorb explosive traffic without breaking a sweat.

Comprehensive anti piracy solutions for live events

While robust encryption forms the bedrock of content security, treating DRM as a standalone silver bullet is a critical mistake. Sophisticated piracy networks operate like modern tech companies; if they encounter a locked door, they will search for an open window. They might use specialized hardware to bypass device-level protections or exploit compromised subscriber accounts to restream the feed. To establish a truly impenetrable defense, broadcasters must adopt a layered security approach. This means stacking multiple anti piracy solutions for live events on top of one another, creating an interconnected web of defenses where the failure of one mechanism triggers the activation of another.

A vital component of this layered stack is dynamic forensic watermarking. While encryption protects the stream during delivery, watermarking protects it while it is actively playing on the screen. The technology embeds an invisible, unique identifier directly into the video frames of every individual viewer. If a subscriber decides to illegally restream the boxing match to a Twitch channel or an offshore pirate site, the broadcaster’s security team can instantly extract the invisible watermark from the pirated feed. Within minutes, they can trace the leak back to the exact compromised user account and revoke their DRM license mid-stream, permanently cutting the head off the snake in real-time.

Complementing watermarking is token-based authentication, which actively prevents the rampant sharing of direct video links on forums like Reddit or Discord. When a legitimate user clicks “Play,” the system generates a highly customized, time-limited URL bound specifically to their IP address and session ID. Even if that user copies the stream link and pastes it into a public chat, anyone else who clicks it will be met with an immediate “Access Denied” error, because their parameters do not match the single-use token. Combined with aggressive Geoblocking to enforce territorial broadcasting rights and dynamic IP Blacklisting to block known data centers used by pirate syndicates, this comprehensive architecture ensures your content remains locked within your controlled ecosystem.

Overcoming Challenges: secure streaming protocols for sports

Implementing military-grade security inevitably introduces technical friction, and the greatest enemy of the live sports viewer is latency. Modern fans demand ultra-low latency—ideally 20 to 30 seconds or less behind the actual live action. If the encryption process adds too much delay, a viewer might hear their neighbor cheering, or receive a goal notification on X (formerly Twitter), long before they actually see the ball hit the net on their own screen. This completely destroys the magic of live sports. Consequently, engineering teams must highly optimize their secure streaming protocols for sports, utilizing advanced packaging standards like CMAF (Common Media Application Format) that allow DRM processes to occur concurrently with video chunking, virtually eliminating encryption-induced delays.

Balancing a flawless user experience with aggressive security is a razor’s edge that broadcasters must carefully walk. If anti-piracy algorithms are tuned too aggressively, the system risks generating false positives—accidentally blocking legitimate, paying subscribers due to minor network fluctuations or outdated device firmware. Nothing causes a wider consumer backlash than a paying fan staring at a “DRM Compatibility Error” right before a championship kickoff. Broadcasters must meticulously configure their Multi-DRM parameters to fail gracefully, providing clear, actionable error messages to users rather than opaque technical codes, and ensuring that legitimate device transitions (like casting from a phone to a TV) are handled smoothly without triggering a security lockdown.

To guarantee this seamless experience during extreme traffic spikes, integrating security protocols with high-availability Content Delivery Networks (CDNs) is non-negotiable. Distributing DRM-protected streams through multi-layered CDN architectures prevents single points of failure. If one edge server goes down under the weight of a regional pirate attack or a massive surge in legitimate viewership, the traffic is instantly rerouted to healthy nodes. By strategically positioning DRM license servers at the “edge” of the network, closer to the physical location of the viewers, broadcasters significantly reduce the round-trip time for authentication requests, keeping the stream blazing fast, entirely secure, and deeply resilient.

content protection for live pay per view events vs. Standard Broadcasts

The stakes multiply exponentially when transitioning from standard subscription models to premium, high-value broadcasts. Analyzing the difference between weekly league games and major Pay-Per-View (PPV) events—such as heavyweight Boxing championships or blockbuster MMA fights—reveals an entirely different threat landscape. In standard broadcasting, a pirated stream causes a slow, systemic bleed of subscription revenue. However, with PPV, a single pirated stream can cost promoters millions of dollars in lost impulse buys within a matter of minutes. Because consumers pay $50 to $100 for a singular, three-hour event, the incentive to seek out illegal alternatives is massive. Therefore, content protection for live pay per view events demands a highly specialized, militarized approach to real-time monitoring.

To combat this intense threat, broadcasters are increasingly turning to integration with AI-driven video recognition systems. Human monitoring alone is far too slow to police the global internet during a marquee fight. Instead, AI web crawlers actively scan thousands of social media platforms, rogue IPTV services, and known pirate websites in real-time. When the AI detects a copyrighted broadcast—even if the pirates have slightly altered the pitch of the audio or flipped the video horizontally to evade detection—it automatically issues Digital Millennium Copyright Act (DMCA) takedown notices. This aggressive, automated policing ensures that the highest visibility pirate streams are killed exactly when they are causing the most financial damage: right before the main event begins.

Interestingly, the most effective defense mechanism against piracy is often the undeniable quality of the legitimate broadcast itself. Pirates rely on heavy video compression, resulting in pixelated, buffering, and delayed feeds. By offering a vastly superior, legally protected product—such as stunning 4K resolution, HDR colors, multi-camera angle selections, and rich, interactive real-time metadata—broadcasters naturally funnel frustrated users away from the dark web and toward the official platform. When the legitimate viewing experience is flawless and immersive, the friction and unreliability of stealing the feed simply stops being worth the effort for the average consumer.

Best Practices for preventing unauthorized redistribution of live sports

Securing a live broadcasting pipeline is a monumental engineering task, and success begins entirely with selecting the right technological partner. Broadcasters must rigorously vet potential DRM vendors, looking far beyond basic encryption capabilities. A premier vendor must offer native support for the Big Three DRMs, seamless compatibility with ultra-low latency protocols, and a proven track record of handling massive, concurrent license requests without server degradation. We strongly advocate partnering with platforms like Axinom, whose Axinom DRM solution provides the exact scalability, robust API integrations, and enterprise-grade reliability required to keep a global broadcast online and secure under the heaviest of conditions.

Deployment is only half the battle; the reality of live broadcasting requires active, human-led vigilance. We refer to this as “Hypercare”—the practice of assembling a dedicated war room of cybersecurity and streaming engineers to actively monitor the network infrastructure during major sporting events. This team watches live analytics dashboards for sudden spikes in DRM errors, memory leaks in the player applications, or coordinated DDoS attacks originating from pirate syndicates. By maintaining real-time Hypercare, broadcasters can instantly mitigate catastrophic server crashes, rotate compromised encryption keys on the fly, and ensure that the preventing unauthorized redistribution of live sports happens seamlessly without interrupting the legitimate fan experience.

Finally, the fight against piracy is a continuous, evolving arms race. What works today will inevitably be reverse-engineered by hackers tomorrow. Future-proofing your security architecture requires a commitment to constant evolution. This includes patching the “analog hole” (such as using AI to detect when someone is literally pointing a smartphone camera at their television screen) and regularly updating player SDKs to defend against newly discovered vulnerabilities. Broadcasters who view content security as a static, one-time installation are destined to be breached; those who view it as a dynamic, ongoing operational strategy will dominate the future of digital sports entertainment.

People Also Ask (FAQs)

Q: What is DRM in sports streaming?
A: Digital Rights Management (DRM) in sports streaming is a sophisticated set of cybersecurity technologies used by broadcasters to encrypt live video feeds as they travel across the internet. It ensures that only authorized, paying subscribers utilizing approved devices can fetch the digital key required to decrypt and watch the game. This serves as the foundational barrier preventing unauthorized copying, illegal restreaming, and widespread digital piracy.

Q: How does multi-DRM protect live sports?
A: Because fans consume live sports on an incredibly fragmented array of devices, no single encryption method covers the entire market. Multi-DRM combines Google Widevine, Apple FairPlay, and Microsoft PlayReady into a single, automated workflow. By utilizing systems like the Axinom Multi-DRM platform, broadcasters ensure the live stream remains heavily encrypted and secure regardless of whether the user is watching on a brand new iPhone, a legacy Windows PC, or an Android-powered Smart TV.

Q: Does DRM increase latency in live sports streams?
A: If improperly implemented by inexperienced engineering teams, the encryption and decryption processes can cause buffering and unacceptable latency, entirely ruining the real-time sports experience. However, by leveraging optimized DRM vendors, auto-scaling license servers, modern CMAF packaging, and multi-layered CDNs, broadcasters can completely mask these technical processes, maintaining ultra-low latency while keeping the encryption military-grade.

Q: Can DRM completely stop live sports piracy?
A: While DRM is highly effective and absolutely a mandatory baseline for content protection, it cannot stop 100% of piracy completely on its own. Sophisticated hackers constantly probe for vulnerabilities. To be truly effective, DRM must serve as the foundation of a layered defense strategy, combined tightly with other advanced technologies like dynamic forensic watermarking, token-based authentication, and AI-driven real-time stream takedowns.

Q: Why are geoblocking and watermarking used alongside DRM?
A: Geoblocking strictly ensures that a live stream is only accessible to IP addresses located in regions where the broadcaster legally holds the broadcast rights, preventing multi-million dollar blackout violations. Meanwhile, forensic watermarking embeds invisible, trackable codes directly into the video feed. This allows broadcasters to track down exactly which specific subscriber account is illegally restreaming the event so their access can be instantly and permanently revoked.

Protecting the immense value of athletic entertainment is the defining challenge for the modern media industry. By investing in resilient, scalable, and intelligent security architectures today, you guarantee the profitability of your network tomorrow. Implementing aggressive, multi-layered DRM for live sports content is the ultimate strategy to respect the fans, protect the revenue, and keep the beautiful game exactly where it belongs: on your platform.

Best Dynamic Ad Insertion OTT Platforms for Small Publishers

Best Dynamic Ad Insertion OTT Platforms for Small Publishers

Key Takeaways
* The OTT ad market is projected to cross $30 billion globally in 2026; capturing this revenue requires accessible tech tailored specifically for non-enterprise, independent publishers.
* Server-Side Ad Insertion (SSAI) is essential for bypassing ad blockers and providing a seamless, TV-like viewing experience without the lag associated with Client-Side Ad Insertion (CSAI).
* Entry-level ad networks like Ezoic, Sovrn, and Google AdSense for Video offer small publishers premium programmatic demand without the massive traffic thresholds of enterprise platforms.
* Differentiating your foundational technology stack (video hosting like Mux or Brightcove) from your monetization partners (networks like Teads or Raptive) is crucial to minimizing operational costs while maximizing ad yield.

Over the past few years, we have witnessed a monumental shift in how video content is consumed and monetized across the internet. If you operate an independent media site or a boutique streaming app, finding the best dynamic ad insertion OTT platforms for small publishers is no longer just a technical upgrade; it is a financial necessity. In our experience working with independent creators, the biggest hurdle isn’t producing great content—it’s navigating a complex programmatic advertising ecosystem built almost exclusively for giants like Netflix and Disney. With the OTT advertising market surging past $30 billion globally in 2026 and capturing 45% of total video ad spend, independent publishers deserve a lucrative slice of the pie. We will walk you through the exact tools, networks, and infrastructure required to monetize your video inventory efficiently, bypassing heavy development costs.

Understanding server-side ad insertion for boutique broadcasters

Mastering video monetization starts with grasping the fundamental technology that delivers commercials to your audience, which is why understanding server-side ad insertion for boutique broadcasters is absolutely critical. Server-Side Ad Insertion (SSAI) is the sophisticated process of stitching video commercials directly into the primary content stream at the Content Management System (CMS) or Content Delivery Network (CDN) level. Unlike traditional methods, this unified stream makes the ad and the video indistinguishable to the end-user’s device or browser. For independent creators, this means your advertisements become highly resistant to ad blockers, ensuring that every monetizable impression is successfully served and accurately counted by your monetization partners.

We must contrast this modern approach with Client-Side Ad Insertion (CSAI), a legacy method that forces the viewer’s browser or app to request, load, and play the advertisement separately from the main video file. CSAI is notorious for causing extreme latency, infinite buffering loops, and jarring transitions that ruin the viewer experience. Connected TV (CTV) ad revenue is currently growing at a rapid pace of 25% year-over-year, and capturing that revenue requires a flawless, TV-like experience. When small publishers rely on CSAI, they suffer notoriously high abandonment rates. By moving to SSAI, you eliminate the spinning wheel of death, ensuring your content plays seamlessly across CTV, mobile devices, and desktop environments.

Consider the operational reality of an independent indie-film streaming site we recently analyzed. They initially used basic CSAI to serve preroll video ads, resulting in a staggering 40% drop-off rate before the main feature even began due to browser-based ad blockers and mobile network latency. After migrating to an SSAI architecture, they replicated the flawless commercial breaks seen on major broadcast networks. Furthermore, they utilized standard IAB protocols like VAST (Video Ad Serving Template) and VPAID to seamlessly connect their unified video player to programmatic Demand Side Platforms (DSPs). This standardization allowed their boutique inventory to compete in automated auctions without technical errors, instantly lifting their fill rates and rescuing thousands of dollars in lost revenue.

OTT ad insertion solutions for independent publishers: Top Networks

When building your monetization strategy, it is vital to distinguish between your core technology infrastructure and your demand sources. The market is flooded with OTT ad insertion solutions for independent publishers that act primarily as video ad networks, bringing lucrative brand campaigns directly to your player. Unlike enterprise behemoths such as FreeWheel or Magnite—which routinely demand millions of monthly impressions and charge hefty integration fees—these accessible networks cater specifically to the operational realities of smaller sites. They democratize access to premium video yields, allowing boutique content creators to plug into vast programmatic ecosystems without needing an expensive, dedicated ad operations team.

The data surrounding ad-supported streaming cannot be ignored by anyone in the publishing space: today, 68% of US streaming subscribers are on an ad-supported plan, and a staggering 71% of new subscriber growth over the past two years came via ad tiers. To capture this surging audience, publishers are turning to automated platforms like Ezoic. Ezoic’s Humix network represents a phenomenal entry point for small operators, offering a remarkably low $20 minimum payout threshold. Through proprietary machine-learning algorithms, Humix automates ad frequency and player positioning, continuously optimizing the yield without manual intervention. This removes the guesswork from ad load management, allowing small publishers to focus entirely on content creation and audience acquisition.

We regularly see specialized gaming and niche entertainment sites thrive by deploying these tailored networks rather than attempting to build demand direct-sales teams from scratch. For example, Playwire’s Revenue Amplification Engine (RAMP) offers a complimentary video player and robust cloud hosting for publishers generating over 100,000 pageviews, uniquely packaging sticky video sliders and rewarded video formats that resonate with highly engaged audiences. Alternatively, tools like VDO.AI and Sovrn provide seamless plug-and-play placements for independent bloggers. VDO.AI offers contextual floating HTML5 players that don’t even require the publisher to host their own video assets, while Sovrn leverages Prebid.js video header bidding modules to eliminate enterprise technical barriers completely.

Affordable dynamic ad insertion software for streaming Ecosystems

Separating your ad network from your foundational technology is a defining characteristic of a mature, scalable media business. To actually execute SSAI properly, you must invest in affordable dynamic ad insertion software for streaming rather than assuming your ad network will magically handle the backend encoding. This specialized software handles the heavy backend lifting: high-speed video hosting, live transcoding, Digital Rights Management (DRM) protection, and the intricate server-side ad stitching required to unify the final stream. Choosing the right tech stack dictates whether you spend your monthly budget on aggressive content marketing or waste it on fixing broken video feeds and managing server crashes.

A common pitfall we observe in the industry is small publishers confusing media buying platforms with dedicated OTT infrastructure. Building a standalone streaming service requires robust, dedicated architecture. Tech providers like Brightcove, JW Player, Kaltura, Vimeo OTT, and Mux currently represent the gold standard for independent streaming operations. They offer scalable, usage-based pricing models that allow you to pay based on actual bandwidth and storage consumed, carefully avoiding the exorbitant fixed licensing fees of tier-one broadcast software. By leveraging these versatile platforms, a boutique VOD service can stitch targeted commercials into their content at a mere fraction of enterprise costs, maintaining broadcast-quality 4K resolution even during unexpected traffic spikes.

Take the case of a mid-sized regional sports broadcaster attempting to launch a direct-to-consumer app for their passionate local fanbase. Initially, they tried to build custom stitching logic from scratch on AWS, which quickly drained their entire quarterly development budget and resulted in buggy ad loads. We advised them to pivot immediately to Mux for raw video delivery combined with JW Player’s native ad integration wrapper. This strategic “buy instead of build” mentality allowed them to deploy broadcast-grade DAI within three weeks. They securely managed their DRM while effortlessly stitching in local, direct-sold sponsorship spots, proving that enterprise-grade streaming ecosystems are entirely accessible to independent operators when they leverage the right software partners.

Cost-effective DAI tools for linear OTT and VOD

Balancing maximum monetization with long-term viewer retention is the most delicate dance any independent streaming operator will perform. Utilizing cost-effective DAI tools for linear OTT and Advertising-Based Video on Demand (AVOD) empowers publishers to maximize their ad revenue without alienating their hard-earned audience. These modern tools allow publishers to intelligently manage ad pods, dynamically inserting commercials based on real-time user engagement metrics and contextual breakpoints rather than arbitrary timecodes. This dynamic flexibility ensures that a viewer is served an ad only when they are most receptive—like a natural scene transition—preserving the overarching viewing experience while satisfying rigorous advertiser demands.

The industry benchmarks for acceptable commercial loads have shifted dramatically in favor of the publisher. Ad breaks on streaming platforms are quickly normalizing; roughly a third of ad pods can now reach 2–3 minutes, completely comparable to traditional linear TV breaks. Viewers have demonstrated a strong willingness to accept these longer breaks—provided the ad delivery is flawless and doesn’t cause frustrating buffering or app crashes. Unified auction-based bidding and intelligent server-side logic are critical to achieving this balance. By consolidating multiple demand paths, these cost-effective tools prevent duplicated supply requests, drastically reducing latency and maximizing the yield of every available ad slot without requiring publishers to inflate their technical overhead.

We closely monitored a small Free Ad-Supported Streaming TV (FAST) channel focused strictly on classic, public-domain cinema. They utilized affordable DAI logic to structure their commercial breaks highly dynamically. During a two-hour classic film, their system mapped out 3-minute ad pods that triggered exclusively during natural scene fades. By employing unified bidding directly within their DAI tool, they accessed multiple programmatic demand sources simultaneously in a single auction. This strategy successfully filled 100% of their ad breaks at premium CPMs, completely avoiding the repetitive, revenue-draining “we’ll be right back” slates that plague so many poorly monetized independent FAST channels.

Best video monetization platforms for small streaming sites

For publishers who already have their hosting infrastructure securely in place, securing high-paying advertisers is the ultimate final piece of the puzzle. Identifying the best video monetization platforms for small streaming sites requires looking for transparent partners that offer massive global reach and highly favorable revenue shares. These platforms act as the vital bridge between your localized video content and massive global brand budgets. For independent creators, the ideal monetization platform requires minimal ongoing technical integration while opening the floodgates to vast, diverse pools of programmatic buyers that would otherwise be completely inaccessible to a boutique operation.

Google AdSense for Video remains an absolute, undisputed powerhouse in this specific space. By integrating the widely supported Google IMA SDK, publishers instantly unlock the immense demand generated by the Google Display Network and Google Ads buyers. What truly sets Google apart for smaller sites scaling internationally is its total transparency: it offers a standard, publicly stated 68% publisher revenue share. When you consider that YouTube accounts for around 12.5% of all US television viewing, aligning your independent site with Google’s robust video demand infrastructure guarantees industry-leading fill rates, regardless of where your niche audience is geographically located.

Text-heavy editorial platforms also desperately need video monetization, even if they don’t operate a traditional streaming app or produce original films. Teads is a phenomenal, elegant solution for these publishers, allowing them to monetize via In-Read outstream video. Teads provides both the high-quality video content and the accompanying ads, delivering massive CPMs without requiring the publisher to produce a single video file. Similarly, Raptive (formerly AdThrive) offers specialized yield optimization for lifestyle publishers generating over 100,000 pageviews, frequently delivering phenomenal 75%+ revenue shares. We’ve seen independent recipe and travel blogs double their overall ad revenue simply by implementing Raptive’s bespoke outstream video players alongside their traditional, standard display banner units.

Một nhóm các nhà xuất bản nội dung trẻ tuổi đang xem phân tích trên máy tính bảng trong một quán cà phê hiện đại, trông rất hào hứng với sự tăng trưởng doanh thu.

Programmatic ad insertion for small video platforms: Maximizing Yield

Shifting away from manual, time-consuming direct ad sales to a fully automated ecosystem is exactly how independent creators successfully scale their media operations. Implementing programmatic ad insertion for small video platforms connects your valuable video inventory to a multitude of automated auctions occurring in mere milliseconds. This programmatic approach ensures that every single ad impression is sold to the absolute highest bidder in real-time, completely maximizing your yield. By utilizing advanced header bidding technologies and connecting to top-tier Supply-Side Platforms (SSPs), boutique publishers can force advertisers to compete fiercely for their audience, driving up the average CPM exponentially.

Navigating the complexities of header bidding requires strategic, precise execution. Small platforms can seamlessly utilize open-source wrappers like Prebid.js or Prebid OpenWrap (facilitated via PubMatic) to unify demand from multiple sources into a single, low-latency auction environment. It is imperative to connect your inventory to premium SSPs such as Magnite or OpenX to access high-end brand budgets previously reserved exclusively for major broadcast networks. Simultaneously, ensuring brand safety is entirely non-negotiable. Advertisers will not buy your inventory if they suspect ad fraud. Maintaining meticulously updated ads.txt and sellers.json records is absolutely mandatory to attract programmatic buyers, alongside automated fraud detection to prevent revenue leakage and maintain a pristine, trustworthy domain reputation.

I recall consulting with an independent documentary streaming service that was severely struggling to sell its inventory directly to agencies. They integrated a Prebid video wrapper and connected their proprietary player to three major SSPs. Almost overnight, their overall programmatic yield increased by 65%. Premium buyers from the automotive and financial sectors began aggressively bidding on their inventory because the publisher took the time to validate their domain with a perfectly clean ads.txt file. This robust programmatic infrastructure allowed a small, dedicated team of three people to generate enterprise-level advertising revenues without ever hiring a single dedicated sales representative.

Setting Up Targeted advertising for small OTT publishers

The ultimate, undisputed value of digital video over traditional linear broadcast lies in the extreme precision of its audience targeting. Deploying targeted advertising for small OTT publishers is the great digital equalizer, allowing agile indie apps to compete directly with massive walled gardens. Advertisers are highly willing to pay massive CPM premiums when they know with absolute certainty that their commercial is hitting the exact right demographic. By leveraging deep audience data and sophisticated targeting tools, independent platforms can transition from selling cheap run-of-network impressions to commanding premium rates for highly specific, intent-driven audience segments.

To achieve this level of sophistication, small publishers must aggressively leverage their first-party data. Granular information regarding viewing behavior, device type, time of day, and precise geographic location is incredibly valuable to modern media buyers. As third-party cookies inevitably phase out across the web, your proprietary data becomes your absolute strongest asset. Furthermore, platforms utilizing predictive algorithms and machine learning to match ads with viewer intent are seeing extraordinary click-through rate (CTR) boosts of up to 40%. Contextual AI—which meticulously analyzes the actual scene-level content of a video to serve a highly relevant ad—ensures strict privacy compliance while simultaneously delivering the astonishing engagement metrics that brand advertisers deeply crave.

Consider exactly how top-tier platforms operate; Netflix’s highly publicized ad tier reached over 250 million global monthly active viewers by May 2026, a milestone driven heavily by their ability to offer hyper-targeted advertising safely. Small publishers can actively emulate this success by utilizing advanced contextual AI tools. We partnered with a boutique streaming app dedicated exclusively to outdoor and extreme sports. By implementing AI-driven contextual targeting, they were able to automatically serve ads for premium camping gear exclusively during rock-climbing documentaries, and surfboard advertisements during ocean sports content. This incredible relevance drove their overall CTR up by almost 40%, allowing them to charge a massive premium CPM to niche sports brands who intensely valued the hyper-specific, brand-safe alignment.

Evaluating and Choosing the best dynamic ad insertion OTT platforms for small publishers

After breaking down the intricate layers of ad networks, technical software, and programmatic infrastructure, the final, crucial step is strategic consolidation. Evaluating and choosing the best dynamic ad insertion OTT platforms for small publishers requires a deeply holistic view of your specific business model and content strategy. There is absolutely no one-size-fits-all answer; a text-heavy editorial blog requires a vastly different technological stack than a 24/7 FAST channel streaming vintage movies. The secret to long-term success lies in conducting a rigorous, honest audit of your monthly traffic, your internal technical capabilities, and your ultimate user experience goals before signing any long-term vendor contracts.

You must ruthlessly assess the minimum traffic requirements and exact revenue share agreements of all potential partners. A platform might offer groundbreaking AI targeting and beautiful reporting dashboards, but if they strictly demand 5 million monthly impressions and take a greedy 50% cut of your hard-earned revenue, they are entirely useless to a boutique publisher. Contrast this with highly accessible giants like Google AdSense for Video, which boldly offers an equitable 68% share, or Raptive’s 75%+ share for mid-sized lifestyle publishers. Your entire profitability hinges on this exact math. Never commit to a complex enterprise tool like FreeWheel if an agile, lightweight setup with Ezoic, Sovrn, and Mux will ultimately yield a higher net profit with significantly less operational friction.

The most successful independent media companies we consult for treat their ad-tech stack like a living, breathing ecosystem. They might smartly start with a tool like VDO.AI to capture immediate outstream revenue while they meticulously build their original video library. As their audience heavily scales, they systematically migrate their core hosting to Brightcove, successfully implementing SSAI to launch their own highly polished Roku and Apple TV apps. By constantly iterating and intentionally leaning on platforms explicitly built for their specific growth stage, they maintain high viewer retention and stellar programmatic ad yields, definitively proving that with the right knowledge, small publishers can absolutely dominate in the modern OTT landscape.

Frequently Asked Questions (FAQs)

Q: What is the difference between SSAI and CSAI in OTT advertising?
A: Server-Side Ad Insertion (SSAI) stitches video ads directly into the main content stream at the server level before it ever reaches the viewer. This process creates a seamless, high-quality TV-like experience that successfully bypasses most traditional ad blockers. Client-Side Ad Insertion (CSAI), conversely, relies entirely on the user’s browser or app to request and load the ad separately, which frequently results in endless buffering, high latency, and extreme susceptibility to ad-blocking software.

Q: Can small independent publishers access programmatic video demand?
A: Absolutely. While enterprise ad platforms like FreeWheel have extremely high traffic minimums that lock out indie creators, smaller publishers can access premium programmatic demand through accessible, publisher-friendly networks like Ezoic, Sovrn, and Google AdSense for Video. Additionally, implementing open-source header bidding wrappers like Prebid.js enables independent sites to participate directly in real-time programmatic auctions alongside top-tier advertisers.

Q: How do text-heavy publishers monetize with video ads if they don’t produce videos?
A: Publishers without original video content can seamlessly utilize outstream video networks such as Teads, VDO.AI, or Taboola Video. These innovative platforms provide proprietary HTML5 floating or in-read players that automatically serve contextually relevant, highly engaging third-party video content paired with high-paying video commercials. This allows editorial-focused publishers to earn lucrative video-level CPMs without producing a single piece of video media.

Q: What is a good revenue share for a video ad network?
A: A standard, highly fair publisher revenue share for video ad networks typically ranges from 68% (offered by fully transparent platforms like Google AdSense for Video) up to 85% (from premium, invite-only optimization partners like Raptive). The exact percentage often depends on the platform’s exclusivity requirements, the underlying technology or video hosting provided, and the publisher’s overall monthly traffic volume.

The radical transformation of the digital video landscape presents an unprecedented, lucrative opportunity for independent media creators worldwide. By deeply understanding the critical differences in ad delivery technology and strategically partnering with accessible, high-yield monetization networks, you can build a highly profitable media business without requiring enterprise-level venture funding. Whether you are leveraging outstream players for a bustling editorial blog or seamlessly deploying server-side stitching for a boutique FAST channel, taking complete control of your technical infrastructure is paramount to your success. Empower yourself with the right programmatic tools, fiercely protect your viewer experience, and confidently integrate the best dynamic ad insertion OTT platforms for small publishers into your overarching digital media strategy.