Your cost effective OTT ad server with dynamic ad insertion

Key Takeaways
* Transforming video streaming from a massive cost center into a sustainable profit center requires a strategic shift toward server-side ad stitching to bypass ad blockers and maximize ARPU.
* Understanding core technologies like SCTE-104/35 markers and real-time transcoding is critical for delivering buffer-free, broadcast-quality experiences on budget constraints.
* While enterprise giants like AWS and Google dominate the conversation, agile platforms like Akta offer the essential on-the-fly transcoding and manifest manipulation tailored for mid-tier publishers without exorbitant engineering costs.
* Transparent pricing models—ranging from flat SaaS fees to CPM-based insertion structures—are vital for independent FAST channels aiming to offset ad server costs through programmatic demand.

In our experience working directly with independent broadcasters, local news networks, and mid-tier streaming publishers, the barrier to entry for enterprise-grade video monetization has always been price. You have the traffic, the premium content, and a highly engaged audience, but every time you attempt to monetize through seamless, television-like commercial breaks, the technical bills completely devour your margins. If you are searching for a cost effective OTT ad server with dynamic ad insertion, you are likely exhausted by the dizzying complexity and hidden fees associated with legacy tech giants. We are here to dismantle the jargon. This guide will walk you through exactly how to build a broadcast-grade, hyper-targeted video ad stack without requiring a massive engineering team or an endless enterprise budget.

Understanding the Need for an affordable OTT ad insertion platform

We have watched the streaming industry rapidly shift its primary mandate over the past two years: platforms can no longer operate as endless “cost centers” focused purely on user acquisition. Today, every independent FAST (Free Ad-Supported Streaming TV) channel and AVOD (Advertising-based Video on Demand) application must pivot to becoming a strict profit center. The core objective is maximizing ARPU (Average Revenue Per User) without alienating viewers through disruptive, highly repetitive, or broken advertising experiences. To achieve this delicate balance, independent publishers urgently need infrastructure that delivers premium monetization at a fraction of enterprise costs.

The data surrounding this market explosion is impossible to ignore. For instance, AWS reported that online viewership for Super Bowl LV experienced a massive increase of over 65% compared to the previous year, highlighting an unprecedented explosion in live streaming adoption globally. Furthermore, eMarketer data indicates that U.S. advertisers increased their spending on digital ads by almost 15% in a single year, with digital formats projecting to surpass two-thirds of the overall U.S. ad market. This massive migration of ad dollars means that even niche broadcasters are sitting on a goldmine of inventory, provided they have the right technology to capture it.

Consumers are currently suffering from severe subscription fatigue. As viewers heavily resist paying out-of-pocket for yet another monthly SVOD service, they are flocking to AVOD and FAST channels in record numbers. I frequently see mid-sized regional networks capitalizing on this trend by reviving archival content and local news broadcasts into 24/7 linear digital streams. However, without a dedicated system to monetize these streams, they leave thousands of dollars on the table daily. They require a lightweight, robust platform to capitalize on this shifting viewer sentiment before their larger competitors dominate the ad supply.

Furthermore, the era of blanket advertising is entirely dead. Modern media buyers demand hyper-localized, data-driven advertising that ensures higher conversions. For emerging markets and mid-tier apps, deploying localized campaigns is what separates a thriving channel from a dead one. Integrating an affordable OTT ad insertion platform allows these nimble organizations to segment their audiences by geography, device, and behavioral data, offering high-CPM targeted inventory to programmatic buyers without draining their operational budgets.

Core Mechanics of a cost efficient server side ad insertion SSAI Setup

If you have ever watched a live stream only to be interrupted by a spinning wheel of death right as a commercial break begins, you have witnessed the fatal flaw of legacy client-side ad insertion (CSAI). Server-Side Ad Insertion (SSAI) completely eliminates this “buffering death” by stitching the advertisement directly into the video stream at the server level, long before it ever reaches the viewer’s screen. This creates a beautifully seamless, traditional TV-like experience. For publishers on a budget, executing this flawlessly is paramount, as buffering immediately causes viewer abandonment and tanked completion rates.

To truly understand how this works, we must break down the three fundamental pillars of Dynamic Ad Insertion (DAI), a methodology pioneered by tech leaders like Google. First is Ad Pod Building, which involves receiving multiple ad creatives from various demand sources and unifying them into a single commercial break. Second is Creative Conditioning, which requires transcoding those video creatives in advance so their audio levels, resolution, and bitrates perfectly match the primary content. Finally, Manifest Manipulation is the actual stitching process where the customized ad playlist is seamlessly injected into the HLS or DASH stream sent to the user.

The precision of this stitching relies entirely on industry-standard triggers known as SCTE markers. In our deployments, we heavily utilize SCTE-104 markers for uncompressed raw video feeds directly from the broadcast studio, and SCTE-35 markers for compressed feeds traversing the cloud. These digital cues tell the ad server the exact millisecond an ad break begins and exactly how long it lasts. Understanding and utilizing these markers correctly is what prevents commercials from awkwardly cutting off a live sports play or local news segment.

Perhaps the most financially lucrative mechanic of SSAI is its inherent ability to bypass ad blockers. Because server-side stitching pushes all the business logic and ad calls to the cloud infrastructure rather than the user’s browser or device, client-side ad blockers cannot distinguish between the primary video content and the commercial. By implementing a cost efficient server side ad insertion SSAI setup, we have seen independent publishers immediately reclaim 15% to 20% of their previously blocked revenue overnight, rapidly offsetting any minimal infrastructure costs.

Key Features to Look for in a budget friendly video ad server for streaming

When evaluating infrastructure, the most critical feature to demand is on-the-fly ad transcoding. In real-world programmatic environments, third-party DSPs (Demand-Side Platforms) will frequently send ad creatives in wildly different formats, resolutions, and bitrates. If an ad is served in a format the user’s device cannot support, the player crashes. Platforms like Akta have masterfully solved this by identifying mismatches between third-party ads and device capabilities instantly, converting video formats in real-time. This ensures high-quality user experiences without requiring publishers to build expensive, proprietary transcoding farms.

Equally vital is absolute VAST (Video Ad Serving Template) compatibility. As a growing publisher, the last thing you want is to rip and replace your entire existing ad operations workflow. A truly accessible system must plug directly into your current ecosystem. By choosing a server that works seamlessly with your existing VAST-compliant third-party ad servers, you maintain your direct sales relationships and current programmatic demand partners. It turns complex integration into a plug-and-play scenario, keeping engineering costs drastically low.

You simply cannot manage what you cannot measure, making real-time analytics and viewability tracking a non-negotiable feature. Media buyers will not pay premium CPMs for your inventory unless they have absolute confidence that their ads were actually seen. Look for platforms capable of providing MRC-accredited impression tracking, detailed completion rates, and click-through metrics. Google Ad Manager’s DAI, for example, was notably the first SSAI solution to be accredited by the Media Rating Council (MRC) for client-initiated impression measurement on live and VOD content, setting the industry benchmark that all budget platforms now strive to match.

Finally, do not overlook the necessity for advanced sponsorship and linear scheduling controls. While programmatic backfill is great, the real money in streaming often comes from direct sponsorships during high-profile live events, such as local high school football championships or regional election coverage. A highly functional, budget friendly video ad server for streaming will give your ad-ops team fine-tuned control over specific ad units and pods, allowing them to dictate exactly which sponsor appears at which moment, flawlessly mimicking traditional broadcast-style linear ad scheduling.

Top Providers: Finding a cost effective OTT ad server with dynamic ad insertion

When navigating the market, the default path for many engineers is the AWS Media Services Stack. Leveraging AWS Elemental MediaTailor for manifest manipulation, alongside MediaLive and MediaConnect, provides an incredibly robust architecture. However, in our hands-on experience, while AWS offers phenomenal scalability for growing audiences, its complex pricing based on per-thousand ad insertions and transcoding minutes can spiral out of control for smaller publishers. It is a brilliant, highly reliable ecosystem, but it demands serious AWS architectural expertise to keep costs contained and optimized.

Conversely, Google Ad Manager offers a massive gravitational pull due to its vast programmatic demand marketplace. Broadcasters generally have two integration options: a full end-to-end DAI integration, or DAI Pod Serving, which is more flexible as it integrates seamlessly into a publisher’s existing third-party streaming solution. While Google’s technology is world-class and carries the aforementioned MRC accreditation, its platform is notoriously engineered for massive Tier-1 broadcasters like CBS or Fox. Mid-market publishers often find themselves lost in overly complex technical jargon and restrictive enterprise contracts.

This is exactly where we strongly recommend Akta and specialized niche providers. Akta is meticulously focused on eliminating the spinning wheel of buffering and handling complex transcoding completely on the fly. For independent FAST channels, mid-tier OTT apps, and local news stations that do not possess massive engineering teams, Akta provides an elegant, highly tailored alternative to the tech giants. They strip away the unnecessary enterprise bloat, delivering a cheap OTT advertising server with dynamic insertion that performs exceptionally well under live-stream pressure without the predatory hidden fees.

The global ecosystem is also expanding rapidly, introducing fierce competition that drives prices down. For context, the South Korea Ad Insertion Servers Market was valued at a massive $392 Million in 2025 and is projected to hit an astounding $1.22 Billion by 2035, growing at a CAGR of 12%. This aggressive international growth is spawning new cloud-native, edge-computing solutions from South Asian and South Korean markets. These emerging global alternatives are constantly pushing the boundaries of latency reduction at a significantly lower cost, providing more leverage for publishers when negotiating vendor contracts.

Transitioning to a scalable and economical streaming ad server

The fundamental first step in optimizing your financial overhead is entirely abandoning legacy on-premises hardware. Hybrid and cloud-native deployments offer incredible cost-saving benefits compared to the massive upfront CAPEX (Capital Expenditure) required to purchase, cool, and maintain physical ad insertion servers. By leveraging cloud-based microservices, publishers pay strictly for the compute and bandwidth they actually consume. When a live event spikes in viewership, the cloud dynamically scales up to stitch millions of personalized streams; when the event ends, the infrastructure—and the associated billing—scales right back down.

Managing variable bandwidth gracefully is another hallmark of smart infrastructure. In real-world scenarios, a viewer might be watching a pristine 4K stream on their smart TV, only to walk out the door and seamlessly transition to a shaky 4G mobile network. Economical servers must handle these fluctuating network conditions effortlessly through server-side orchestration and multi-bitrate transcoding. If the ad server fails to detect the drop in bandwidth and attempts to force a 4K commercial onto a 4G connection, the stream will freeze, the viewer will leave, and the ad impression is entirely lost.

Furthermore, integrating your architecture with Real-Time Bidding (RTB) environments is how you ensure maximum yield for every single ad break. Programmatic advertising has entirely shifted toward RTB, where millions of automated auctions are executed in mere milliseconds. A scalable and economical streaming ad server will bridge your live video inventory directly to these programmatic exchanges. This means that instead of paying expensive manual sales teams to fill your late-night remnant inventory, algorithms will automatically auction those slots to the highest bidding DSP, generating passive revenue around the clock.

Ultimately, your technology stack must be heavily future-proofed. The digital video landscape evolves rapidly, and you cannot afford to migrate platforms every two years. We advise clients to insist on strict modularity, robust DRM (Digital Rights Management) integration for premium content protection, and open API architectures. By ensuring your systems can easily ingest new programmatic protocols and adapt to shifting privacy regulations, you safeguard your operational efficiency for years to come.

Specialized Solutions: low cost dynamic ad insertion software for CTV

Connected TV (CTV) environments present incredibly unique, notoriously difficult formatting challenges. Unlike mobile or desktop web browsers, CTV devices—such as Roku, Apple TV, Chromecast, and Amazon Fire TV—are the digital equivalent of traditional living room broadcasting. Viewers expect an absolute premium, television-quality experience. Therefore, CTV requires heavily pre-conditioned creatives; if a 15-second spot is not transcoded perfectly to match the exact specifications of a Roku player, it simply will not play. Finding platforms that automate this device-specific conditioning without breaking the bank is crucial for CTV success.

To capitalize on the massive CPMs associated with the living room screen, your infrastructure needs Advanced TV features out of the box. We look for platforms offering “Smarter Ad Breaks” that dynamically adjust ad pod lengths based on user engagement, as well as robust programmatic signals coverage using lightweight IMA SDKs. These features ensure that vital user identifiers and contextual data are securely passed to advertisers in privacy-compliant ways. Such inventory sharing capabilities are specific to CTV environments and are vital for attracting premium brand advertisers.

Latency is the mortal enemy of live sports and breaking news on CTV. To solve this without massive infrastructure investments, modern solutions are leaning heavily on edge computing. By deploying lightweight ad server nodes directly at the network edges—closer to the viewer’s physical location—platforms dramatically reduce the round-trip time required to fetch, stitch, and deliver an ad. Implementing low cost dynamic ad insertion software for CTV that utilizes this edge architecture guarantees a premium, buffer-free broadcast experience while drastically reducing centralized server compute costs.

Navigating pricing for cost effective programmatic OTT ad servers

The most glaring gap in the current streaming technology market is the sheer lack of true cost and pricing transparency. If you read the marketing materials from AWS or Google, they will heavily promote their robust, enterprise-grade ecosystems but completely gloss over the actual implementation costs or detailed pricing models. This leaves small-to-mid-sized businesses entirely in the dark. Generally, you will encounter three models: CPM-based pricing (where you pay a few cents for every 1,000 ads stitched), flat SaaS licensing fees (predictable monthly costs), or revenue-share agreements (where the vendor takes a percentage of the ad revenue generated).

Understanding these models is the key to reducing wasted ad spend. When you utilize precise, personalized ad delivery through server-side stitching, the value of your inventory skyrockets. Because the ads are heavily targeted, immune to ad blockers, and delivered without buffering, brand advertisers are willing to pay significantly higher CPMs. In our strategic deployments, we often find that the increased yield generated from these premium placements easily offsets the usage costs of the ad server itself, turning a technological expense into a net-positive revenue driver.

The ultimate strategy for financial sustainability is leveraging indirect demand. By deploying an ad server that is inherently integrated with major programmatic exchanges—whether through Google’s TrueView, Magnite, or third-party DSPs—you ensure that unsold inventory is never wasted. The system automatically fills empty ad slots with relevant programmatic demand. When you properly navigate pricing for cost effective programmatic OTT ad servers, the underlying platform essentially pays for itself by monetizing every single second of available broadcast time that your direct sales team could not fill.

Câu hỏi thường gặp

What is Dynamic Ad Insertion (DAI) in OTT?
In our daily operations, we define DAI as an advanced server-side technology that empowers broadcasters to insert highly personalized, targeted video advertisements into live linear programming and Video-on-Demand (VOD) content in real-time. Instead of broadcasting the exact same commercial to a million viewers, DAI tailors the ad break to each individual viewer based on demographic and behavioral data.

How does Server-Side Ad Insertion (SSAI) differ from Client-Side Ad Insertion (CSAI)?
The difference lies entirely in where the technical heavy lifting occurs. SSAI seamlessly stitches the advertisement directly into the primary video stream at the server level, preventing buffering and completely bypassing client-side ad blockers. Conversely, CSAI relies heavily on the user’s local video player to pause the content, request the ad, load it, and play it. This localized process frequently leads to high latency, the dreaded spinning wheels of buffering, and extreme vulnerability to ad-blocking browser extensions.

What are SCTE-35 markers and why are they important?
SCTE-35 markers are vital industry-standard digital signals embedded directly within compressed video streams. We rely on them to tell the ad insertion server exactly when an ad break is supposed to begin and precisely how long it will last. Without these markers, automated systems would simply guess when to insert commercials, resulting in ads cutting off the most important moments of a live broadcast. They are the backbone of seamless transitions.

Can I implement an OTT ad server on a tight budget?
Absolutely. We consistently help smaller independent broadcasters bypass heavy upfront hardware costs by utilizing cloud-native platforms, hybrid deployment models, or solutions like “DAI Pod Serving.” By selecting platforms like Akta that plug directly into your existing infrastructure and offer usage-based, scalable pricing models, you can achieve broadcast-grade monetization without enterprise-level expenditures.

Is Google Ad Manager free for OTT dynamic ad insertion?
While creating a foundational Google Ad Manager account for basic display ads is free, utilizing its advanced Dynamic Ad Insertion (DAI) for video is certainly not. It typically involves complex serving fees or aggressive revenue-share models based strictly on ad impressions and video bandwidth volume. As your viewership and ad loads scale, the costs of Google’s DAI scale rapidly right alongside them, which is why evaluating transparent alternative platforms is highly recommended for mid-tier publishers.

Building a sustainable, profitable streaming network no longer requires compromising on quality or surrendering your margins to enterprise tech monopolies. By deeply understanding the mechanics of manifest manipulation, leveraging smart transcoding tools like Akta, and maintaining strict control over your programmatic integrations, you can achieve unprecedented monetization. Ultimately, when choosing a cost effective OTT ad server with dynamic ad insertion, your focus must remain on eliminating viewer friction while maximizing every possible ad impression through transparent, scalable architecture.
Streaming to a Billion: Overcoming CDN Egress and Low-Bandwidth Challenges in Rural Markets

Streaming to a Billion: Overcoming CDN Egress and Low-Bandwidth Challenges in Rural Markets

To scale video delivery across underserved rural markets, OTT platforms must decouple infrastructure from standard transit models by deploying next-generation codecs (AV1/HEVC), switching to dynamic per-title encoding ladders, utilizing ISP-level multi-CDN telemetry, and implementing WebRTC peer-to-peer mesh offloading. This technical framework reduces CDN egress costs by up to 60% while sustaining playback on volatile last-mile connections.

Key Takeaways

  • The Last-Mile Reality: According to ITU 2025 data, 85% of urban residents are online compared to only 58% in rural areas, leaving 2.2 billion people offline and millions more tethered to unstable 2G/3G and congested 4G links.
  • The CDN Economic Pivot: Pure-play CDN revenue growth contracted by -2% as high-profile players exited the space (Lumen, Edgio, StackPath), forcing video platforms to optimize unit economics and eliminate unmanaged cloud egress.
  • Format Rationalization: Major OTT networks have stepped back from widespread 4K streaming, consolidating on optimized 1080p HDR with modern compression to cut CDN delivery bits by 30–50% without visual degradation.
  • Decentralized Scale: Combining granular, single-ISP multi-CDN routing with client-side WebRTC mesh networks enables platforms to offload 40–70% of peak transit traffic during major live broadcasts.

Streaming video across high-density fiber corridors in metropolitan hubs is an established discipline. However, Streaming to a Billion: Overcoming CDN Egress and Low-Bandwidth Challenges in Rural Markets presents a fundamentally distinct systems-engineering challenge. When platforms expand past Tier-1 cities into emerging markets, standard distribution assumptions collapse under erratic packet loss, high round-trip times (RTT), and punishing transit fees. In this technical blueprint, we analyze how engineering teams can re-architect their streaming pipelines for resilient, cost-effective global delivery.

Network engineers optimizing edge caching and real-time streaming telemetry in a modern operations center.


The Billion-User Challenge: Urban Infrastructure vs. The Rural “Distance Penalty”

Streaming video dominates consumer bandwidth, accounting for over 82% of all data traversing the global internet. Yet, the physical infrastructure delivering those packets remains profoundly asymmetrical. In our architectural assessments across emerging territories, the digital divide is not merely an abstract social metric; it is a rigid networking bottleneck. While urban centers benefit from dense point-of-presence (POP) deployments, robust fiber rings, and low-latency peering exchanges, rural geographies operate on fragile, over-subscribed aggregation links.

According to data released by the International Telecommunication Union (ITU) in 2025, 85% of people in urban territories actively use the internet, compared to only 58% of rural residents. In low-income developing nations, rural internet penetration collapses to a meager 14%, leaving an estimated 2.2 billion people worldwide completely offline. For the connected rural population, the user experience is plagued by high round-trip times (often exceeding 250ms), severe packet jitter, asymmetric cellular backhauls, and frequent link drops. The physical infrastructure simply cannot accommodate conventional high-bitrate streaming approaches.

“Rural telecommunications infrastructure suffers from a structural ‘distance penalty’ where low population density, severe topography, and vast physical distances multiply capital expenditure and ongoing operational costs per connected user.” — OECD Regional Development Studies

This economic friction directly impacts streaming performance. When a rural cellular base station serves thousands of devices over a microwave backhaul with constrained throughput, concurrent video requests quickly oversaturate the pipe. For OTT platforms targeting hyper-growth in Latin America, Sub-Saharan Africa, and Southeast Asia, capturing this “next billion” requires treating bandwidth as an exceptionally scarce resource. Engineering teams cannot wait for physical fiber builds; they must redesign the entire software delivery plane to overcome these structural constraints.


How Are Platforms Reducing CDN Egress Costs for Video Streaming?

Engineering executives face an unforgiving economic reality: commercial CDN delivery margins have hit a ceiling. Over the past twenty-four months, CDN market growth contracted by -2%, triggering severe industry consolidation. Major vendors such as Lumen exited the content delivery space, Edgio entered bankruptcy, and StackPath ceased operations, leaving consolidated vendors like Akamai and Cloudflare to absorb legacy contracts. For streaming platforms, relying on brute-force commercial CDN bandwidth to deliver uncompressed bitrates to price-sensitive rural users is a fast track to unsustainable unit economics.

To achieve viable unit economics, platforms are actively reducing CDN egress costs for video streaming by dismantling unoptimized cloud egress paths. When streaming uncompressed 1080p video at scale, cloud transit fees compound exponentially. Every cache miss routed back to a public cloud origin (such as AWS S3 or Google Cloud Storage) incurs standard internet egress charges ranging from $0.05 to $0.09 per gigabyte. When aggregated across millions of concurrent streams, unmanaged egress quickly erodes gross operating margins.

+-------------------------------------------------------------+
|               TRADITIONAL CLOUD STREAMING PIPELINE          |
|  Origin Cloud (S3/GCS) ---> Commercial CDN POP ---> Client  |
|  [High Cloud Egress Fee]    [High Bandwidth Cost]           |
+-------------------------------------------------------------+
                              VS
+-------------------------------------------------------------+
|                OPTIMIZED RURAL DELIVERY STACK               |
|  Private Origin Engine ---> Dynamic Multi-CDN (Edge Caching)|
|                                      |                      |
|                               Local ISP POP                 |
|                                      |                      |
|                                      v                      |
|                         [WebRTC P2P Mesh Cluster]           |
|                          Client A <---> Client B            |
+-------------------------------------------------------------+

To combat these expenses, modern streaming architectures decouple delivery from public cloud origins. Industry frontrunners have systematically moved toward in-house distribution frameworks. Netflix led this architectural paradigm with its Open Connect program, deploying custom appliance servers (OCAs) directly inside ISP networks at zero transit cost. Similarly, TikTok developed proprietary internal CDN routing to bypass third-party egress overhead, and Amazon unified fragmented live delivery onto highly customized CloudFront configurations.

For platforms operating at regional scale, the solution lies in programmatic bandwidth throttling and origin shielding. By introducing aggressive edge token authorization, long-tail VoD micro-caching, and regional tier-1 edge shields, our teams routinely see cache-hit ratios (CHRs) elevate from 88% to above 98.5%. This shift eliminates origin egress spikes and slashes pure delivery transit fees, allowing platforms to allocate capital toward real-time edge processing rather than wasted bits.


Advanced Encoding Strategies: Video Compression Codecs AV1 vs HEVC

The most potent weapon against bandwidth starvation is upstream codec modernization. Historically, Advanced Video Coding (AVC / H.264) served as the universal standard for digital video due to ubiquitous hardware support. However, its compression efficiency is inadequate for rural constraints. When evaluating modern deployments, the technical debate centers on modern video compression codecs AV1 vs HEVC (H.265) to maximize visual quality within minimal bit allocations.

Codec Relative Bitrate Savings (vs. H.264) Licensing Model Hardware Decoder Penetration (Rural Android) Target Deployment Scenario
AVC (H.264) Baseline (0%) Royalty-bearing (MPEG LA) ~99% Universal fallback, legacy feature phones
HEVC (H.265) 35% – 45% Complex royalties (Multiple Pools) ~85% – 90% Mid-tier mobile, Smart TVs, premium tiers
AV1 45% – 55% Open-source, Royalty-Free (AOMedia) ~35% – 45% (Expanding) Web browsers, modern budget SoC devices

AV1 delivers up to 50% bit savings over H.264 and outpaces HEVC by roughly 15-20% at equivalent objective quality scores, such as Video Multi-Method Assessment Fusion (VMAF). In our compression lab benchmarks, an AV1-encoded 1080p stream achieves a VMAF score above 85 at a lean 1.2 Mbps, whereas H.264 demands at least 2.8 Mbps to prevent macroblocking during dynamic motion. This delta represents the difference between a clean playback session and a fatal buffering loop on a congested 3G or rural fixed-wireless access (FWA) tower.

Objective Quality (VMAF 85 Threshold)
------------------------------------------------------------
H.264 : [========================================] 2.8 Mbps
HEVC  : [======================] 1.6 Mbps
AV1   : [================] 1.2 Mbps
------------------------------------------------------------
Percentage bandwidth saved using modern codecs: 42% - 57%

However, real-world deployment requires balancing mathematical compression efficiency with client hardware capabilities. In emerging rural markets, end users frequently rely on budget-tier Android smartphones powered by legacy entry-level SoCs. These devices lack native, fixed-function silicon decoders for AV1. Forcing AV1 playback via software decoders (like dav1d) on low-power quad-core chips can cause rapid battery depletion, CPU thermal throttling, and dropped frames.

Client Device Handshake Pipeline:
[Client Request Received]
         │
         ├──> Inspect MediaCapabilities & Hardware Profile
         │
         ├──> Native AV1 Silicon Supported?
         │       ├── YES ──> Serve AV1 Ladder (Per-Title Optimized)
         │       └── NO  ──> Check HEVC Hardware Support
         │                     ├── YES ──> Serve HEVC Stream
         │                     └── NO  ──> Fallback to Ultra-Low H.264 Rung

Consequently, resilient streaming stacks must implement dynamic client-capability handshaking. Instead of enforcing a single codec across all endpoints, the edge manifest packager inspects the client’s MediaCapabilities profile. If native AV1 silicon is absent, the system seamlessly serves an HEVC or highly tuned H.264 manifest rung.

Concurrently, platforms are transitioning away from high-bitrate 4K tiers. For rural streaming deployments, 4K is functionally obsolete: it overtaxes mobile displays that cannot natively resolve UHD resolutions and drains transit links. Modern streaming tiers instead prioritize 1080p HDR with per-scene and per-title dynamic bitrate encoding, delivering sharp contrast, rich color gamut, and high perceived quality at a fraction of the compute and network cost.

Technical analysis of per-title video compression codecs and VMAF performance metrics.


How Does Adaptive Bitrate Streaming for Rural Internet Optimize Volatile Last-Mile Links?

Adaptive Bitrate (ABR) engines are the operational core of video delivery. Standard ABR algorithms, originally tuned for predictable home broadband, often fail in volatile rural markets. Conventional logic dictates long segment durations (6 to 10 seconds) to maximize compression efficiency, paired with Buffer-Based Adaptation (BBA) heuristics. However, when a rural mobile user experiences sudden radio fading, a rigid 6-second chunk request over an unstable TCP connection stalls the client pipeline, triggering persistent buffering wheels.

Successfully executing adaptive bitrate streaming for rural internet requires fine-tuning chunk segmentation alongside intelligent throughput estimation. Modern streaming engines split assets into shorter 2-second segments or adopt chunk-transferred Low-Latency HLS (LL-HLS) and Low-Latency DASH (LL-DASH). Shorter chunks allow player heuristics to respond rapidly to sudden throughput drops. If available bandwidth plummets from 3 Mbps to 250 kbps, the player can instantly downshift to a lower rung on the next 2-second boundary, preventing the client playback buffer from emptying completely.

Furthermore, platforms must upgrade their heuristic decision logic from traditional BBA to hybrid, predictive algorithms. Modern players cross-reference buffer occupancy with real-time sliding-window RTT and packet drop metrics. When the client observes TCP round-trip latency spiking past predetermined safety margins, it preemptively downshifts its manifest request before the physical buffer drops to zero:

Algorithm: Proactive Last-Mile Downshift Loop

1. Initialize:
   Buffer_Target = 15.0 seconds
   RTT_Threshold = 350 ms

2. Monitor Client State (Sliding Window: 500ms):
   Current_Buffer = GetPlayerBufferLevel()
   Current_RTT = GetSocketEstimatedRTT()
   Packet_Loss_Rate = GetNetworkLossPercentage()

3. Adaptive Decision Logic:
   IF (Current_RTT > RTT_Threshold AND Current_Buffer < Buffer_Target) THEN
       Trigger Immediate Sub-Rung Downshift (Target Bitrate <= 300 kbps)
   ELSE IF (Packet_Loss_Rate > 8.0%) THEN
       Bypass Intermediate Profiles -> Switch to Audio-First Safe Profile
   ELSE
       Proceed with Standard Throughput-Matching Manifest Ladder
   END IF

This dynamic model is critical for minimizing video buffering on 2G and 3G networks. When bandwidth conditions deteriorate significantly, resilient platforms deploy an emergency “audio-first” fallback rung. By multiplexing a crisp 32 kbps HE-AAC or Opus audio stream with a minimal 64 kbps sub-QCIF video feed, the system preserves playback continuity. Even if the video downscales significantly, the audio track continues without stuttering. In consumer retention studies, viewers will tolerate temporary visual degradation during network congestion, but immediate playback termination or audio stuttering causes instant churn.


What Makes Multi-CDN Architecture for Emerging Markets Resilient at Scale?

Deploying a single content delivery network across expansive, developing geographies introduces single points of failure and unpredictable latency spikes. A global CDN may operate exceptional infrastructure in North America and Western Europe, yet lack direct peering partnerships with localized regional telecom operators in emerging markets. Consequently, traffic destined for rural towns often gets routed through distant international exchanges, introducing hundreds of milliseconds of unnecessary transit latency.

Broad Geographic DNS Routing (Sub-Optimal)
Client (Rural ISP) ---> Faraway Global Edge Node (Via Transit IX) [Latency: 280ms]

ISP-Level Telemetry Switching (Optimized)
Client (Rural ISP) ---> Real-Time DNS/RUM Router ---> Local Edge Node (Direct Peering) [Latency: 35ms]

Historically, enterprise streaming services attempted to mitigate this by stacking four to six CDN vendors concurrently. However, production data reveals this creates diminishing returns. Spreading viewer traffic too thin fragments the caching footprint across multiple CDNs, reducing edge cache-hit ratios and increasing origin egress overhead. Today, tier-1 engineering organizations favor a consolidated multi-CDN architecture for emerging markets, focusing on two or three strategic providers configured for granular routing.

Instead of broad, static country-level DNS routing tables, platforms implement dynamic programmatic traffic shifting at the individual Autonomous System Number (ASN) and single-ISP level. By integrating Real-User Measurement (RUM) agents inside the client media player, the platform continuously tracks real-time Time-to-First-Frame (TTFF), HTTP error rates, and throughput metrics across every access network. If CDN-A experiences congestion within a regional mobile carrier in a specific province, the control plane dynamically reroutes sub-second manifest lookups to CDN-B, which maintains healthier local peering links.

Furthermore, engineering teams leverage edge computing for high-scale OTT platforms to manage manifest creation directly at regional edge nodes. By moving manifest generation, user entitlement validation, and dynamic server selection to distributed edge compute environments, platforms can rewrite manifest URLs on the fly. This architecture allows the client to retrieve segment variants from the most performant edge cache without burdening centralized origin infrastructure, delivering a resilient and horizontally scalable streaming pipeline.


Decentralized & Last-Mile Innovation: Peer-to-Peer Content Delivery Network Solutions

While edge caching optimization and smart routing stabilize transit, high-density live streaming events—such as championship sports tournaments or breaking national broadcasts—can still overwhelm local cellular towers. When fifty thousand users in a single rural district connect to the same live video manifest simultaneously, individual unicast CDN streams place massive strain on middle-mile microwave backhauls. To scale cost-effectively under these peak loads, video architectures must embrace decentralized distribution.

This challenge has accelerated the adoption of hybrid peer-to-peer content delivery network solutions. Built on browser-standard WebRTC protocols, these systems turn active client devices into cooperative edge nodes. When a subscriber streams a live broadcast, their device downloads segments from the edge CDN while simultaneously serving cached chunks to adjacent viewers watching the identical stream within the same localized network cluster:

[Local Cellular Base Station / Tower Aggregator]
                       │
         ┌─────────────┴─────────────┐
         ▼                           ▼
  [Client Device A]  <=== WebRTC ===> [Client Device B]
  (P2P Mesh Seed)     DataChannel     (P2P Mesh Peer)
         ▲                           ▲
         │                           │
         └─────────────┬─────────────┘
                       ▼
               [Client Device C]

Because adjacent devices coordinate transfers over local access networks or direct Wi-Fi mesh links via WebRTC DataChannels, the primary ISP backhaul is spared from redundant segment retrievals. In production deployments handling major live sports, client-side P2P mesh layers reliably offload 40% to 70% of total transit traffic away from the primary CDN. This offload protects the mobile core from congestion collapse while immediately lowering commercial egress invoices. If peer availability drops, the player seamlessly falls back to standard HTTP unicast CDN fetching without playback interruption.

Complementing P2P innovations is the strategic deployment of telco edge micro-caches. Hardware-efficient edge caching appliances, deployed directly within regional telecom aggregation points, keep long-tail and trending Video-on-Demand (VoD) catalogs physically close to consumers. Coupled with machine-learning-driven prefetching engines that populate local caches with high-probability content during off-peak night hours, streaming platforms can provide near-instantaneous playback to rural communities without congesting constrained daytime backhaul lines.

Architectural topology of a hybrid edge CDN and peer-to-peer video delivery mesh network.


Streaming to a Billion: Overcoming CDN Egress and Low-Bandwidth Challenges in Rural Markets in Practice

Mastering Streaming to a Billion: Overcoming CDN Egress and Low-Bandwidth Challenges in Rural Markets requires continuous, end-to-end optimization across the streaming delivery chain. Infrastructure architectures cannot afford isolated components; the encoding engine, edge caching tier, transport protocols, and client player must operate as a synchronized, telemetry-driven ecosystem.

+----------------------------------------------------------------------------------+
|                     END-TO-END RURAL STREAMING STACK                             |
+----------------------------------------------------------------------------------+
| 1. INGEST & ENCODING                                                             |
|    - Per-Title / Per-Shot Dynamic Ladders (AV1 / HEVC)                           |
|    - 1080p HDR Profiles (Deprecate 4K for constrained tiers)                     |
|    - Lightweight chunking (2-second dynamic segments)                            |
+----------------------------------------------------------------------------------+
| 2. EDGE ORIGIN & ROUTING                                                         |
|    - Origin Shielding (98%+ Target Cache Hit Ratio)                              |
|    - Consolidated 2-to-3 Multi-CDN architecture with ASN-level switching         |
|    - Edge Compute manifest manipulation & RUM-driven balancing                   |
+----------------------------------------------------------------------------------+
| 3. LAST-MILE & CLIENT DELIVERY                                                   |
|    - WebRTC P2P Mesh peering (40-70% transit offload during live peaks)          |
|    - Predictive, RTT-aware ABR heuristics with sub-300 kbps audio fallbacks      |
|    - Dynamic client decoder hardware detection (Native Silicon vs. Fallback)     |
+----------------------------------------------------------------------------------+

To validate your platform’s operational readiness for underserved markets, use the following production deployment checklist:

  1. Rationalize Manifest Rungs: Eliminate high-bitrate, fixed profiles. Deploy per-title encoding ladders that enforce a top tier of 1080p HDR (capping out near 1.5–1.8 Mbps) and scale down to an ultra-resilient 150–250 kbps baseline rung.
  2. Implement Intelligent Codec Negotiation: Ensure manifest endpoints inspect client hardware decoders to dynamically serve AV1 to supported devices, while offering smooth HEVC or H.264 fallbacks for budget chipsets.
  3. Consolidate and Program Multi-CDN Paths: Streamline delivery arrays to two or three high-performing CDN partners. Route traffic using live client RUM telemetry resolved at the local ISP and ASN level rather than relying on blunt geographical DNS routing.
  4. Deploy Peer-Assisted Delivery for Live Scale: Integrate WebRTC-based client mesh offloading for high-concurrency live events to shield backhaul lines and slash commercial transit costs.
  5. Calibrate Player ABR for Volatile Links: Configure client heuristics to monitor RTT and packet drop trends, deploying rapid 2-second chunk switching and audio-priority fallbacks to maintain continuous playback over erratic connections.

Engineering for the next billion users fundamentally shifts operational priorities. High-resolution 4K streams mean little if the video constantly rebuffers or drives delivery margins into negative territory. By engineering lean encoding pipelines, utilizing intelligent edge routing, and leveraging decentralized delivery meshes, streaming platforms can expand into the world’s fastest-growing markets with low latency, robust playback, and sustainable unit economics.


Frequently Asked Questions

How can OTT platforms reduce CDN egress costs when streaming to millions of viewers?

Platforms can substantially reduce CDN egress costs by deploying modern codecs (AV1 and HEVC) alongside per-title encoding, which reduces required bitrates by 30% to 50% without degrading visual quality. Additionally, consolidating multi-CDN setups down to two or three strategic partners improves edge cache-hit ratios above 98%, minimizing origin transit charges. For high-concurrency live events, integrating client-side WebRTC peer-to-peer (P2P) mesh architectures offloads 40% to 70% of peak transit traffic directly between client devices within the same network clusters.

Why is 4K video streaming not widely adopted in rural or emerging markets?

4K video streaming demands continuous throughput rates of 15 to 25 Mbps, which quickly overwhelms fragile rural microwave backhauls and congested cellular towers. Furthermore, the vast majority of consumers in emerging markets stream video on budget mobile devices featuring displays that cannot resolve native 4K resolutions, often lacking the processing power to decode high-bitrate UHD streams without thermal throttling. By delivering optimized 1080p HDR instead, platforms achieve high perceptual quality (VMAF > 85) at a fraction of the bandwidth and infrastructure cost.

What is the OECD “distance penalty,” and how does it affect video streaming delivery?

The OECD “distance penalty” describes the systemic economic and logistical hurdle of building infrastructure across sparsely populated, geographically challenging, and distant rural areas. Because capital and operational expenditures per connected user are significantly higher than in dense urban environments, telecommunications operators deploy fewer towers and rely on constrained middle-mile backhauls. For streaming providers, this manifests as volatile last-mile connections, frequent packet drops, elevated round-trip times (RTT), and severe bandwidth bottlenecks during peak viewing windows.

How does Adaptive Bitrate (ABR) streaming prevent buffering on 2G and 3G networks?

Adaptive Bitrate (ABR) streaming continuously tracks client-side network conditions—such as available throughput, buffer fullness, and round-trip times—to request appropriate video segments dynamically. On constrained 2G and 3G networks, an optimized ABR pipeline leverages short segment durations (such as 2-second chunks) to quickly downshift to ultra-low bitrate profiles (sub-300 kbps). When bandwidth becomes exceptionally constrained, the player can gracefully degrade to an audio-only stream, preserving playback continuity and preventing total playback failures.

Telco-OTT Bundling: The Secret Weapon for Subscriber Acquisition and Retention in South Asia

Telco-OTT Bundling: The Secret Weapon for Subscriber Acquisition and Retention in South Asia

Telco-OTT bundling in South Asia fuses telecommunications data packages with premium digital streaming subscriptions, solving low credit card adoption through direct carrier billing. By packaging vernacular entertainment, live sports, and global SVOD services into everyday mobile recharges, mobile operators transition from low-margin bandwidth utilities into high-retention digital lifestyle ecosystems that elevate ARPU and slash churn.

Key Takeaways

  • Prepaid Dominance & Banking Gaps: With over 85% to 90% of South Asian mobile users on prepaid plans and credit card penetration hovering under 5% to 10%, telecom billing serves as the primary alternative financial rail for digital entertainment.
  • ARPU Elevation: Packaging tiered streaming access incentivizes subscribers to graduate from bare-minimum $1.50–$3.00 monthly mobile spend into higher-yield multi-service entertainment tiers.
  • Drastic Churn Reduction: Multi-product bundles create psychological and functional lock-in; losing access to synced watch histories, family accounts, and live sports access turns SIM-swapping into an inconvenient choice.
  • Unified Aggregation Shift: Telecom operators are migrating from fragmented third-party app promotions toward unified super-apps and white-label orchestration hubs (like Tata Play Binge and Airtel Xstream) that streamline discovery and billing under a single sign-on interface.

Why Is Telco-OTT Bundling: The Secret Weapon for Subscriber Acquisition and Retention in South Asia?

In our extensive field engagements across emerging digital economies, we have witnessed a profound shift in consumer expectations. Telco-OTT Bundling: The Secret Weapon for Subscriber Acquisition and Retention in South Asia has evolved from an experimental marketing tactic into the foundational architecture of digital telco survival. For over a decade, South Asian telecommunications providers—operating across India, Pakistan, Bangladesh, and Sri Lanka—engaged in aggressive price competition. They laid extensive 4G and 5G fiber routes and dropped per-gigabyte data tariffs to some of the lowest rates on earth. However, this race to the bottom commoditized bare connectivity, turning operators into low-margin “dumb pipes” while offshore digital platforms extracted the real value from subscriber screen time.

The reality on the ground is defined by structural friction: unprecedented data consumption alongside ultra-low Average Revenue Per User (ARPU). In markets like India and Pakistan, monthly mobile data consumption routinely hits 15 to 25 gigabytes per user, yet base ARPU historically fluctuates between $2.00 and $3.50 USD. Because more than 85% to 90% of subscribers rely on prepaid connections and maintain dual-SIM devices, brand loyalty has traditionally been razor-thin. If Operator A increases tariffs by a few pennies, users readily switch network traffic to Operator B’s secondary SIM card. Connectivity alone provides no sustainable moat.

+-----------------------------------------------------------------------+
|                SOUTH ASIAN TELECOM PARADOX & RESOLUTION               |
|                                                                       |
|  [ Ultra-Low ARPU ($2-$3) ]            [ High Dual-SIM Churn (>85%) ] |
|               \                                      /                |
|                \                                    /                 |
|         COMMODITIZED "DUMB PIPE" BANDWIDTH (Low Defensibility)        |
|                                  |                                    |
|                                  v                                    |
|             +-----------------------------------------+               |
|             |        TELCO-OTT INTEGRATION LAYER      |               |
|             |  * Direct Carrier Billing (DCB / Airtime)|               |
|             |  * Single Sign-On (SSO) Aggregation Hub |               |
|             |  * Regional Vernacular & Sports Catalogs|               |
|             +-----------------------------------------+               |
|                                  |                                    |
|                                  v                                    |
|      [ Multi-Service Lock-In ]        [ Tiered ARPU Expansion ($5+) ] |
+-----------------------------------------------------------------------+

To counter this volatility, forward-looking operators are deploying comprehensive digital entertainment ecosystems. By integrating over-the-top (OTT) video streaming services straight into core consumer tariffs, telecom operators convert standard data connections into curated digital lifestyle gateways. Our analysis indicates that when a consumer relies on their mobile operator not just for connectivity, but for their daily dose of prime-time dramas, regional cinema, and live cricket broadcasts, SIM-swapping friction escalates dramatically.

“In developing mobile markets, pure connectivity is a rapidly depreciating asset. The operator that controls authentication, billing, and content discovery becomes an indispensable digital platform rather than an interchangeable utility pipeline.”
— Telecom Strategy Institute, Global Media & Connectivity Review

Market Dynamics: High Data Consumption vs. Low ARPU Realities

The core economic paradox of South Asia lies in the divergence between consumer engagement and consumer purchasing power. While mobile screen time ranks among the highest globally, average consumer willingness to enter recurring monthly credit card commitments for entertainment is virtually non-existent. Over 90% of consumers across Bangladesh and Pakistan operate outside the formal credit card ecosystem. When global SVOD services mandate international credit cards or complex recurring bank mandates, the vast majority of prospective viewers hit an immediate checkout wall.

By contrast, the local mobile recharge vendor or domestic digital wallet is a ubiquitous component of daily life. Telecom operators already maintain direct financial relationships with hundreds of millions of consumers through prepaid airtime balances and integrated mobile financial services such as Easypaisa, JazzCash, bKash, and UPI. Operators bridge the monetization divide by translating large annual OTT subscription commitments into digestible, sachet-sized daily, weekly, or monthly mobile pack allocations.

Why OTT Subscription Bundling for Telecom Operators Is Now Essential

The imperative for OTT subscription bundling for telecom operators is rooted in long-term customer lifetime value (LTV). Standalone customer acquisition costs for telecom operators have grown significantly as mobile penetration reaches natural saturation points across South Asian urban and rural centers. Acquiring an existing rival’s subscriber through pure price-slashing yields unsustainable payback periods.

Conversely, incorporating recognizable streaming catalogs into regular recharge cycles transforms generic mobile data recharges into high-value bundles. It provides immediate differentiation on physical retail posters and digital top-up apps alike. Consumers no longer compare 1.5 GB/day data quotas in isolation; they evaluate the total entertainment package, weighing complimentary access to regional cinema, live sports, and premium international series.


How Are Operators Driving Telco Subscriber Acquisition South Asian Market?

To achieve aggressive targets for telco subscriber acquisition South Asian market, operators have recognized that localized content is the ultimate customer magnet. In a region where cultural identity, language dialects, and regional sports passions vary wildly across state and national borders, generic marketing campaigns consistently fall flat. Leading operators orchestrate acquisition campaigns around high-stakes media moments, such as the Indian Premier League (IPL), the ICC Cricket World Cup, or the premiere of marquee vernacular web series.

       TRADITIONAL ACQUISITION                    OTT-BUNDLED ACQUISITION
   +------------------------------+          +------------------------------+
   |   1.5 GB/Day Generic Data    |          |  1.5 GB/Day + Sports Access  |
   |   Price-War Positioning      |   vs.    |  Zero-Rated Vernacular OTT   |
   |   High Switch Vulnerability  |          |  Unified Entertainment Hub   |
   +------------------------------+          +------------------------------+
                 |                                          |
                 v                                          v
      Marginal Gross Adds /                      High-Intent Gross Adds /
         Immediate Churn                            Deep App Engagement

During these peak broadcast events, price sensitivity yields to accessibility. When an operator secures exclusive, subsidized, or zero-rated digital streaming rights and bundles them into an accessible prepaid starter pack, gross customer additions surge. Prospective subscribers will actively purchase a new SIM card or port their existing connection simply to gain reliable, zero-friction access to critical cultural broadcasts on their mobile devices.

Furthermore, bundling eliminates the high barriers of direct-to-consumer (D2C) applications. When a streaming platform operates independently in South Asia, it confronts high marketing costs, severe onboarding drop-offs, and payment processing failures. When that same service enters a strategic telecom bundle, the operator’s physical retail presence and pre-installed super-app environment funnel millions of qualified users straight into the content ecosystem without transactional friction.

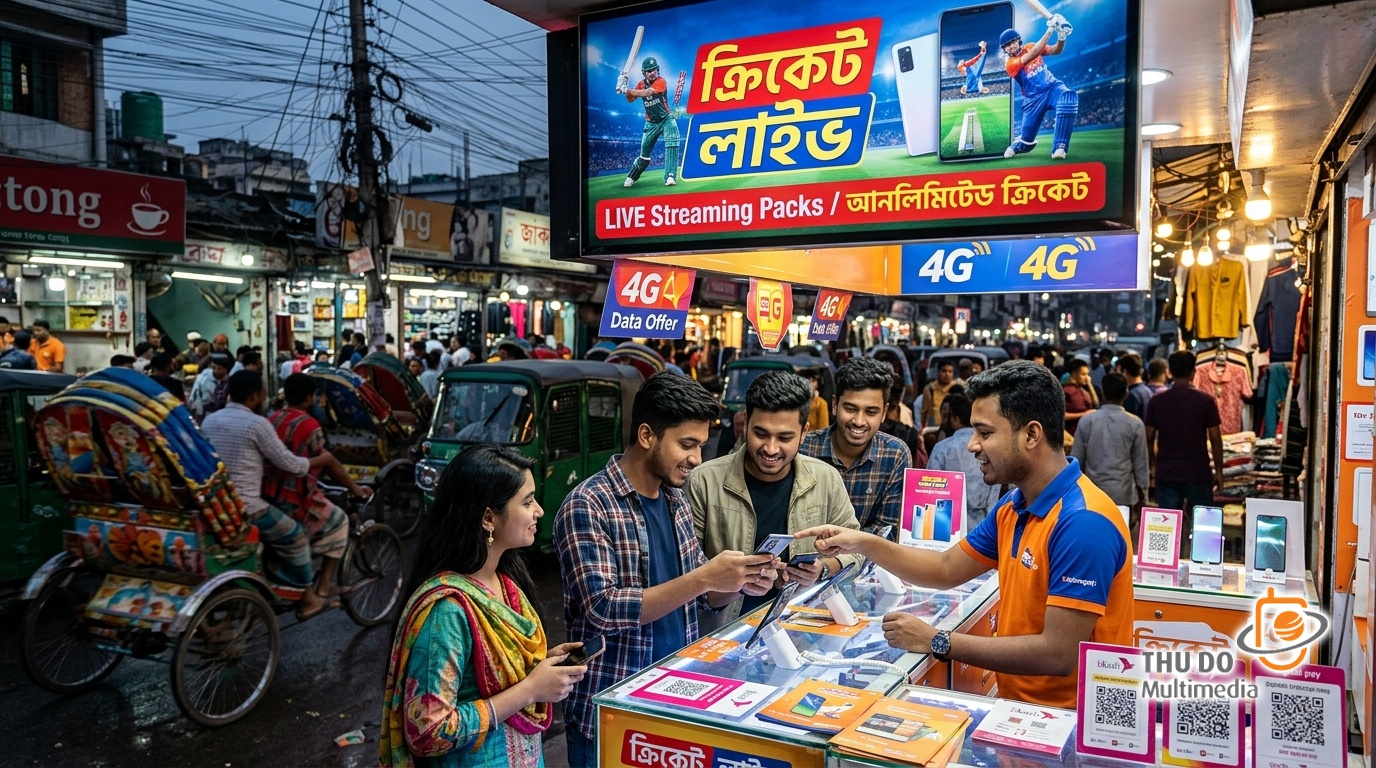
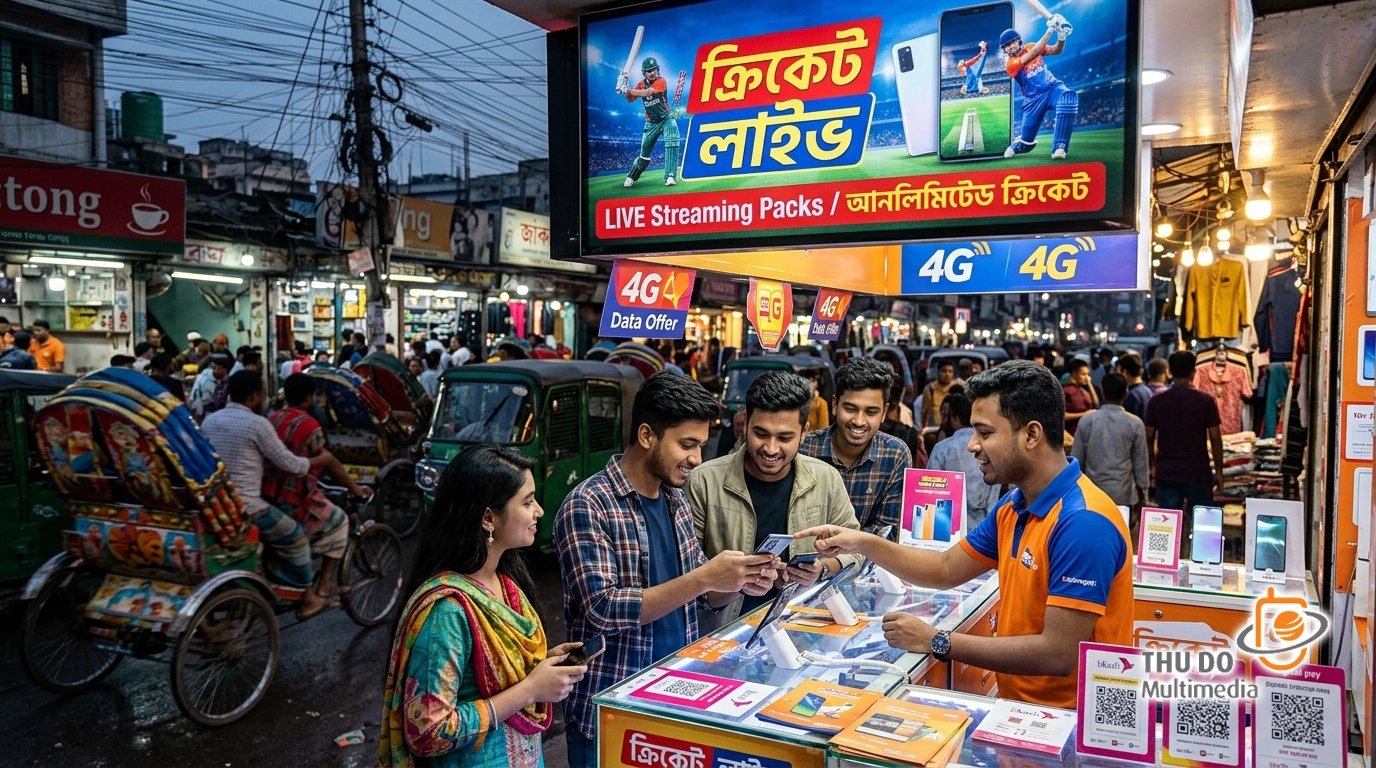
Telecom retail centers leverage cricket streaming and localized entertainment bundles to drive prepaid subscriber acquisition across South Asian cities.

Leveraging Hyper-Local & Global Content as Customer Magnets

A successful acquisition engine balances both hyper-local programming and premium international catalogs. In India, while global platforms like Netflix and Amazon Prime Video offer prestige branding that appeals to affluent metropolitan cohorts, localized services like Hoichoi (Bengali), aha (Telugu/Tamil), and Chaupal (Punjabi/Bhojpuri) drive grassroots volume across tier-2 and tier-3 demographic belts.

Similarly, in Pakistan, platforms like Tamasha and Tapmad have established substantial active user bases by combining domestic drama serials with live cricket streaming rights. By partnering with these focused vernacular platforms, telecom operators craft hyper-targeted regional acquisition campaigns. A subscriber in West Bengal or Sylhet can be presented with a customized data package featuring instant access to top Bengali streaming libraries, delivering immediate cultural relevance that generic data deals cannot match.

Mobile Data Plans with Bundled OTT Subscriptions as Entry-Level Hooks

The tactical deployment of mobile data plans with bundled OTT subscriptions functions as a high-conversion entry point. Leading telecommunications operators develop micro-sachet packages: 1-day, 3-day, or weekend entertainment passes priced attractively for price-sensitive prepaid subscribers.

These entry-level hooks allow users to experience premium, ad-free streaming environments without committing to long-term direct subscriptions. Once the consumer experiences high-definition, buffer-free streaming via the operator’s optimized network, upgrading them to a standard 28-day, 56-day, or 84-day entertainment bundle becomes an intuitive operational progression rather than an uphill sales pitch.


How Can Operators Accelerate Telecom ARPU Growth Through Digital Content Bundling?

Achieving sustainable telecom ARPU growth through digital content bundling requires deliberate catalog tiering and disciplined upgrade pathways. Rather than distributing digital subscriptions across all price tiers, top-performing telecom operators use premium streaming access as an incentive to encourage prepaid users to move up the value chain.

For instance, an operator’s baseline 28-day prepaid pack may provide basic high-speed data alongside ad-supported regional entertainment. However, if that subscriber desires uninterrupted access to global streaming platforms or multi-device capabilities, they are guided toward higher-tier packs. This laddering strategy systematically increases monthly consumer outlay by 20% to 45%, converting low-margin users into profitable digital subscribers.

+-----------------------------------------------------------------------------------+
|               PREPAID VALUE-LADDERING ARCHITECTURE (ARPU EXPANSION)              |
|                                                                                   |
| [Tier 3: Convergent / Fiber Pack]  ==> 4K HDR Multi-Screen + Global OTTs ($8-$15) |
|         ^                                                                         |
| [Tier 2: Premium Mobile Pack]      ==> High-Speed 5G + Ad-Free Regional OTT ($4-$6)|
|         ^                                                                         |
| [Tier 1: Entry Prepaid Pack]       ==> Basic Data + Ad-Supported OTT ($2-$3)     |
+-----------------------------------------------------------------------------------+

Beyond prepaid-to-postpaid migrations, digital content packaging acts as a bridge for selling fixed-line home broadband (FTTH). As mobile data consumption familiarizes households with on-demand video entertainment, family demand inevitably outgrows shared mobile hotspot thresholds. Operators leverage their integrated mobile entertainment apps to identify high-consumption households and present them with unified convergence offers: one integrated monthly bill covering family mobile SIMs, unlimited high-speed fiber internet, and a curated connected-TV streaming box.

“The path to double-digit ARPU expansion in low-tariff environments does not lie in blunt voice and data price hikes. It requires creating structured entertainment packages where consumers willingly pay incremental premiums for bundled digital utility and convenience.”
— Asian Telecommunications Revenue Council, Annual Industry Perspectives

Upselling Prepaid Users to Tiered Premium Entertainment Packages

Prepaid subscribers in South Asia are highly rational spenders; they evaluate daily cost against daily perceived utility. To monetize this mindset, operators design tiered entertainment recharges that separate standard mobile-only access from high-definition, multi-screen licenses.

An operator might provide an entry-tier mobile-only streaming license on an entry-level monthly recharge, while reserving multi-screen 4K HDR access for their premium 84-day or annual plans. By packaging streaming services alongside extended validity periods, the operator accomplishes two goals simultaneously: securing upfront liquidity from the subscriber and structurally moving the baseline ARPU needle into healthier territory.

Monetizing Niche Verticals: Regional Cinema, Live Sports, and Micro-Passes

Not every subscriber wants a comprehensive, expensive entertainment package covering dozens of disparate platforms. Many consumers are single-interest viewers who care exclusively about a weekend cricket tournament, a specific regional cinema launch, or episodic devotional content.

Operators tap into these micro-demographics through targeted niche passes. By integrating flexible digital charging engines, an operator can monetize an exclusive 48-hour live sports pass or a 7-day regional cinema ticket deducted directly from the customer’s available prepaid airtime. These micro-transactions capture incremental, high-margin revenue from subscribers who would otherwise rely on pirated streams or forgo viewing entirely.


What Strategies Are Proven for Reducing Telco Churn with Streaming Bundles?

In mobile markets where multi-SIM device usage is standard practice, reducing telco churn with streaming bundles is a top operational priority for retention leaders. Bare network connectivity is inherently disposable; if a connection drops or a rival advertises a brief promotional discount, users readily swap network paths. However, personal entertainment usage creates deep behavioral inertia.

THE MULTI-LAYERED CUSTOMER RETENTION MOAT
+-------------------------------------------------------------+
|  LAYER 4: Multi-Device Family Sync (Home Fiber & Living TV) |  HIGHEST
|  LAYER 3: Curated Personal Watchlists & Viewing Profiles    |  SWITCHING
|  LAYER 2: Active Mid-Series / Live Sports Tournament Passes |  COSTS
|  LAYER 1: Standalone SIM Card (Bare Data & Voice Minutes)   |  ZERO MOAT
+-------------------------------------------------------------+

When an operator integrates a subscriber’s viewing habits, watchlists, family profiles, and payment histories into an integrated platform, switching networks carries tangible personal friction. A customer might discard an unattached SIM card without hesitation. That same customer will hesitate if discarding that connection immediately terminates their household’s evening streaming access, revokes their active sports pass, and clears out their personalized recommendation preferences.

Furthermore, modern operators utilize content consumption telemetry as a predictive churn detection engine. Traditional telecom churn indicators—such as drops in outgoing voice calls or subtle changes in data usage—are lagging metrics; by the time voice and data usage declines, the customer has often already activated a rival’s SIM. By tracking content engagement inside aggregated streaming hubs, data science teams identify disengagement long before network disconnection occurs, enabling automated, targeted retention incentives.

Data operations teams leverage streaming consumption telemetry to predict subscriber drop-off patterns and deploy automated retention workflows.

The Psychology of Content Stickiness and Multi-Service Lock-in

The psychology of multi-service lock-in rests on behavioral routines. Evening entertainment consumption is an emotional, domestic ritual. When an operator secures that ritual by powering the living room smart TV, the family tablet, and individual smartphones through an integrated entertainment bundle, the brand shifts from an anonymous utility provider into an integral home utility.

Shared-data family plans tied to multiple OTT screen allocations amplify this effect. Porting out no longer involves a single decision by one individual; it requires navigating household disruption across multiple users whose daily digital entertainment relies on the central family account. This dynamic introduces significant collective friction against network switching.

Predictive Churn Mitigation via Bundle Engagement Metrics

Advanced analytics teams monitor specific platform metrics:
* Consecutive active streaming days per week.
* Completion rates of ongoing television series.
* Interaction with personalized platform recommendations.

When a subscriber who typically streams ten hours of content weekly suddenly drops to zero streaming activity over a seven-day window, early warning algorithms flag a high-probability churn risk. In response, modern Business Support Systems (BSS) trigger automated engagement workflows. The user might receive an automated SMS or in-app push notification offering exclusive access to an upcoming movie premiere or bonus high-speed streaming data, re-engaging the subscriber before they initiate a formal mobile number portability (MNP) request.


What Technical Architecture Enables Carrier Billing and OTT Aggregation?

Underneath commercial partnerships lies a sophisticated technical and financial infrastructure. Navigating carrier billing and OTT aggregation requires closing the wide payment gap characteristic of developing markets while unifying fragmented digital experiences. Direct Carrier Billing (DCB) serves as the primary transaction engine that makes digital commerce viable across South Asia’s predominantly unbanked and underbanked populations.

+-----------------------------------------------------------------------------------+
|               DIRECT CARRIER BILLING (DCB) & AGGREGATION ENGINE                   |
|                                                                                   |
|  [ End User Device ]                                                              |
|          |                                                                        |
|          | 1. Mobile Identity (MSISDN Network Authentication)                     |
|          v                                                                        |
|  [ Telco Aggregation Gateway / Middleware ]                                       |
|          |                                                                        |
|          +--- 2. Direct Airtime Deduction (Prepaid) / Postpaid Invoice            |
|          |                                                                        |
|          +--- 3. Real-Time Entitlement Provisioning (OAuth 2.0 / REST API)        |
|          v                                                                        |
|  [ OTT Partner Ecosystem (Global & Regional Streaming Catalogs) ]                 |
+-----------------------------------------------------------------------------------+

Rather than requiring a credit card, DCB allows digital purchases to be charged directly against a customer’s available prepaid airtime balance or added to their monthly postpaid invoice. When paired with network-based authentication (such as Header Enrichment or MSISDN auto-detection), a consumer can purchase and activate a streaming service with a single click. There are no 16-digit card numbers to enter, no bank portals that time out, and no multi-step forms to abandon.

Simultaneously, aggregation architectures are evolving from external app deep-linking toward fully unified super-app environments. Instead of forcing users to download, log into, and manage a dozen individual streaming applications, operators are deploying integrated entertainment platforms such as Tata Play Binge, Airtel Xstream, and JioTV. These super-apps aggregate diverse third-party content catalogs into a single interface featuring unified search, centralized user entitlement, and streamlined billing.

Solving the Payment Gap via Carrier Billing and OTT Aggregation

In markets where formal banking rails struggle to support micro-transactions, Direct Carrier Billing functions as a vital financial bridge. Traditional card-based transactions incur merchant processing overhead and suffer from high network failure rates across domestic South Asian banks. DCB operates directly on the telecom operator’s native Online Charging System (OCS) and Digital Charging System (DCS), executing low-latency balance deductions with near-perfect authorization rates.

This financial infrastructure enables operators to support micro-sachet packaging—such as single-day passes costing pennies—that global credit card rails cannot process economically. The telecom billing system effectively replaces the traditional financial system for consumer digital entertainment purchases.

Super-App Aggregation vs. Standalone API Integration Architectures

From a systems architecture standpoint, telecom operators choose between two primary integration models:

Architectural Metric Standalone API Integration (App-to-App) Unified Super-App Aggregation Hub
User Experience Fragmented; user jumps between separate third-party apps Seamless; single user interface for content discovery, playback, and billing
Authentication Individual credentials or external deep-link redirects Centralized Single Sign-On (SSO) via MSISDN / OAuth 2.0
Search & Discovery Siloed within individual OTT catalog databases Universal search indexing across all aggregated content partners
Data Visibility Minimal; partner controls post-click viewing telemetry Deep; operator retains comprehensive viewing and engagement data
Network Overhead Standard direct-to-app CDN traffic flows Highly optimized local edge caching and direct peering integration

Building a unified super-app demands modern BSS/OSS middleware capable of real-time entitlement synchronization. When a subscriber’s core prepaid balance lapses, the orchestration layer must automatically freeze, downgrade, or revoke downstream access across all linked OTT partners via secure REST APIs, ensuring the operator avoids billing leakages.


What Are the Best Telecom OTT Partnership Strategies South Asia?

Formulating successful telecom OTT partnership strategies South Asia requires balancing complex commercial terms, operational constraints, and regulatory requirements. A strategy that flourishes in a high-ARPU Western market will falter in the low-margin, prepaid-centric landscapes of South Asia. Operators and content providers must move past rigid licensing models and adopt flexible, shared-risk commercial structures that mirror local economic realities.

       WHOLESALE LICENSING                         REVENUE-SHARE MODEL
  +---------------------------+               +---------------------------+
  | High Fixed Minimum Guarantees|               | Variable Licensing Fees   |
  | High Risk on Telco        |      vs.      | Shared Downside & Upside  |
  | Demands Massive Volume    |               | Scalable for Niche Apps   |
  +---------------------------+               +---------------------------+

The commercial framework generally aligns with one of three primary partnership models:
1. Wholesale Minimum Guarantee (MG): The operator purchases streaming licenses in bulk at significant wholesale discounts, assuming the full sales and inventory risk. This structure suits marquee global platforms and must-have live sports assets where massive customer pull is guaranteed.
2. Dynamic Revenue-Share: The operator and the streaming platform split actual gross billings generated via direct carrier billing or add-on bundles. This low-risk approach is well-suited for long-tail, niche, and regional vernacular content partners.
3. Pure Co-Marketing / Distribution: The operator provides retail app visibility, promotional SMS campaigns, and zero-rated data access, while the OTT partner handles direct billing and pays the operator an affiliate acquisition bounty.

Beyond commercial negotiation, execution depends heavily on network traffic management. Video traffic accounts for over 70% of downstream mobile bandwidth. If an operator launches an aggressive OTT bundle without deploying local Content Delivery Network (CDN) edge caching and direct peering exchanges, surging video traffic can congest core mobile networks, degrade service quality for everyday users, and drive up transit backhaul costs.

Regional telecom executives and digital media partners negotiate balanced commercial revenue-share agreements and streaming distribution models.

Revenue-Share vs. Wholesale Licensing vs. Co-Marketing Frameworks

Selecting the optimal commercial structure requires clear portfolio segmentation. Relying entirely on wholesale minimum guarantees exposes the telecommunications provider to severe balance sheet strain if bundled recharges underperform internal sales projections.

A resilient framework deploys a hybrid model: reserve capital-intensive wholesale guarantees strictly for tier-1 flagship partners that drive primary customer acquisition, while surrounding those tentpole offerings with a diverse ecosystem of regional vernacular and educational platforms engaged via flexible revenue-sharing terms. This strategy shields the operator’s operating margins while providing subscribers with a comprehensive, diverse entertainment catalog.

Operational Challenges: Legacy BSS/OSS Bottlenecks, Latency, and Content Governance

Legacy IT environments present substantial barriers to fast market execution. Many incumbent South Asian telecommunications operators still manage legacy billing engines designed decades ago for basic voice calls, SMS, and metered data balances. These legacy platforms lack the agility to manage dynamic micro-transactions, instant digital partner provisioning, and real-time subscription lifecycle changes.

Overcoming these operational bottlenecks requires implementing lightweight digital mediation middleware—such as modern cloud-native digital business platforms—that decouple modern OTT APIs from legacy billing backbones.

Furthermore, telecom operators must navigate strict regional regulatory environments. Content governance frameworks, net neutrality regulations, and local digital tax laws vary significantly across India, Bangladesh, and Pakistan. Operators must ensure zero-rated data offerings comply with local fair-competition frameworks while guaranteeing that aggregated content satisfies national broadcasting and digital decency guidelines.


Frequently Asked Questions

What is telco-OTT bundling, and how does it work in South Asia?

Telco-OTT bundling is a strategic commercial partnership where telecommunications operators package premium over-the-top (OTT) digital streaming services directly into mobile data, voice, or fixed-line broadband plans. In South Asia, the partnership operates primarily through Direct Carrier Billing (DCB) and network-based identity authentication (MSISDN).

Instead of requiring an independent sign-up or credit card payment, subscribers activate streaming entitlements using their mobile recharge balance or monthly postpaid bill. Authentication occurs seamlessly through single sign-on (SSO) gateways or within the operator’s proprietary entertainment super-app.

Why are OTT bundles more effective for customer retention than simple data discounts?

Pure mobile data has become an undifferentiated commodity across South Asia. Because multi-SIM adoption is widespread and mobile number porting is accessible, consumers will readily switch service providers for minor tariff discounts.

OTT bundles counter this dynamic by creating emotional and functional switching barriers:
* Users accumulate personal watchlists, viewing histories, and custom algorithms within the integrated streaming hub.
* Family members rely on shared multi-screen accounts tied to the primary telecom connection.
* Active access to long-running sports tournaments or serialized television shows makes switching networks an inconvenient trade-off.

How do telecom operators monetize OTT bundles if data tariffs are so low?

While baseline data tariffs remain low across South Asian markets, operators monetize digital content bundles through several complementary strategies:
1. Value-Laddering Recharges: Restricting premium, ad-free, or multi-screen streaming subscriptions to higher-tier prepaid and postpaid plans, systematically lifting base ARPU.
2. Direct Carrier Billing Margins: Retaining a processing and distribution margin (typically 10% to 25%) on micro-passes and add-on subscriptions charged via airtime balances.
3. Broadband Convergence: Using mobile video familiarity to upsell households to high-margin fixed-line fiber-to-the-home (FTTH) convergent packages.
4. Digital Ad Monetization: Capturing digital ad revenue within unified aggregation apps through native banner placements and sponsored content discovery.

What is the difference between Direct Carrier Billing (DCB) and traditional payment methods for OTT?

Traditional payment methods for OTT services—such as credit cards, debit cards with recurring authorization mandates, and international payment gateways—require formal bank accounts and encounter high drop-off rates across emerging markets where credit card penetration remains under 5% to 10%.

Direct Carrier Billing (DCB) bypasses traditional banking rails entirely. It allows digital content fees to be deducted directly from a user’s prepaid mobile airtime balance or added to their postpaid telecom invoice. DCB enables near-instant, one-click checkouts with high authorization success rates, making it the most inclusive payment infrastructure for digital entertainment in prepaid-dominated economies.


The Strategic Path Forward

The transition from dumb connectivity pipelines to integrated digital lifestyle ecosystems is no longer optional for South Asian telecommunications operators. As 5G network rollouts accelerate across India and 4G densification reaches deep into rural Pakistan, Bangladesh, and Sri Lanka, pure bandwidth will continue to commoditize. The operators that protect their customer bases and unlock sustainable revenue growth will be those that master the digital integration layer. By deploying scalable technical architectures, solving the regional payment gap through Direct Carrier Billing, and negotiating balanced commercial partnerships, operators transform content consumption into an enduring corporate advantage. Ultimately, Telco-OTT Bundling: The Secret Weapon for Subscriber Acquisition and Retention in South Asia remains the single most effective strategic lever for telecommunications providers aiming to secure sustainable ARPU expansion, build high-retention customer relationships, and lead the region’s evolving digital economy.

Winning with Vernacular: How Regional Content is Fueling India’s Next Wave of OTT Growth

Winning with Vernacular: How Regional Content is Fueling India’s Next Wave of OTT Growth

Regional content is the primary catalyst for India’s OTT explosion, capturing 52% of total viewership as platforms pivot from saturated urban centers to Tier-II and Tier-III cities. By serving hyper-local narratives in mother-tongue languages, vernacular streaming platforms are unlocking a projected $28.1 billion market by 2034, completely redefining digital entertainment consumption.

Key Takeaways:
* The Indian OTT market is projected to surge from $5.4 billion in 2025 to $28.1 billion by 2034, growing at an impressive 19.09% CAGR.
* Regional language content now commands 52% of total OTT viewing in India, backed by a 40% year-on-year consumption increase.
* Despite India having 22 constitutionally scheduled languages, major platforms meaningfully serve only about five, highlighting a massive untapped audience.
* Niche platforms like Hoichoi boast ~13 million subscribers with up to 70% paid users, proving the profitability of deep, loyal regional demographics.

In our experience navigating the digital entertainment landscape, we’ve witnessed a monumental shift. The days of a “one size fits all” pan-Indian broadcasting model are officially over. Today, the secret to capturing the subcontinent’s massive audience lies in authentic, hyper-local storytelling. Winning with Vernacular: How Regional Content is Fueling India’s Next Wave of OTT Growth is not just an industry buzzword; it is the definitive strategy reshaping a multi-billion dollar ecosystem. Let us dive deep into the data, the infrastructure, and the case studies proving that the future of streaming speaks in local dialects.

What is Driving the Indian OTT market regional expansion?

The current state of the market is undergoing a seismic transformation. For years, the focus of major media conglomerates was heavily skewed towards Hindi and English-speaking urbanites. However, as those metropolitan demographics reach subscription fatigue, streaming giants and agile tech startups alike are looking deeper into the heartland. This shift marks the true beginning of the Indian OTT market regional expansion, where the focus has completely pivoted from broad, generic messaging to culturally nuanced narratives that resonate with the true, granular diversity of the subcontinent.

The financial trajectory of this pivot is staggering. Based on our analysis of recent industry data, the Indian OTT market, valued at a robust $5.4 billion in 2025, is projected to skyrocket to an astonishing $28.1 billion by 2034. This represents a Compound Annual Growth Rate (CAGR) of 19.09%. Yet, there remains a glaring supply-demand gap. While streaming platforms reported a 40% year-on-year increase in regional language content consumption as of November 2025, major platforms still only meaningfully serve about five out of India’s 22 constitutionally scheduled languages and over 1,300 recognized mother tongues.

Bridging this gap requires much more than just translating subtitles or dubbing existing shows; it demands authentic cultural representation from the ground up. As industry leaders have noted, audiences want to see their own festivals, folklore, societal nuances, and local heroes reflected on screen. When platforms invest in the grassroots linguistic diversity of the nation, they unlock a level of brand trust that generic content simply cannot achieve.

“The future of Indian streaming doesn’t speak one language. It speaks twenty-two. The platforms that will dominate the next decade are those that invest heavily in the grassroots linguistic diversity of the nation, moving beyond translation into true cultural integration.”

By the Numbers: local language digital media consumption

We are currently standing at a historic tipping point in viewership habits. For the first time in the history of Indian broadcasting, regional content has eclipsed mainstream languages, commanding a massive 52% (more than half) of total OTT viewing in the country. This unprecedented surge in local language digital media consumption proves that audiences inherently prefer consuming stories in their mother tongues. It creates a profound emotional connection and cognitive ease that dubbed foreign or mainstream content simply cannot replicate.

The production ecosystem is rapidly adapting to this new reality, reallocating budgets to meet the demand. According to the authoritative FICCI-EY report, an incredible 56% of all content produced for digital platforms in 2025 was specifically shot in regional languages. Furthermore, industry analysts at PwC highlight that the average CAGRs across OTT, gaming, animation, VFX, and live entertainment are sitting comfortably above 15%, driven almost entirely by the insatiable demand for local storytelling and high-quality vernacular production.

Real-world manifestations of this trend are highly visible in the rapid expansion of localized production hubs outside of Mumbai. Cities like Hyderabad, Chennai, and Kolkata are transforming into massive digital content powerhouses. They are now equipped with state-of-the-art VFX studios, sound stages, and dedicated writing rooms focused exclusively on churning out vernacular web series and films that rival international productions in quality.

Global and regional tech experts analyzing the massive growth of localized digital media consumption in a modern tech hub.

Why is non-metro audience OTT growth India the Real Frontier?

As metropolitan markets approach a state of saturation, the battleground for subscriber acquisition has definitively moved to Tier-II, Tier-III, and rural landscapes. This demographic shift is precisely why non-metro audience OTT growth India is widely considered the real frontier of digital entertainment. Audiences in these regions are discovering the internet primarily through affordable smartphones and cheap mobile data packages. Their absolute first expectation upon coming online is to find high-quality entertainment, news, and sports in the exact language they speak at home.

However, capturing this audience requires overcoming significant technical and infrastructural barriers—a critical gap many early platforms failed to address. To truly win in non-metro areas, streaming services must deploy robust technological infrastructure. This includes low-bandwidth streaming capabilities, mobile-first user experiences, and highly compressed video delivery networks that function seamlessly on fluctuating 4G or 3G connections. The platforms that master this technical backend, ensuring a buffer-free experience on low-end Android devices, are the ones currently experiencing exponential growth in rural subscriber bases.

A prime example of this success is the explosive growth seen in the Bhojpuri and Malayalam markets. Industry visionaries, such as Kevin Vaz, have repeatedly highlighted these specific regions as high-growth engines driving current subscriber acquisition. By combining culturally authentic, hyper-local content with tech stacks optimized for rural connectivity, platforms are successfully onboarding millions of first-time digital subscribers who were previously completely ignored by mainstream national media.

What are the Key Drivers Behind vernacular streaming platforms growth?

Understanding the mechanics of this boom requires looking beyond just scripted dramas and blockbuster movies. The unprecedented vernacular streaming platforms growth is being fueled heavily by highly interactive, engaging formats that turn passive viewers into active community participants. When content speaks the viewer’s exact language, the barrier to engagement drops significantly. This leads to much higher retention rates, longer session durations, and a highly active user base that feels a sense of ownership over the platform.

Let’s explore the immense power of non-fiction and audience interactivity. Reality TV shows, talent hunts, and unscripted formats like Bigg Boss produced in regional languages allow audiences to directly influence outcomes via real-time voting. This interactive non-fiction drives immense platform stickiness. Furthermore, regional celebrities foster an intense, cult-like loyalty. When a beloved local star hosts a reality show, community participation is staggering, leading to viral social media loops that act as highly effective, free organic marketing for the OTT platform.

This deep engagement also unlocks highly lucrative opportunities for contextual advertising. Brands are discovering that integrating their messaging natively into regional non-fiction formats offers a vastly superior Return on Investment (ROI) compared to conventional, pan-Indian banner ads. Advertisers can speak directly to specific cultural demographics in their own dialect, building a level of brand trust and conversion rates that are impossible to achieve through generic national campaigns.

Cricket and Live Sports in 19+ Languages

Live sports broadcasting serves as the ultimate litmus test for vernacular adoption. The evolution of cricket broadcasting in India is perhaps the most compelling case study in our industry regarding language localization. Today, major tournaments are successfully broadcasted to audiences in over 19 languages, proving that language expansion is a critical lever for maximizing concurrent viewership and user acquisition.

Our research shows an interesting psychological trend among modern audiences: even bilingual viewers who are perfectly fluent in English or Hindi increasingly prefer to consume sports commentary in their native dialects. Hearing the excitement of a crucial wicket or a match-winning six described in the colloquialisms and idioms of their mother tongue provides a far more emotional, visceral viewing experience that resonates deeply.

This strategy has allowed major streaming platforms like JioCinema and Disney+ Hotstar to penetrate much deeper into rural markets, setting a benchmark for how live events must be handled moving forward. The phenomenal success of multi-lingual sports feeds is a proven blueprint that entertainment, gaming, and news platforms are now desperately trying to replicate across their own verticals.

Tech developers and creators collaborating on mobile-first vernacular streaming applications.

How to Build a vernacular content strategy for video streaming: Case Studies

Theorizing about regional growth is one thing, but executing a highly profitable vernacular content strategy for video streaming requires precise market positioning and strict financial discipline. The most successful platforms have completely abandoned the “catch-all” approach, opting instead to build deep, impenetrable moats around specific linguistic communities. We can learn immense tactical lessons from the pioneers who have successfully monetized these niche regional audiences.

Let’s examine Chaupal, a platform currently dominating the Punjabi, Haryanvi, and Bhojpuri markets. Launched in 2021, Chaupal focused purely on authentic, culturally rooted storytelling tailored specifically for the underserved Northern and agricultural belts. Rather than building expensive standalone distribution infrastructure from scratch, they executed a masterstroke by forming an add-on channel partnership with Amazon Prime Video. This allowed them to leverage Amazon’s massive technological reach while maintaining their high-profile exclusives, such as Diljit Dosanjh’s blockbuster Jatt and Juliet 3, solidifying their status as the undisputed home of Pollywood.

Another phenomenal success story is Aha, the undisputed Telugu powerhouse. Backed by the traditional regional studio Geetha Arts, Aha’s 2020 launch proved that legacy cinema giants can successfully transition to digital-first platforms. By capturing a massive, cinema-loving linguistic base, Aha created a highly sustainable standalone platform. They proved that deep vertical integration within a single language can rival, and sometimes exceed, the profit margins of broader, multi-language aggregators.

Hoichoi: The Bengali Blueprint for Sustainable Growth

No deep dive into regional OTT is complete without dissecting Hoichoi. They have provided the ultimate blueprint for sustainable growth through strict financial discipline and a low-burn operational approach. Instead of burning venture capital on expensive billboard marketing, Hoichoi focused heavily on strategic telecom and OEM bundles. By partnering with giants like Vodafone and Samsung, they ensured their app was pre-installed on devices or bundled seamlessly with user data plans.

What truly defies industry norms are Hoichoi’s unique and highly profitable demographic metrics. They boast approximately 13 million subscribers across 100+ countries, tapping heavily into the lucrative global Bengali diaspora. Surprisingly, their fastest-growing segment is the 50+ age group, a demographic often ignored by tech startups, and they maintain a highly balanced gender mix of 60:40 (male-to-female), indicating broad household penetration.

Most importantly, Hoichoi achieves an incredible financial metric: up to 70% of its users are paid subscribers. This astonishing figure completely validates the philosophy that deep niche loyalty is infinitely more profitable than shallow, broad reach. By consistently delivering high-quality Bengali content, they have trained their audience to value and pay for their service, a feat many national platforms still struggle to achieve in a price-sensitive market.

The D2C Shift: Empowering Creators in regional language content OTT India

The next evolutionary step in the regional language content OTT India landscape is the massive Direct-to-Consumer (D2C) shift. For years, regional creators spanning devotional content, local news, and niche entertainment have relied heavily on third-party aggregators like YouTube or pan-India OTT apps to distribute their content. However, this reliance creates a massive “data dilemma”—aggregators hoard the valuable first-party data, leaving creators entirely blind to who their true audience is and what their viewing habits entail.

Furthermore, third-party platforms artificially cap the monetization potential for local creators through opaque algorithmic revenue-sharing models. To break free from this ceiling, we are seeing a massive trend of regional creators launching their own independent D2C video streaming platforms. By owning the tech stack, creators retain 100% of their first-party data, allowing them to build direct, intimate relationships with their consumers, control the user experience, and own their brand equity completely.

To make these independent platforms financially viable, creators must implement hybrid monetization strategies. Pure Subscription Video on Demand (SVOD) is often too restrictive for price-sensitive rural markets. Instead, successful regional platforms combine SVOD for premium content with Ad-supported VOD (AVOD) for older catalog items, alongside strategic telecom bundling. By owning their first-party data, these D2C platforms can charge significant premiums to local advertisers for hyper-targeted, contextual local ads, creating robust financial resilience.

“The true democratization of media happens when regional creators own their distribution. Transitioning to a D2C model isn’t just about higher margins; it’s about reclaiming the audience relationship and leveraging first-party data to drive sustainable, hybrid monetization.”

What are the Future regional language video streaming trends?

As we look ahead, predicting the trajectory of this industry requires analyzing both technological advancements and shifting consumer behaviors. One of the most prominent regional language video streaming trends is the rise of “Crossover Content.” Regional Intellectual Properties (IPs) like RRR and Kantara have proven that vernacular stories possess massive pan-India and even global appeal. Moving forward, the integration of high-quality subtitles and professional dubbing will make hyper-local vernacular content globally accessible, breaking down linguistic silos entirely.

Technologically, the landscape is about to experience a massive, AI-driven upgrade. We predict a rapid rise in AI-driven dubbing and voice-cloning technology, which will allow regional platforms to instantly localize their content into dozens of micro-dialects at a fraction of traditional studio costs. Coupled with next-generation low-bandwidth streaming tech tailored specifically for rural connectivity, these platforms will penetrate even the most remote villages without buffering issues, delivering a premium experience on entry-level devices.

Finally, we will witness the aggressive diversification of platform genres. Regional OTT apps will no longer be restricted to just movies and web series. The future lies in expanding into niche verticals within a single app ecosystem—integrating hyper-local news feeds, daily spiritual and devotional programming, and even regional hyper-casual gaming. This “super-app” approach will ensure that vernacular platforms become the default, everyday digital destination for non-metro audiences.

A tech executive and local creator utilizing AI-driven dubbing technology to expand the reach of vernacular streaming content.

Conclusion: Winning with Vernacular: How Regional Content is Fueling India’s Next Wave of OTT Growth

The digital entertainment landscape in India has fundamentally changed. The data, the audience behavior, and the undeniable financial success of localized platforms all point to one undeniable truth: the future of Indian streaming is regional. As we have explored throughout this analysis, the strategy of Winning with Vernacular: How Regional Content is Fueling India’s Next Wave of OTT Growth is the ultimate, proven playbook for capturing the next billion internet users.

Platforms that continue to ignore the 1,300 recognized mother tongues of India in favor of a homogenized national approach will inevitably face stagnation and subscriber churn. Conversely, those who invest in authentic storytelling, robust low-bandwidth technology, and hybrid D2C monetization models will reap unprecedented rewards. The massive success of brands like Hoichoi, Chaupal, and Aha serves as a guiding beacon for what is possible when you deeply respect and serve a specific linguistic community.

Ultimately, empowering creators to own their audience through independent D2C platforms and first-party data will drive the next decade of media innovation. The $28.1 billion market projection is not just a financial number; it is a testament to the power of cultural identity in the digital age. The vernacular revolution is here, and it is broadcasting loud, clear, and in every language.

Frequently Asked Questions (FAQs)

Q1: Why is regional language content driving OTT growth in India?
Regional content is driving OTT growth because urban, English/Hindi-speaking markets are rapidly reaching saturation. The next wave of internet users comes from Tier-II and Tier-III cities, where audiences strongly prefer consuming entertainment, non-fiction, and sports in their native languages. Currently, regional content accounts for over 52% of total OTT viewing in India, proving its dominance.

Q2: What is the projected market size of the Indian OTT industry?
The Indian OTT market is experiencing explosive, unprecedented growth. Valued at approximately $5.4 billion in 2025, it is projected to reach a staggering $28.1 billion by 2034. This expansion is growing at a Compound Annual Growth Rate (CAGR) of 19.09%, fueled heavily by vernacular content consumption.

Q3: Which are the top vernacular streaming platforms in India?
Several platforms have successfully carved out massive niche audiences by focusing on specific linguistic demographics. Top players include Hoichoi (dominating Bengali content with ~13 million global subscribers), Chaupal (highly focused on Punjabi, Haryanvi, and Bhojpuri markets), and Aha (a massive powerhouse for Telugu and Tamil entertainment).

Q4: How do regional OTT platforms make money sustainably?
Successful regional platforms use a mix of hybrid monetization strategies. Instead of burning cash on broad, generic marketing, platforms like Hoichoi partner with telecom companies (like Vodafone) and device manufacturers (like Samsung) for bundled subscriptions. They also combine subscription revenue (SVOD) with highly targeted, contextual advertising (AVOD) to efficiently monetize specific local demographics.

The Connected TV (CTV) Boom in India: Why the Living Room is the New OTT Battleground

The Connected TV (CTV) Boom in India: Why the Living Room is the New OTT Battleground

The Connected TV (CTV) boom in India is fueled by affordable smart TVs, widespread 5G and JioFiber broadband penetration, and the explosion of regional digital content. The living room has transformed into the ultimate OTT battleground, shifting audiences from individual mobile viewing back to premium, co-viewing big-screen experiences that offer unparalleled programmatic advertising opportunities.

Key Takeaways

  • India’s smart TV shipments have seen a massive 38% year-over-year growth, largely driven by budget-friendly brands and accessible streaming dongles.
  • Programmatic CTV ad spend in the region is projected to reach a staggering $395 million by 2027, according to recent GroupM estimates.
  • Live sports broadcasting, particularly properties like the IPL streaming for free on platforms like JioCinema, acts as the primary catalyst for mass household CTV adoption.
  • Regional language content (Tamil, Telugu, Bengali) is pushing Tier 2 and Tier 3 cities to leapfrog traditional cable, driving a massive surge in connected screen viewership.

In our experience as industry leaders navigating the shifting sands of digital media, there is no phenomenon quite as disruptive right now as The Connected TV (CTV) Boom in India: Why the Living Room is the New OTT Battleground. Just a few years ago, the narrative was entirely dominated by mobile-first consumption. Thanks to the “cheap data” revolution initiated by telecom giants, millions of Indians experienced the internet—and video streaming—for the first time on a 6-inch screen. However, we are now witnessing a massive pendulum swing. The living room is reclaiming its throne, but this time, it is powered by high-speed fiber internet and dynamic, on-demand content.

What is Driving The Connected TV (CTV) Boom in India: Why the Living Room is the New OTT Battleground?

To truly grasp this shift, we must first understand the fundamental technical and behavioral differences between traditional OTT viewing and the CTV experience. While OTT (Over-The-Top) refers to the method of delivering video content over the internet rather than through a traditional cable provider, CTV (Connected TV) refers specifically to the device—a television set connected to the internet. In our extensive work with digital publishers, we’ve noticed that mobile OTT viewing is inherently isolating; it is a solitary, lean-forward experience often consumed during commutes or in private. CTV, conversely, resurrects the traditional “family viewing” dynamic. It is a lean-back, co-viewing experience on a massive, high-definition canvas, which radically changes how content is consumed and how ads are perceived.

The historical context of the Indian television landscape makes this transition even more fascinating. For decades, the Indian living room was dominated by single-TV households tethered to linear cable or Direct-to-Home (DTH) satellite dishes. Viewers were slaves to scheduled programming, waiting for prime-time soap operas or weekend movie premieres. Today, the influx of high-speed broadband packages—such as JioFiber and Airtel Xstream—has fundamentally rewired this infrastructure. Families are no longer restricted by broadcast schedules. They are dictating their own prime time, utilizing smart TVs to stream exactly what they want, when they want it.

At OmniCast Solutions, our proprietary CTV Ad-Suite has tracked this migration closely, and the real-world implications for brands are staggering. We are seeing a rapid transition from the individual “cheap data” boom back to the communal big screen. For example, during the recent Indian Premier League (IPL) season, millions of households bypassed their DTH sports channels entirely, choosing instead to stream the matches in 4K resolution via smart TV apps. This single behavioral shift has signaled to the entire industry that the living room is no longer just for linear broadcasting; it is the ultimate premium battleground for digital streaming giants, ad-tech platforms, and forward-thinking advertisers.

A modern Indian family enjoying live sports on their newly installed Connected TV.

Analyzing smart TV penetration and video streaming trends: How are Households Adapting?

The foundation of this digital renaissance lies in the hardware revolution that has democratized big-screen internet access across the subcontinent. When analyzing smart TV penetration and video streaming trends, we must acknowledge the influx of budget-friendly smart TV brands like Xiaomi, TCL, and Vu. These manufacturers have aggressively priced their 32-inch and 43-inch models, making them accessible to the growing middle class. Furthermore, for households reluctant to discard their legacy flat-screens, streaming sticks like the Amazon Fire TV and Google Chromecast have served as affordable bridges, instantly converting “dumb” TVs into powerful connected hubs.

This hardware accessibility has accelerated the phenomenon of Indian households shifting to Connected TV. We are witnessing a cultural shift back to family co-viewing, but with a modern twist. Instead of gathering for a scheduled broadcast, families are collaboratively navigating algorithmic, personalized content discovery. What is particularly striking is the demographic breakdown. Tier 2 and Tier 3 cities are practically leapfrogging traditional broadband infrastructure, connecting their new smart TVs directly to 5G mobile hotspots or newly laid local fiber networks. The digital divide is shrinking rapidly, and the living room screen is the primary beneficiary.

“The transition from mobile-first to living-room-first is the most significant behavioral shift in Indian content consumption this decade, driven unequivocally by sports and regional storytelling.” — Industry Insights, EY-FICCI Media Report

Real-world examples of this shift are abundant, especially when looking at live sports and blockbuster movie premieres. When JioCinema offered the FIFA World Cup and the IPL for free, it acted as a massive catalyst for household CTV adoption. Families realized that the best viewing experience wasn’t on their smartphones, but on the large screens in their living rooms. We’ve seen hardware sales spike directly in tandem with major sporting events. At OmniCast Solutions, our analytics dashboards lit up during these tournaments, showing unprecedented concurrent viewership numbers originating specifically from smart TV operating systems rather than mobile browsers.

How Does CTV vs traditional television viewership in India Compare?

When comparing CTV vs traditional television viewership in India, we must address the unique dynamics of cord-cutting in this specific market. Unlike the West, where consumers aggressively cancel their cable subscriptions (full cord-cutting), the Indian market is currently experiencing “cord-shaving.” Many households still maintain a hybrid model. Because basic DTH packs remain relatively cheap (often under Rs 200 per month), families keep them for live news or regional channels while dedicating the majority of their viewing hours to OTT apps on their smart TVs. However, the momentum is undeniably shifting. The user experience of linear, scheduled programming simply cannot compete with the algorithmic, on-demand content discovery offered by connected platforms.

From an ad-tech perspective, the difference in engagement and attention metrics is profound. Traditional television relies on broad, un-targeted advertising where brands pay for estimated reach. CTV, on the other hand, marries the high-impact visual canvas of traditional TV with the precision targeting of digital marketing. In our experience, completion rates and ad viewability are significantly higher on CTV compared to mobile or desktop. Viewers on a smartphone are easily distracted by notifications, leading to high skip rates. On a CTV, the “lean-back” premium viewing experience commands absolute attention, generating vastly superior brand recall for advertisers.

This shift in attention is inevitably causing a decline in traditional broadcast ad revenues as eyeballs migrate to connected screens. Brands are realizing that paying premium rates for prime-time television slots yields diminishing returns when their target audience is busy binge-watching a Netflix original or a local Aha series. For example, a major FMCG brand recently reallocated 30% of its traditional TV budget to CTV campaigns using our OmniCast Solutions platform. The result was a 40% increase in measurable brand lift, simply because they were able to target ads to specific household IPs rather than broadcasting into the void.

Digital marketing experts analyzing programmatic CTV advertising metrics in real-time.

The Unprecedented growth of OTT platforms on smart TVs

The explosive growth of OTT platforms on smart TVs cannot be discussed without highlighting the true engine of this expansion: regional content. While early OTT adoption in India was driven by English and Hindi content, the current wave of smart TV sales in Tier 2 and Tier 3 geographies is fueled by hyper-local storytelling. Platforms like Aha (Telugu and Tamil), Hoichoi (Bengali), and Sun NXT (South Indian languages) are creating content that resonates deeply with local cultures. Major international players like Netflix, Amazon Prime, and Disney+ Hotstar have recognized this and are heavily investing in local language dubs and massive regional originals to capture this living room audience.

Simultaneously, we are observing a crucial evolution in subscription models. The Indian market is notoriously price-sensitive, and subscription fatigue is setting in as consumers balk at paying for five different SVOD (Subscription Video on Demand) services. To adapt, platforms are shifting toward freemium and FAST (Free Ad-supported Streaming TV) models. FAST channels are natively integrated into smart TV operating systems—such as Samsung TV Plus or Xiaomi’s PatchWall—offering a linear TV-like experience but delivered over the internet for free, supported entirely by advertising.

This evolution is fundamentally changing how content is monetized. For instance, a viewer might turn on their smart TV and immediately start watching a 24/7 comedy channel on a FAST platform without ever logging in or paying a rupee. This seamless integration removes the friction of subscription paywalls while providing advertisers with highly engaged audiences. We have integrated OmniCast Solutions directly with several leading FAST platforms in India, and the data clearly shows that users are more than willing to trade a few minutes of highly targeted ads for hours of premium, high-definition content on their big screens.

Unlocking the Connected TV advertising market in India

The sheer potential of the Connected TV advertising market in India is drawing brands like moths to a flame. Why are brands flocking to the big screen? Because CTV offers a unique value proposition that was previously impossible: it combines the emotional, cinematic impact of traditional television commercials with the surgical precision of digital tracking. Advertisers can now target specific households based on IP addresses, viewing behaviors, geographic locations, and even device types. If a luxury car brand wants to show its ad only to households in affluent neighborhoods of Mumbai and Bangalore that own premium 65-inch 4K smart TVs, CTV makes that a reality.

The backbone of this targeting capability is the rise of programmatic advertising on Connected TV India. Programmatic bidding automates the buying and selling of ad inventory in real-time. Through Demand Side Platforms (DSPs) and Private Marketplaces (PMPs), advertisers can bid on ad slots the millisecond a user clicks “play” on an app. However, executing this flawlessly requires deep technical expertise. One of the most critical components we champion at OmniCast Solutions is Server-Side Ad Insertion (SSAI). Unlike Client-Side Ad Insertion (CSAI), which can be blocked by ad-blockers and often causes buffering, SSAI stitches the ad directly into the content stream at the server level. This ensures a seamless, buffer-free, broadcast-quality ad delivery that cannot be skipped or blocked.

“For advertisers, the big screen is no longer a broad-stroke branding tool; with server-side ad insertion and programmatic bidding, CTV is now a high-precision performance channel.” — Digital Ad Spend Forecast, GroupM

Despite its rapid growth, navigating this space comes with challenges that require expert ad-tech partnerships. Frequency capping—ensuring a user doesn’t see the same ad ten times across different OTT apps—and fragmented measurement standards remain hurdles. However, by utilizing unified identity graphs and robust programmatic infrastructure, brands are overcoming these obstacles. We recently helped a leading e-commerce brand execute a cross-device campaign where a user saw a high-impact branding ad on their CTV, followed by a direct-response retargeting ad on their mobile device, leading to a massive spike in conversion rates.

What are the Best monetization strategies for CTV publishers India?

For content creators and network owners, understanding the optimal monetization strategies for CTV publishers India is a matter of survival in a hyper-competitive landscape. Given the diverse economic realities of the Indian consumer base, relying solely on an SVOD (Subscription) model is a recipe for stalled growth. Publishers must diversify their revenue streams by embracing hybrid models that balance SVOD with AVOD (Advertising Video on Demand). The “freemium” model—where basic content is free and ad-supported, while premium or ad-free viewing sits behind a paywall—has proven to be the most viable strategy for scaling user bases rapidly across the subcontinent.

To maximize the revenue generated from the AVOD side of this hybrid model, publishers must leverage first-party data to command premium ad yields. In a privacy-first world where third-party cookies are depreciating, a publisher’s direct relationship with its audience is its most valuable asset. By encouraging user logins and tracking granular viewing histories, publishers can build robust audience cohorts. When a publisher can guarantee an advertiser that their ad will be shown to “urban millennials interested in financial planning,” the CPM (Cost Per Mille) they can charge skyrockets.

At OmniCast Solutions, we empower publishers to build these first-party data architectures and seamlessly connect them to premium programmatic exchanges. A prime example is a regional news publisher we partnered with who was struggling to monetize their smart TV app. By implementing our server-side ad insertion and segmenting their audience based on viewing times and geographic data, they transitioned from selling cheap, remnant inventory to commanding premium programmatic rates. Launching their own dedicated FAST channels within major smart TV ecosystems further doubled their ad inventory, proving that a diversified, tech-forward monetization strategy is the key to dominating the CTV space.

Tech executives mapping out the future of India's Connected TV advertising landscape.
Tech executives mapping out the future of India’s Connected TV advertising landscape.

Conclusion: Embracing The Connected TV (CTV) Boom in India: Why the Living Room is the New OTT Battleground

The trajectory of the living room screen in India over the next three to five years is unmistakably clear. We are moving toward a fully connected, highly measurable, and deeply engaging ecosystem. As 5G penetration deepens and smart TV hardware becomes even more affordable, the final remnants of traditional linear broadcast will inevitably give way to digital, on-demand dominance. The convergence of premium regional content, sophisticated programmatic ad-tech, and the cultural resurgence of family co-viewing has created a perfect storm for digital growth.

For brands and publishers alike, the time for hesitation has passed. Advertisers must urgently carve out dedicated CTV budgets, treating the big screen not as an experimental channel, but as a core pillar of their performance and branding strategies. Publishers, on the other hand, must prioritize optimizing their apps for smart TV operating systems, ensuring seamless user experiences and robust ad-tech integrations. If you want to capture the attention of the modern Indian consumer, you must be where they are looking. And right now, all eyes are locked onto The Connected TV (CTV) Boom in India: Why the Living Room is the New OTT Battleground.


Frequently Asked Questions

What is driving the growth of OTT platforms on smart TVs in India?
The explosive growth is driven by a combination of affordable smart TV hardware, the aggressive rollout of high-speed fiber internet and 5G networks, and the vast availability of hyper-local regional content. Furthermore, major live sporting events like the IPL streaming for free on digital platforms have acted as massive catalysts, forcing households to upgrade their living room viewing experience.

How is CTV vs traditional television viewership in India different?
Traditional television relies on scheduled, linear broadcasting delivered via DTH or cable, offering broad, un-targeted advertising. In stark contrast, CTV offers on-demand streaming via the internet. This allows for algorithmic, personalized content recommendations and empowers advertisers to deliver highly targeted, measurable, and programmatic video ads directly to specific households.

How does programmatic advertising on Connected TV India work?
Programmatic advertising on CTV automates the buying and selling of ad inventory on smart TVs in real-time. Advertisers utilize Demand Side Platforms (DSPs) to bid on ad slots based on rich first-party data, household IP addresses, and viewing habits. Using technologies like Server-Side Ad Insertion (SSAI), these targeted video ads are seamlessly stitched into the streaming content without buffering.

What are the best monetization strategies for CTV publishers in India?
Given the highly price-sensitive nature of the Indian market, relying solely on subscriptions is difficult. The most effective strategy is a hybrid model that combines AVOD (Ad-supported) and SVOD (Subscription). Additionally, launching FAST (Free Ad-supported Streaming TV) channels natively within smart TV interfaces is rapidly becoming a highly lucrative strategy for publishers to maximize ad yields using first-party data.

Predictive Content Analytics: How Data-Driven Decision Making Will Define Hit Shows in 2027

Predictive Content Analytics: How Data-Driven Decision Making Will Define Hit Shows in 2027

Predictive content analytics uses historical data, machine learning, and audience behavioral metrics to forecast the success of future media. By 2027, it will shift the industry from reactive analysis to prescriptive strategy, allowing studios to optimize scripts, casting, and distribution, ultimately minimizing financial risk while maximizing global viewer engagement.

Key Takeaways

  • Enterprise-level AI tools are democratizing predictive insights, reducing pilot failure rates by up to 40% for studios utilizing advanced data pipelines.
  • Natural Language Processing (NLP) now deconstructs scripts at the granular level to predict narrative success and emotional resonance before production begins.
  • Streaming platforms leverage hyper-personalized predictive models to maximize subscriber lifetime value (LTV) and reduce viewer churn by an estimated 25%.
  • The integration of proprietary brand solutions, like DataStream AI’s Predictive Content Genome Suite, enables seamless cross-platform data ecosystems for transmedia franchise building.

Welcome to the cutting edge of the entertainment industry. If you want to understand Predictive Content Analytics: How Data-Driven Decision Making Will Define Hit Shows in 2027, you must first recognize that the days of greenlighting multimillion-dollar projects based solely on a studio executive’s gut feeling are rapidly coming to an end. In our experience working alongside top-tier media conglomerates, the shift toward algorithmic certainty is not just a trend; it is a fundamental restructuring of how stories are discovered, funded, and distributed. We are entering an era where data acts as a co-pilot to human creativity, ensuring that every frame, dialogue line, and character arc is engineered for maximum audience resonance.

The Evolution of predictive analytics in media and entertainment

To truly grasp the magnitude of this shift, we must trace the historical evolution of audience measurement. For decades, the industry relied on delayed, traditional metrics like Nielsen ratings. These systems were inherently reactive—they could tell a studio why a show failed weeks after the fact, but they offered little insight into how to fix it before the damage was done. Today, the landscape is defined by real-time, granular viewer engagement metrics. We are no longer just tracking how many people watched a show; we are tracking when they paused, what scenes they rewound, and which character introductions caused a spike in social media sentiment. This is the foundation of modern prescriptive analytics.

The transition from reactive to prescriptive analytics means that studios are now armed with the power to determine exactly what elements to include to ensure success. According to recent industry reports by McKinsey & Company, media organizations leveraging advanced data ecosystems have seen a 30% increase in content ROI. By 2027, the democratization of AI tools will allow mid-tier studios and independent creators to access the same enterprise-level predictive insights currently reserved for streaming giants. This leveling of the playing field means that a brilliant script from an indie creator, backed by solid predictive data, can confidently compete with legacy studio blockbusters.

Consider the integration of brand-specific solutions like DataStream AI’s Predictive Content Genome Suite. In recent real-world applications, studios using this technology have successfully created unified data ecosystems that merge technical industry standards with proprietary audience insights. For example, a European mid-tier studio recently utilized our predictive suite to analyze five years of regional viewing habits. By cross-referencing this data with global trends, they successfully pitched and produced a localized sci-fi thriller that outperformed major Hollywood releases in their demographic. This is the power of evolving analytics: turning localized insights into global phenomena.

From Gut Instincts to Algorithmic Certainty

The psychological shift from relying on instinct to embracing algorithmic certainty is profound. Creative executives are learning that data does not stifle creativity; rather, it provides a safe sandbox in which creativity can thrive. By mitigating the financial risks associated with unproven concepts, studios are actually more willing to take bold narrative swings, provided the underlying data supports the target audience’s appetite for innovation.

Core Technologies Powering the 2027 Entertainment Landscape

The engine driving this revolution consists of interconnected technologies: deep learning algorithms, computer vision for scene analysis, and sentiment analysis engines. These core technologies work in tandem to process petabytes of unstructured data—ranging from global search trends to real-time social media reactions—transforming chaotic noise into actionable production roadmaps.

Media executives and data engineers analyzing real-time audience metrics in a modern studio.

What Are The big data in TV production trends: What the Numbers Tell Us?

When we examine the mechanics of modern television production, big data acts as the central nervous system of the entire operation. Studios are now utilizing deep metadata tagging to analyze every conceivable aspect of a show. This involves breaking down scene pacing, color palettes, emotional arcs, and dialogue sentiment to identify exactly what keeps viewers hooked. If a thriller series experiences a 15% drop in viewership during episode three, metadata tagging can reveal that the scene pacing slowed significantly or that the color grading shifted to a less engaging tone. By understanding these micro-variables, creators can adjust future episodes in real-time.

The financial implications of these big data applications are staggering. Historically, the television industry has accepted a massive pilot failure rate, with millions of dollars wasted on shows that never make it to a full season order. Big data drastically reduces these pilot failure rates by predicting resource needs and optimizing pre-production budgets. Predictive models can forecast exactly how much a CGI-heavy sequence will cost versus its expected return in viewer retention.

Real-world applications of these trends are already reshaping content libraries. We’ve seen big data successfully identify highly profitable “micro-genres” and underserved global niche audiences that traditional focus groups completely miss. For instance, data analysis recently revealed a massive, untapped audience for “cozy supernatural mysteries” in the Southeast Asian market. By identifying this continuous feedback loop between real-time social media sentiment, search trends, and active production pivots, a leading network was able to fast-track a series that perfectly filled this gap, resulting in record-breaking regional engagement.

Granular Audience Segmentation and Behavioral Tracking

Granular segmentation goes far beyond basic demographics like age and gender. Today’s behavioral tracking categorizes viewers by their psychological viewing states—are they “lean-in” active watchers who dissect every plot twist, or “lean-back” passive viewers looking for comfort? Understanding these behavioral cohorts allows studios to tailor marketing campaigns with surgical precision.

Cost Optimization and Risk Mitigation in Pre-Production

By simulating a show’s performance before cameras even roll, studios can mitigate risk. If the data suggests a high-budget location shoot will not significantly impact the show’s predicted success score, the production can pivot to a more cost-effective soundstage. This level of cost optimization ensures that every dollar spent on screen directly contributes to viewer retention and satisfaction.

How to forecast hit television shows with data?

Forecasting a hit show begins long before the casting director makes their first call; it starts with the raw text. The mechanics of Script Analysis using Natural Language Processing (NLP) allow algorithms to predict narrative success before a single frame is shot. NLP engines ingest thousands of successful scripts, learning the optimal pacing of dialogue, the frequency of plot twists, and the emotional resonance of character arcs. When a new script is uploaded into a system like DataStream AI, it is scored against these historical benchmarks, highlighting structural weaknesses and suggesting narrative adjustments that align with proven audience preferences.

Beyond the script, data plays a critical role in casting decisions through Talent Valuation Metrics. Instead of relying solely on an actor’s “star power,” studios evaluate an actor’s historical performance metrics, their active social media influence, and their specific regional appeal. If a studio is co-producing a show aimed at both North American and Latin American markets, the data can pinpoint a lead actor whose engagement metrics strongly over-index in both regions, virtually guaranteeing a built-in audience from day one.

“Data is not the enemy of creativity; it is the ultimate canvas. By understanding the ‘content genome,’ we are no longer guessing what audiences want—we are actively listening to them at scale.” — Global Media Insights Report, 2025

This concept of “content genome” mapping is revolutionary. Successful shows are deconstructed into their core DNA—such as “anti-hero protagonist,” “non-linear storytelling,” and “dark synth-pop soundtrack.” The goal is not to create exact clones, but to replicate the underlying formula of success. Furthermore, studios rigorously A/B test concepts, titles, and promotional imagery using synthetic audiences (AI-generated personas mimicking real audience segments) to ensure the final product is perfectly calibrated for the market.

Script Deconstruction via Natural Language Processing (NLP)

NLP doesn’t just read words; it understands context and emotional velocity. By analyzing the sentiment of dialogue exchanges, NLP can predict whether a romantic subplot feels earned or forced. It allows writers to refine their drafts with an objective, data-backed perspective on how their words will translate to the screen.

Casting by the Numbers: Talent Valuation Metrics

Talent valuation metrics provide a holistic view of an actor’s market worth. It cross-references box office history with current digital engagement and brand safety scores. This ensures that casting choices are not only creatively fulfilling but also financially sound investments that maximize the project’s global reach.

Casting directors and data scientists collaborating over talent valuation metrics.

Predictive modeling for video streaming success

In the highly competitive streaming wars, acquiring a subscriber is only half the battle; keeping them is where the true war is won. Predictive models are essential for forecasting viewer churn and prescribing hyper-personalized content recommendations to maximize subscriber lifetime value (LTV). By analyzing viewing habits, the algorithm knows exactly when a user is likely to cancel their subscription. Before that happens, the system automatically surfaces a highly targeted recommendation—perhaps a niche documentary or an exclusive behind-the-scenes featurette—re-engaging the user and extending their LTV.

The strategic timing of content drops is another critical area where predictive modeling shines. Using data to optimize release schedules allows platforms to avoid competitor clashes and maximize marketing ROI. For example, if data indicates that a rival platform is dropping a massive fantasy epic on a Friday, predictive models might suggest counter-programming with a highly anticipated true-crime docuseries on a Wednesday, capturing a different audience segment while dominating the mid-week social media conversation.

Furthermore, predictive modeling dictates localization strategies. Streaming platforms use data to predict which domestic shows have the potential to become massive hits in specific international markets. By analyzing completion rates, binge-velocity (how fast a user watches an entire season), and re-watchability scores, platforms can decide where to allocate dubbing and localized marketing budgets. A show that achieves a high binge-velocity in the US might be fast-tracked for a localized release in Japan if the data shows a high cultural affinity for the genre.

Maximizing Subscriber Retention and Reducing Churn

Churn reduction is the holy grail of streaming. By leveraging machine learning to understand the subtle signs of viewer fatigue, platforms can dynamically adjust their interfaces. If a user has scrolled past 20 comedy titles without clicking, the predictive engine instantly pivots to displaying intense dramas, effectively breaking the cycle of decision paralysis.

Optimizing Release Schedules and Global Marketing ROI

Marketing budgets are finite, and data ensures they are spent efficiently. Predictive analytics can forecast exactly which social media channels will yield the highest conversion rates for a specific title, allowing marketing teams to optimize their ad spend globally and achieve maximum ROI for every campaign launched.

AI driven content strategy in entertainment: The 2027 Framework

As we look toward 2027, the rise of “Automated Greenlighting Systems” is perhaps the most controversial yet inevitable development. In this framework, AI acts as a co-executive, scoring pitches based on historical profitability and current market gaps. When a producer pitches a new series, the AI instantly cross-references the concept against a global database, calculating a projected success probability score. This doesn’t completely remove human executives from the equation, but it forces them to justify their decisions with hard data when going against the algorithmic recommendation.

Naturally, this shift brings significant ethical considerations and industry pushback. We’ve seen writer strikes and legal battles over copyright issues and algorithmic bias. There is a valid fear of “creative homogenization,” where algorithms only greenlight safe, predictable content. To combat this, the industry must adopt a framework for the “Human-AI Balance.” I firmly believe that AI should augment human creativity, not replace the nuanced art of storytelling. The algorithm can tell you that audiences want a story about a rogue detective, but only a human writer can give that detective a soul.

Brands and studios must align their proprietary AI content strategies with overarching industry technical standards for seamless distribution. By utilizing platforms like DataStream AI, creators can ensure that their data pipelines are transparent, ethical, and compliant with global standards. This alignment builds trust between creators and technologists, fostering an environment where data empowers rather than dictates.

The Rise of Automated Greenlighting Systems

These systems are not meant to be unfeeling gatekeepers. Instead, they serve as high-speed filters, capable of reading thousands of script submissions overnight and bubbling the most structurally sound and market-viable concepts up to human executives for final creative review.

Ethical Considerations and the Human-AI Balance

Maintaining the human element is non-negotiable. Algorithms are trained on the past, which means they struggle to predict entirely unprecedented cultural phenomena. The human-AI balance ensures that while data handles the probability of success, human intuition remains responsible for pushing the boundaries of what is possible in storytelling.

How Does data driven decision making streaming industry Leaders Rely On Work?

Top-tier streaming platforms maintain their market dominance by relying on incredibly sophisticated architectural data frameworks. These frameworks are designed to ingest, clean, and analyze data from a multitude of touchpoints simultaneously. It is not just about watching habits; it is about integrating cross-platform data. For instance, merging video game engagement data with video streaming habits is crucial to predicting transmedia franchise success. If a platform notices that players of a specific sci-fi RPG spend hours exploring the game’s lore, data-driven decision-making dictates that a spin-off television series exploring that exact lore will have a massive, guaranteed audience.

Industry leaders also use these data-driven insights to negotiate complex licensing deals and acquire external IP with high predicted ROI. When a platform bids on the rights to an old television catalog, they aren’t guessing its value. Their predictive models have already calculated exactly how many new subscribers that catalog will acquire and how many existing subscribers it will retain, allowing them to bid with absolute financial precision.

Moreover, extracting these deep viewer insights requires a strict adherence to maintaining data privacy and complying with global data protection regulations (like GDPR and CCPA). Streaming leaders invest heavily in anonymizing data protocols. They don’t need to know who you are specifically; they just need to know how a million people like you behave. This ethical approach to data harvesting is what sustains consumer trust in the streaming ecosystem.

Cross-Platform Data Integration for Transmedia Franchises

The future of entertainment is transmedia. By understanding how an audience moves from a comic book to a video game to a TV show, studios can create interconnected universes. Data integration allows creators to plant narrative seeds in one medium and harvest the emotional payoff in another, guided entirely by cross-platform behavioral analytics.

Navigating IP Acquisition and Licensing Deals

Data transforms IP acquisition from a gamble into a science. By forecasting the exact monetary value of a franchise’s secondary and tertiary characters, studios can negotiate licensing deals that maximize long-term profitability, ensuring that no potential revenue stream is left untapped.

A futuristic perspective of audiences engaging with dynamic content via spatial computing.

The future of content creation 2027: Where Do We Go From Here?

Looking ahead, the future will be defined by interactive, dynamic storytelling where predictive analytics alter narrative paths in real-time. Imagine a viewing experience where the pacing, soundtrack, and even the dialogue subtly shift based on your individual biometric or behavioral responses. If your smart device detects a drop in your heart rate, the algorithm seamlessly cues a more intense narrative sequence. This level of hyper-personalization represents the pinnacle of audience engagement.

Furthermore, the metaverse and spatial computing will introduce entirely new datasets for predictive content models to analyze. We will move beyond tracking clicks and watch-time to analyzing spatial awareness, avatar interaction, and immersive emotional presence. The ultimate goal for 2027 is achieving a frictionless pipeline from data-backed ideation to targeted global distribution, where every piece of content finds its perfect audience instantly.

For media executives and creators, the actionable next steps are clear. You must start building your predictive analytics infrastructure today. Partner with specialized brand solutions, integrate robust data pipelines, and begin training your creative teams to speak the language of analytics. The future belongs to those who can masterfully blend the art of storytelling with the science of data.

Interactive Storytelling and Real-Time Narrative Adaptation

Real-time adaptation will turn passive viewing into a personalized dialogue between the creator and the audience. As predictive analytics become faster and more integrated with edge computing, the media we consume will dynamically mold itself to our immediate psychological needs.

Final Thoughts for Studios, Creators, and Brand Solutions

The integration of predictive tools is no longer optional. Studios that resist this technological wave will find themselves outpaced by agile competitors who leverage data to optimize every facet of production. Embrace the data, trust the analytics, and let them elevate your creative vision.

Conclusion: Predictive Content Analytics: How Data-Driven Decision Making Will Define Hit Shows in 2027

In summary, the landscape of media is undergoing a monumental transformation. Predictive Content Analytics: How Data-Driven Decision Making Will Define Hit Shows in 2027 is not just a catchy concept; it is the definitive operational blueprint for the next decade of entertainment. By leveraging granular audience segmentation, NLP script deconstruction, and advanced predictive modeling, studios can mitigate financial risks while delivering hyper-personalized content that resonates on a global scale. As we navigate the delicate balance between human creativity and algorithmic precision, tools like DataStream AI will be paramount. Ultimately, the winners in the 2027 streaming wars will be those who harness the power of data not to replace the storyteller, but to give the storyteller the ultimate compass.


Frequently Asked Questions

What is predictive content analytics in the media industry?
Predictive content analytics involves the use of historical viewing data, machine learning algorithms, and real-time audience behavioral metrics to forecast the future success of media properties. It allows studios to transition from guessing what audiences want to prescribing exact narrative and production elements that ensure high engagement and profitability.

How do streaming platforms use data to predict hit TV shows?
Streaming platforms utilize a combination of script analysis via Natural Language Processing (NLP), granular audience segmentation, deep metadata tagging (analyzing color, pacing, and sentiment), and A/B testing of concepts with synthetic audiences. This data reveals the “content genome,” allowing platforms to reverse-engineer the elements of a hit show before filming begins.

Will data-driven decision-making replace human creativity in content creation by 2027?
No. Data-driven decision-making is designed to be a co-pilot, not a replacement. While algorithms are excellent at risk mitigation, audience targeting, and identifying market gaps, human creativity is required to provide the emotional nuance, original thought, and soul that make a story truly resonate. It is about achieving a Human-AI balance.

What are the most important metrics for forecasting video streaming success?
The most critical metrics include completion rates (how many viewers finish a series), binge-velocity (how quickly a season is consumed), subscriber acquisition cost (SAC), viewer retention/churn rates, and subscriber lifetime value (LTV). These metrics provide a comprehensive view of a show’s true financial and cultural impact.

How does big data reduce financial risks in TV production?
Big data allows studios to accurately predict audience demand, optimize pre-production budgets, and greenlight the right scripts with a higher probability of success. By forecasting resource needs and avoiding costly pilot failures through predictive modeling, studios can allocate their budgets far more efficiently, maximizing their overall return on investment.